Cyber Security Market
Cyber Security Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_703888 | Published On : September 25, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Cyber Security Market Size
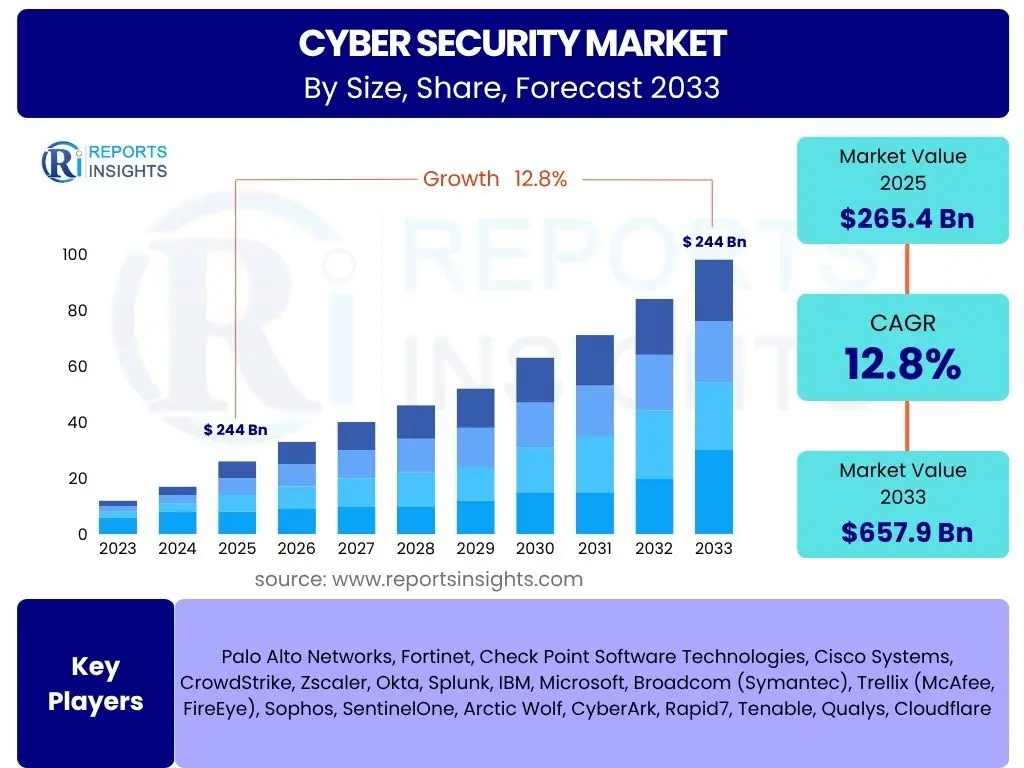
According to Reports Insights Consulting Pvt Ltd, The Cyber Security Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 10.8% between 2026 and 2034. The market is estimated at USD 240.35 Billion in 2026 and is projected to reach USD 548.72 Billion by the end of the forecast period in 2034.
Key Cyber Security Market Trends & Insights
The global cyber security landscape is currently undergoing a radical transformation driven by the integration of artificial intelligence and the decentralization of corporate networks. As organizations move toward hybrid work models and multi-cloud environments, the traditional perimeter-based security approach is being replaced by Zero Trust Architecture (ZTA). This shift is characterized by the principle of never trust, always verify, regardless of whether a user is inside or outside the network. Furthermore, the rise of Generative AI has created a dual-edged sword; while it enables sophisticated threat detection and automated response, it also empowers threat actors to develop highly convincing phishing campaigns and polymorphic malware. Market participants are increasingly focusing on Extended Detection and Response (XDR) and Security Orchestration, Automation, and Response (SOAR) to manage the overwhelming volume of security alerts and reduce mean time to respond (MTTR).
Regional dynamics play a crucial role in shaping market trends, with North America maintaining its dominance due to early adoption and the presence of major technology providers. However, the Asia-Pacific region is emerging as the fastest-growing market, fueled by rapid digitization in India, China, and Southeast Asia. The increasing frequency of state-sponsored cyber-attacks and ransomware-as-a-service (RaaS) models has forced governments worldwide to implement stringent data protection regulations, such as the GDPR in Europe and the CCPA in the United States, further driving investments in compliance and data privacy solutions. The convergence of Information Technology (IT) and Operational Technology (OT) is another significant trend, particularly in critical infrastructure sectors like energy and manufacturing, necessitating specialized security measures for Industrial Control Systems (ICS).
- Largest Region: North America remains the largest market, accounting for over 35% of the global share due to high technology penetration and rigorous regulatory frameworks.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, driven by government-led digital initiatives and increasing mobile connectivity.
- Leading Segment by Component: The Services segment holds the largest market share as enterprises require expert consultancy and managed services to navigate complex security environments.
- Dominant Deployment Mode: Cloud-based security solutions are outperforming on-premise deployments due to the scalability and cost-efficiency required for modern digital transformation.
- Key Sector Influence: The Banking, Financial Services, and Insurance (BFSI) sector remains the primary investor in cyber security, given the high sensitivity of financial data and the constant threat of digital fraud.
Key Takeaways Cyber Security Market Size & Forecast
The Cyber Security market is entering a phase of sustained high growth as digital assets become the primary drivers of economic value. The forecast period from 2025 to 2034 will be defined by the transition from reactive security measures to proactive, intelligence-led defense strategies. Organizations are moving away from siloed security products toward integrated platforms that offer holistic visibility across the entire digital ecosystem. This consolidation is driven by the need to reduce complexity and lower the total cost of ownership (TCO) while improving the overall security posture. Analysts emphasize that the growth in the market is not merely a response to threats but a fundamental requirement for the viability of the modern digital economy.
- Consistent CAGR: The steady 10.8% growth rate reflects the non-discretionary nature of security spending across all major industries.
- Market Valuation: Reaching nearly USD 550 Billion by 2034 indicates a doubling of the market size within a decade, highlighting the escalating stakes of digital protection.
- Strategic Shift: Identity and Access Management (IAM) is becoming the new security perimeter, with biometrics and multi-factor authentication seeing rapid adoption.
- Regulatory Impact: New and evolving data sovereignty laws in regions like the Middle East and Latin America are compelling multi-national firms to localise security operations.
- AI-Driven Security: By 2034, it is expected that over 70% of security operations will be automated through AI and machine learning algorithms to keep pace with automated threats.
Cyber Security Market Drivers Analysis
The primary driver for the cyber security market is the exponential increase in the frequency and sophistication of cyber-attacks, ranging from ransomware to supply chain compromises. As businesses undergo digital transformation, their attack surface expands significantly, incorporating cloud platforms, IoT devices, and remote access points. This expansion necessitates advanced security solutions capable of monitoring and protecting diverse environments. Additionally, the proliferation of strict regulatory mandates globally acts as a catalyst, as non-compliance can lead to massive financial penalties and irreparable brand damage.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increasing Sophistication of Ransomware Attacks | +3.2% | Global / North America | 2025 - 2034 |
| Rapid Adoption of Cloud Computing and SaaS | +2.8% | Asia-Pacific / Europe | 2025 - 2030 |
| Strict Data Privacy Regulations (GDPR, CCPA) | +2.1% | Europe / United States | 2025 - 2034 |
| Expansion of IoT and Connected Devices | +1.5% | China / South Korea / Japan | 2027 - 2034 |
Cyber Security Market Restraints Analysis
A significant restraint in the cyber security market is the critical shortage of skilled cyber security professionals, which hinders the ability of organizations to effectively deploy and manage sophisticated security tools. Furthermore, the high cost of implementation and maintenance for premium security suites can be prohibitive for small and medium-sized enterprises (SMEs). Integration challenges with legacy IT systems also pose a barrier, often creating vulnerabilities during the transition phase. Budget constraints in developing economies can slow down the adoption of advanced threat protection technologies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Cyber Professionals | -1.8% | United States / India / UK | 2025 - 2034 |
| High Cost of Advanced Security Solutions | -1.2% | Developing Nations (MEA, LATAM) | 2025 - 2029 |
| Complexity of Integrating Legacy Systems | -0.9% | Global | 2025 - 2030 |
Cyber Security Market Opportunities Analysis
The market presents significant opportunities in the development of AI-powered autonomous security systems that can predict and neutralize threats without human intervention. The transition toward Zero Trust Network Access (ZTNA) offers a lucrative path for vendors providing identity-centric security. Additionally, the growing focus on security-by-design in the development of hardware and software presents a massive market for embedded security solutions. The surge in demand for Managed Security Services (MSSP) allows vendors to cater to SMEs who prefer outsourcing their security operations to reduce internal overhead.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of AI and ML for Threat Hunting | +4.0% | Global / Technology Hubs | 2026 - 2034 |
| Zero Trust Network Access (ZTNA) Adoption | +3.5% | North America / Western Europe | 2025 - 2032 |
| Cyber Security Insurance Integration | +2.2% | United Kingdom / United States | 2026 - 2034 |
| Managed Security Service Providers (MSSP) Growth | +2.5% | India / Southeast Asia | 2025 - 2034 |
Cyber Security Market Challenges Impact Analysis
The primary challenge remains the asymmetry of cyber warfare, where attackers only need to succeed once while defenders must be successful every time. The rise of deepfakes and AI-generated social engineering poses a psychological challenge that technical barriers struggle to address. Furthermore, the increasing complexity of multi-cloud environments makes achieving uniform security visibility difficult. Geopolitical tensions also contribute to a fragmented security landscape, with certain technologies being banned or restricted in various jurisdictions, complicating global operations for multi-national corporations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Evolution of Deepfakes and AI-Phishing | -1.5% | Global | 2025 - 2034 |
| Fragmented Global Regulatory Compliance | -1.1% | Multi-national Corporations | 2025 - 2034 |
| Quantum Computing Threats to Encryption | -0.8% | Global / Research Centers | 2028 - 2034 |
Cyber Security Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global cyber security market, encompassing various segments including hardware, software, and services across multiple industry verticals. It evaluates the impact of emerging technologies like AI, blockchain, and 5G on the threat landscape and defensive capabilities. The scope includes historical data analysis from 2020 to 2024, a detailed assessment of the 2025 base year, and a robust forecast methodology for the period 2026 to 2034. It covers competitive benchmarking of key players and regional insights to help stakeholders make informed investment decisions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 216.92 Billion |
| Market Forecast in 2034 | USD 548.72 Billion |
| Growth Rate | 10.8% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Cisco Systems, Inc., Palo Alto Networks, Inc., Fortinet, Inc., CrowdStrike Holdings, Inc., Check Point Software Technologies Ltd., Microsoft Corporation, IBM Corporation, Trend Micro Incorporated, Zscaler, Inc., Okta, Inc., Broadcom Inc. (Symantec), Trellix (McAfee & FireEye), SentinelOne, Inc., Sophos Ltd., Proofpoint, Inc., Rapid7, Inc., Akamai Technologies, Darktrace plc, F5, Inc., Cloudflare, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the cyber security market allows for a precise understanding of which areas are driving growth and where technological investment is most concentrated. The market is broadly categorized into components, security types, deployment modes, and industry verticals. Currently, the Software segment is undergoing rapid evolution as on-premise solutions are phased out in favor of cloud-native applications that offer better integration with contemporary digital infrastructures. The Services segment is also seeing significant traction as organizations struggle to find internal talent and instead rely on external experts for everything from incident response to security audits.
Among security types, Cloud Security is projected to witness the highest growth rate as more enterprises transition their core operations to public and private clouds. Network security remains the foundational layer of protection, but its focus is shifting toward software-defined perimeters. Application security is gaining prominence due to the rise in mobile app usage and the integration of security within the DevOps lifecycle (DevSecOps). Large enterprises continue to lead in terms of total spending, but the SME segment is expected to show robust growth as affordable, scalable SaaS-based security solutions become more widely available.
- By Component: Hardware, Software (Identity and Access Management, Antivirus/Antimalware, Firewall, Intrusion Detection/Prevention, Encryption), Services (Professional Services, Managed Security Services).
- By Security Type: Network Security, Endpoint Security, Application Security, Cloud Security, Infrastructure Protection, Data Security.
- By Deployment Mode: On-premise, Cloud-based (Public, Private, Hybrid).
- By Organization Size: Small and Medium-sized Enterprises (SMEs), Large Enterprises.
- By Industry Vertical: BFSI, Government and Defense, Healthcare, IT and Telecom, Manufacturing, Retail, Energy and Utilities, Others.
Regional Highlights
- North America: Currently the largest market due to high cyber security awareness, the presence of major security vendors, and strict government regulations such as the Executive Order on Improving the Nations Cybersecurity.
- Asia-Pacific: Recognized as the fastest-growing region with a high CAGR, driven by rapid urbanization, digital government initiatives in India and China, and the expansion of the regional manufacturing sector.
- Europe: A mature market focused heavily on data privacy and sovereign cloud initiatives, with Germany, France, and the UK leading the adoption of GDPR-compliant security frameworks.
- Middle East and Africa: Experiencing growth due to investments in smart city projects and the need to protect critical oil and gas infrastructure from state-sponsored threats.
- Latin America: Showing steady growth as countries like Brazil and Mexico improve their digital banking security and enact new national data protection laws.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cyber Security Market.- Cisco Systems, Inc.
- Palo Alto Networks, Inc.
- Fortinet, Inc.
- CrowdStrike Holdings, Inc.
- Check Point Software Technologies Ltd.
- Microsoft Corporation
- IBM Corporation
- Trend Micro Incorporated
- Zscaler, Inc.
- Okta, Inc.
- Broadcom Inc. (Symantec)
- Trellix
- SentinelOne, Inc.
- Sophos Ltd.
- Proofpoint, Inc.
- Rapid7, Inc.
- Akamai Technologies
- Darktrace plc
- F5, Inc.
- Cloudflare, Inc.
Frequently Asked Questions
What is the projected size of the Cyber Security market by 2034?
The global cyber security market is projected to reach approximately USD 548.72 Billion by 2034, growing at a CAGR of 10.8% from 2025.
Which region is expected to grow the fastest in the Cyber Security market?
The Asia-Pacific (APAC) region is expected to exhibit the fastest growth rate due to rapid digitization, increasing internet penetration, and government-led cybersecurity initiatives.
What are the primary drivers for the Cyber Security market growth?
Key drivers include the rising frequency of ransomware attacks, the shift to cloud computing, and the necessity of complying with strict global data privacy regulations.
How is AI impacting the Cyber Security market?
AI is being used to automate threat detection and response, improving efficiency for security teams, but it is also being used by attackers to create more sophisticated malware.
What are the biggest challenges facing the Cyber Security industry?
The industry faces a significant shortage of skilled personnel, high costs for advanced solutions, and the increasing complexity of multi-cloud and remote work environments.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
