Corrugated Board Market
Corrugated Board Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710952 | Published On : September 21, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Corrugated Board Market Size
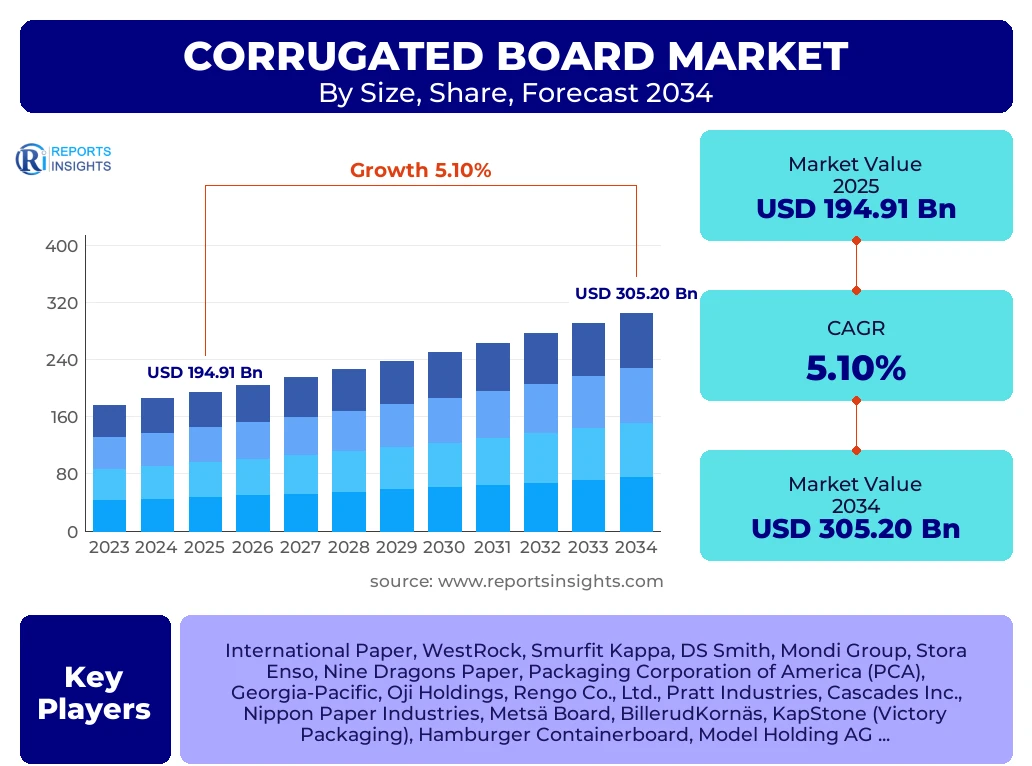
According to Reports Insights Consulting Pvt Ltd, The Corrugated Board Market is projected to grow at a Compound Growth Rate (CAGR) of 5.1% between 2026 and 2034. The market is estimated at USD 204.85 Billion in 2026 and is projected to reach USD 305.20 Billion by the end of the forecast period in 2034.
Key Corrugated Board Market Trends & Insights
The corrugated board industry is currently undergoing a significant transformation driven by the global shift toward sustainable packaging and the exponential growth of digital commerce. Consumers and regulatory bodies are increasingly demanding fiber-based alternatives to single-use plastics, positioning corrugated board as the primary choice for secondary and tertiary packaging. Furthermore, the integration of advanced digital printing technologies is allowing for high-quality graphics and personalized packaging, which is becoming a vital tool for brand differentiation in the retail sector. The market is also seeing a move toward lightweighting—reducing the weight of the board without compromising structural integrity—to minimize shipping costs and environmental impact.
- Largest Region: Asia-Pacific remains the dominant global force, accounting for over 40% of the total market share due to massive manufacturing outputs in China and India.
- Fastest Growing Region: Southeast Asia and parts of Africa are experiencing the most rapid growth, fueled by rising middle-class consumption and developing retail infrastructure.
- Largest Segment by Flute Type: C-Flute remains the most widely used segment due to its excellent cushioning and stacking properties for shipping containers.
- Largest Segment by End-User: The Food and Beverage industry is the primary consumer, utilizing corrugated board for bulk transport and retail-ready displays.
- Emerging Trend: Smart packaging integration, including QR codes and RFID tags printed directly onto corrugated surfaces, is gaining traction for supply chain transparency.
Key Takeaways Corrugated Board Market Size & Forecast
The forecast period from 2025 to 2034 suggests a robust trajectory for the corrugated board market, underpinned by structural shifts in global logistics. As the e-commerce sector matures, there is an increasing reliance on durable yet recyclable packaging that can withstand multiple touchpoints in the last-mile delivery process. This demand is particularly strong in developed economies where circular economy mandates are being strictly enforced. Investors and stakeholders are focusing on vertical integration, where paper mills and converting plants are optimized for energy efficiency to offset the rising costs of raw materials and carbon taxes.
- China Dominance: China continues to be the world's largest producer and consumer of corrugated board, driven by its internal domestic market and its role as a global export hub.
- E-commerce Impact: The surge in direct-to-consumer shipping is expected to contribute nearly 30% of the incremental growth in the corrugated market over the next decade.
- Sustainability Mandates: European Union regulations regarding packaging waste are forcing a transition from plastic-heavy protective packaging to 100% recyclable corrugated inserts.
- Investment in Recycled Content: Leading manufacturers are shifting their portfolio toward 100% recycled testliners to meet corporate ESG goals.
- Technological Advancement: The adoption of high-speed digital inkjet presses is reducing lead times for small-batch customized packaging orders.
Corrugated Board Market Drivers Analysis
The primary driver for the corrugated board market is the relentless expansion of the e-commerce landscape. Unlike traditional retail, e-commerce requires significantly more packaging per unit to ensure product safety during complex shipping routes. Additionally, the global push for plastic substitution is a major catalyst. As brands seek to enhance their environmental credentials, they are replacing expanded polystyrene (EPS) and plastic shrink wraps with innovative corrugated designs. The versatility of corrugated board, being both lightweight and high-strength, makes it an indispensable component of modern industrial supply chains.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| E-commerce Proliferation | +1.8% | Global (High in US, China) | 2025-2034 |
| Sustainability & Plastic Substitution | +1.2% | Europe, North America | 2025-2030 |
| Growth in Food & Beverage Industry | +0.9% | India, Brazil, Southeast Asia | 2026-2034 |
Corrugated Board Market Restraints Analysis
The market faces significant headwinds from the volatility of raw material prices, specifically wood pulp and recovered paper. Fluctuations in energy costs also impact the operational margins of paper mills, which are highly energy-intensive. Furthermore, the increasing popularity of flexible packaging in certain niche food applications poses a competitive threat, as flexible pouches often require less space and have a lower carbon footprint in terms of transportation weight compared to rigid corrugated boxes.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -0.6% | Global | Ongoing |
| Competition from Flexible Packaging | -0.4% | Developed Markets | 2025-2034 |
Corrugated Board Market Opportunities Analysis
Significant opportunities exist in the development of moisture-resistant and antimicrobial corrugated coatings, which can expand the board's utility in the fresh produce and pharmaceutical sectors. Furthermore, the rise of "unboxing experiences" as a marketing tool provides an opportunity for high-end corrugated solutions with premium printing finishes. The industrialization of emerging economies in Africa and South Asia also presents a vast untapped market for standardized shipping containers and bulk packaging solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Digital Printing & Personalization | +0.7% | North America, Europe | 2026-2032 |
| Bio-based Barrier Coatings | +0.5% | Western Europe, Japan | 2027-2034 |
Corrugated Board Market Challenges Impact Analysis
One of the most pressing challenges is the supply chain disruption regarding the availability of high-quality recycled fibers. As more industries compete for recycled paper, the quality of the fiber degrades over multiple recycling cycles, requiring a delicate balance with virgin fibers to maintain strength. Additionally, strict environmental regulations regarding wastewater treatment in paper mills are increasing capital expenditure requirements for manufacturers, particularly in developing regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fiber Quality Degradation | -0.3% | Global | 2030-2034 |
| Stringent Environmental Compliance | -0.4% | China, India, EU | 2025-2028 |
Corrugated Board Market - Updated Report Scope
This report provides an exhaustive analysis of the global corrugated board landscape, covering the entire value chain from raw material sourcing to end-use applications. It evaluates the impact of macroeconomic factors such as inflation and trade policies on market dynamics. The scope includes a detailed breakdown of flute types, wall constructions, and printing technologies across six major geographic regions, ensuring a 360-degree view for strategic decision-making.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 194.91 Billion |
| Market Forecast in 2034 | USD 305.20 Billion |
| Growth Rate | 5.1% CAGR |
| Number of Pages | 256 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | International Paper, WestRock, Smurfit Kappa, DS Smith, Mondi Group, Stora Enso, Nine Dragons Paper, Packaging Corporation of America (PCA), Georgia-Pacific, Oji Holdings, Rengo Co., Ltd., Pratt Industries, Cascades Inc., Nippon Paper Industries, Metsä Board, BillerudKornäs, KapStone (Victory Packaging), Hamburger Containerboard, Model Holding AG, Thai Containers Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The corrugated board market is segmented based on structural characteristics and functional applications. The wall type is a critical differentiator, with Single Wall board being the most common for standard shipping boxes, while Double and Triple Wall boards are reserved for heavy-duty industrial equipment and bulk transport. Flute profiles are selected based on the specific need for cushioning versus printability, with finer flutes like E and F gaining popularity in primary consumer packaging due to their smooth surface and excellent graphic reproduction capabilities.
- By Flute Type: Includes A, B, C, E, and F flutes, each offering different levels of compression strength and thickness.
- By Board Style: Categorized into Single Face (flexible wrap), Single Wall (standard), Double Wall (heavy duty), and Triple Wall (extreme durability).
- By Printing Technology: Flexography, Offset Lithography, and Digital Printing.
- By End-Use Industry: Detailed analysis across Food & Beverage, E-commerce, Electronics, Pharmaceuticals, and Industrial sectors.
Regional Highlights
- Asia-Pacific: The largest market globally, driven by China's massive manufacturing sector and the rapid digitalization of retail in India and Southeast Asia. The region benefits from high production capacities and a growing domestic consumer base.
- North America: A highly mature market focused on innovation in e-commerce logistics and sustainable materials. The United States is a leader in high-end corrugated graphics and retail-ready packaging.
- Europe: The pioneer in circular economy initiatives, Europe has the highest recycling rates for corrugated board and stringent regulations favoring fiber-based packaging over plastics.
- Latin America: Expected to show steady growth fueled by the agricultural export sectors in Brazil and Argentina, which require significant amounts of corrugated packaging for fresh produce.
- Middle East & Africa: An emerging market where infrastructure development and the rise of organized retail are creating new demand for standardized corrugated solutions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Corrugated Board Market.- International Paper
- WestRock
- Smurfit Kappa
- DS Smith
- Mondi Group
- Stora Enso
- Nine Dragons Paper
- Packaging Corporation of America (PCA)
- Georgia-Pacific
- Oji Holdings
- Rengo Co., Ltd.
- Pratt Industries
- Cascades Inc.
- Nippon Paper Industries
- Metsä Board
- BillerudKornäs
- Hamburger Containerboard
- Model Holding AG
- Thai Containers Group
- Lee & Man Paper Manufacturing
Frequently Asked Questions
What is driving the growth of the Corrugated Board Market?
The primary growth drivers are the expansion of the e-commerce sector and the global movement to replace single-use plastics with sustainable, recyclable fiber-based packaging solutions.
Which region holds the largest share of the Corrugated Board Market?
The Asia-Pacific region currently holds the largest market share, accounting for over 40% of global consumption, led primarily by China, India, and Japan.
How is digital printing impacting the corrugated board industry?
Digital printing allows for shorter production runs, high-quality graphics, and personalization, which enables brands to create limited-edition packaging and improve consumer engagement.
What are the main challenges for corrugated board manufacturers?
Key challenges include the volatility of raw material prices (pulp and recycled paper), rising energy costs for production, and maintaining fiber quality through multiple recycling loops.
What is the expected CAGR of the market through 2034?
The Corrugated Board Market is expected to grow at a CAGR of 5.1% from 2025 to 2034, driven by industrialization and sustainable packaging trends.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted