Contract Glazing Market
Contract Glazing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711405 | Published On : October 31, 2026 |
Format : 


 | Author : Erika Grotto
Contract Glazing Market Size
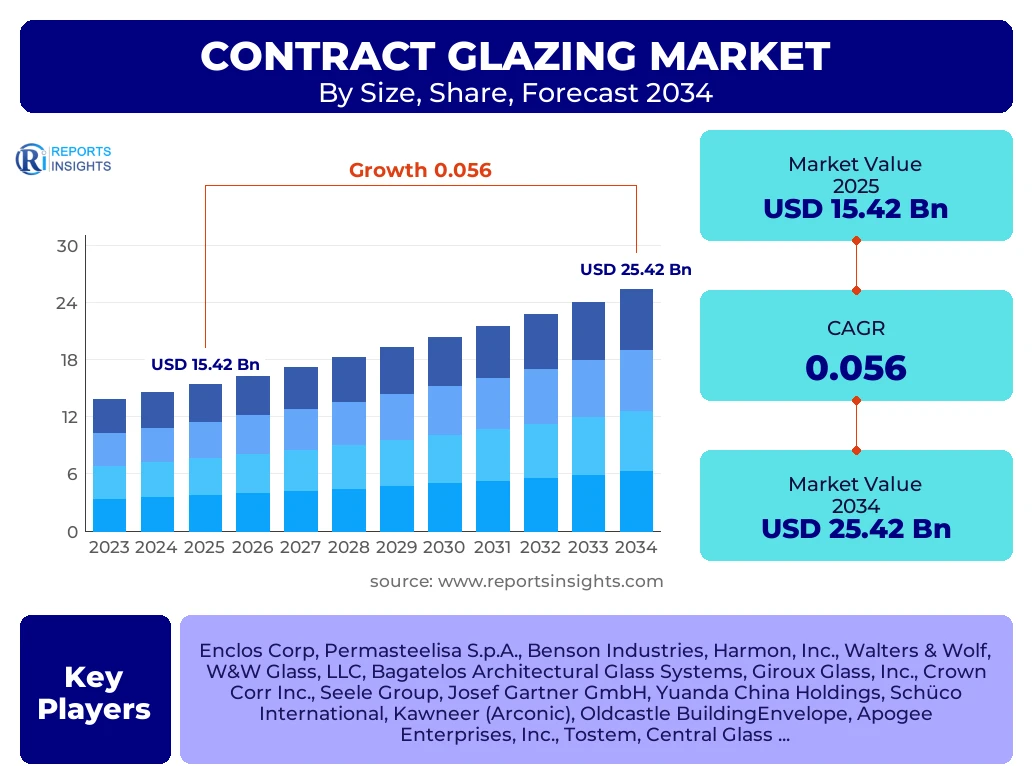
According to Reports Insights Consulting Pvt Ltd, The Contract Glazing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.6% between 2025 and 2034. The market is estimated at USD 16.28 Billion in 2026 and is projected to reach USD 25.42 Billion by the end of the forecast period in 2034.
Key Contract Glazing Market Trends & Insights
The contract glazing market is currently undergoing a significant transformation driven by the integration of advanced materials and digital fabrication technologies. Industry stakeholders are increasingly prioritizing high-performance building envelopes that contribute to carbon neutrality goals. Regional insights indicate that while North America and Europe remain hubs for technological innovation in glazing systems, the Asia-Pacific region is experiencing the most rapid expansion due to massive infrastructure projects. Competitive benchmarking reveals that leading firms are shifting from traditional onsite assembly to modular, unitized systems that reduce labor costs and improve installation precision. The market is also seeing a rise in smart glass applications, where glazing systems respond dynamically to environmental conditions to optimize energy consumption.
- Largest Region: Asia-Pacific currently holds the largest market share, driven by rapid urbanization and large-scale commercial developments in China and India.
- Fastest Growing Region: Southeast Asia and parts of the Middle East are projected to exhibit the highest CAGR due to emerging smart city initiatives.
- Leading Segment: The Commercial Building segment remains the largest contributor in terms of revenue, specifically high-rise office towers and mixed-use developments.
- Material Trend: High-performance Low-E glass combined with thermally broken aluminum frames dominates the premium contract glazing space.
Key Takeaways Contract Glazing Market Size & Forecast
The forecast period from 2025 to 2034 suggests a steady upward trajectory for the contract glazing industry, fueled by both new construction and the retrofitting of aging structures. Analysis of user inquiries and market data highlights a critical focus on the lifecycle cost of glazing systems rather than just the initial capital expenditure. Investors and developers are increasingly looking for contract glazers who can provide end-to-end solutions, including design-assist services and long-term maintenance. The shift toward sustainable architecture, mandated by stricter building codes in the European Union and North America, is a primary catalyst for the adoption of triple-pane glazing and vacuum-insulated glass (VIG) technologies.
- Dominant Country: The United States leads in terms of value within the North American market, particularly in the renovation of institutional and commercial buildings.
- Sector Growth: The institutional sector, encompassing healthcare and education, is showing resilient growth as facilities upgrade to improve occupant wellness and energy efficiency.
- Strategic Shift: Prefabrication and off-site manufacturing are becoming standard practices among top-tier contract glazers to mitigate onsite risks.
- Financial Outlook: Sustained investment in green building certifications (LEED, BREEAM) is directly correlating with higher contract values for specialized glazing firms.
Contract Glazing Market Drivers Analysis
The primary engine behind the growth of the contract glazing market is the global movement toward energy-efficient building envelopes. Governments worldwide are implementing more stringent thermal performance standards, forcing developers to utilize advanced glazing solutions that minimize heat gain and loss. Furthermore, the aesthetic trend of maximizing natural light in modern architecture continues to favor large-span glass installations, increasing the demand for complex curtain wall systems that only specialized contract glazers can execute.
Another significant driver is the recovery and expansion of the global tourism and hospitality industry, leading to the construction of iconic hotel structures and airports. These projects typically require customized, high-specification glazing that includes acoustic insulation and high structural integrity. The rise of "biophilic design" also plays a role, as architects use glass to blur the lines between indoor and outdoor environments, necessitating larger and clearer glazing units.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stricter Energy Efficiency Regulations | +1.8% | European Union and North America | 2025 - 2034 |
| Urbanization and High-Rise Construction | +1.5% | China, India, and Southeast Asia | 2025 - 2030 |
| Growth in Institutional Infrastructure | +1.2% | Global | 2026 - 2034 |
| Technological Advancements in Smart Glass | +0.9% | United States and Japan | 2027 - 2034 |
Contract Glazing Market Restraints Analysis
Despite the positive growth outlook, the contract glazing market faces significant hurdles, most notably the volatility of raw material prices. The cost of aluminum and float glass is susceptible to energy price fluctuations and trade policies, which can erode the profit margins of fixed-price contracts. Additionally, the industry is grappling with a severe shortage of skilled labor, particularly experienced glaziers and project managers capable of handling complex, large-scale installations.
Environmental regulations regarding the manufacturing of glass also act as a restraint, as the production process is energy-intensive. Increasing carbon taxes and environmental compliance costs are being passed down the supply chain, potentially slowing down project approvals in price-sensitive markets. Furthermore, logistical challenges in transporting oversized or fragile glass units add to the complexity and cost of global glazing projects.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -1.1% | Global | 2025 - 2028 |
| Skilled Labor Shortages | -0.9% | North America and Western Europe | 2025 - 2034 |
| High Transportation Costs for Oversized Units | -0.6% | Global | 2026 - 2030 |
Contract Glazing Market Opportunities Analysis
The burgeoning market for building retrofits presents a massive opportunity for contract glazers. As cities strive to meet net-zero targets, millions of square feet of existing commercial space require glazing upgrades to improve insulation. This "re-glazing" market is less dependent on new construction cycles and provides a steady stream of revenue. Moreover, the integration of Building Integrated Photovoltaics (BIPV) into glazing systems allows contract glazers to position themselves as providers of energy-generating facades.
The expansion of data centers and specialized industrial facilities also offers new niches. These buildings require glazing solutions that offer high security, fire resistance, and specific thermal management properties. By diversifying into these specialized sectors, contract glazing firms can reduce their exposure to the cyclical nature of the residential and general commercial markets. Additionally, the adoption of digital twins and Building Information Modeling (BIM) allows for more efficient project execution and opens doors for advanced maintenance contracts.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Energy Retrofitting of Existing Buildings | +2.1% | Europe and United States | 2025 - 2034 |
| Building Integrated Photovoltaics (BIPV) | +1.4% | Germany, Japan, and China | 2027 - 2034 |
| Specialized Security and Fire-Rated Glazing | +0.8% | Global (Middle East focus) | 2026 - 2032 |
Contract Glazing Market Challenges Impact Analysis
One of the most persistent challenges is the increasing complexity of architectural designs, which often outpaces the standard capabilities of glazing materials. Contract glazers must invest heavily in R&D and engineering to ensure that ambitious glass designs meet structural and safety requirements. This leads to longer lead times and higher risks during the installation phase. Supply chain disruptions also continue to pose a threat, particularly for specialized coatings and high-end hardware sourced from limited global suppliers.
Competition from low-cost regional players is another challenge for established international firms. In developing markets, price often takes precedence over long-term durability, leading to the use of inferior glazing systems. This creates a fragmented market where premium glazers must constantly demonstrate the value of their higher-priced, high-performance systems. Lastly, the rapid pace of technological change requires continuous retraining of the workforce to stay proficient in new installation techniques and software tools.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Fragmentation | -0.7% | Global | 2025 - 2027 |
| Increased Project Complexity | -0.5% | Global | 2025 - 2034 |
| Price Competition in Emerging Markets | -0.4% | APAC and Latin America | 2026 - 2030 |
Contract Glazing Market - Updated Report Scope
This report provides an exhaustive analysis of the contract glazing industry, covering a wide range of glazing types, materials, and end-use sectors. It investigates the market dynamics across six major geographical regions, providing detailed insights into the regulatory landscapes and construction trends affecting the industry. The scope includes a deep dive into the value chain, from glass fabrication to onsite installation, highlighting the role of technological integration in modern facade engineering.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 15.42 Billion |
| Market Forecast in 2034 | USD 25.42 Billion |
| Growth Rate | 5.6% CAGR |
| Number of Pages | 258 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Enclos Corp, Permasteelisa S.p.A., Benson Industries, Harmon, Inc., Walters & Wolf, W&W Glass, LLC, Bagatelos Architectural Glass Systems, Giroux Glass, Inc., Crown Corr Inc., Seele Group, Josef Gartner GmbH, Yuanda China Holdings, Schüco International, Kawneer (Arconic), Oldcastle BuildingEnvelope, Apogee Enterprises, Inc., Tostem, Central Glass, Vitro, AGC Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The contract glazing market is categorized by the method of installation, the type of material used, and the final application. The "Unitized Curtain Wall" segment is currently the fastest-growing sub-segment within the commercial sector due to its ability to be pre-assembled in a controlled factory environment, which significantly speeds up the construction timeline and ensures higher quality control. This is particularly relevant for high-rise buildings in dense urban areas where onsite staging space is limited.
In terms of materials, Aluminum frames remain the industry standard due to their strength-to-weight ratio and corrosion resistance. However, there is a growing interest in hybrid systems that incorporate timber for aesthetic and sustainability reasons. The glass segment itself is diversifying, with laminated and tempered glass seeing high demand for safety and acoustic purposes, while Low-E coatings are now a standard requirement for thermal efficiency in most jurisdictions.
- By Type:
- Unitized Systems (Pre-fabricated panels)
- Stick-built Systems (On-site assembly)
- Storefront and Entrance Systems
- Point-supported Glass (Spider glazing)
- Skylights and Sloped Glazing
- By Material:
- Aluminum Frame Glazing
- Steel Frame Glazing
- Wood/Timber Frame Glazing
- Advanced Glass Types (Self-cleaning, Smart Glass)
- By End-Use:
- Commercial (Offices, Retail, Hotels)
- Institutional (Healthcare, Education, Government)
- Residential (Multi-family high-rise)
- Industrial and Transportation (Airports, Factories)
Regional Highlights
- North America: The market is characterized by a strong focus on high-performance retrofitting in cities like New York and Chicago. The US remains a leader in adopting advanced glazing technologies.
- Europe: Germany and the UK are the primary drivers, with strict environmental regulations (Energy Performance of Buildings Directive) pushing the demand for triple glazing and passive house standards.
- Asia-Pacific: This is the largest and most dynamic region. China dominates global glass production and is also the largest consumer, while India is seeing a surge in demand for commercial glazing for its expanding IT and finance sectors.
- Middle East: The region is known for iconic architectural projects that utilize high-specification, heat-reflective glazing to combat extreme temperatures. Saudi Arabia's Vision 2030 projects are a major future driver.
- Latin America: Growth is concentrated in Brazil and Mexico, primarily in the luxury residential and commercial hospitality sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Contract Glazing Market.
- Enclos Corp
- Permasteelisa S.p.A.
- Benson Industries (MiTek)
- Harmon, Inc. (Apogee Enterprises)
- Walters & Wolf
- W&W Glass, LLC
- Bagatelos Architectural Glass Systems
- Giroux Glass, Inc.
- Crown Corr Inc.
- Seele Group
- Josef Gartner GmbH
- Yuanda China Holdings Limited
- Schüco International KG
- Kawneer (Arconic Corporation)
- Oldcastle BuildingEnvelope (CRH plc)
- Tostem (LIXIL Group)
- Central Glass Co., Ltd.
- Vitro Architectural Glass
- AGC Inc.
- Saint-Gobain Glass
Frequently Asked Questions
What is the difference between unitized and stick-built contract glazing?
Unitized glazing involves pre-assembling large glass panels in a factory before shipping them to the site for installation, which is faster and higher quality. Stick-built glazing involves assembling the frames and glass piece-by-piece on the building site, offering more flexibility for custom designs but requiring more onsite labor.
How is the push for net-zero buildings affecting the contract glazing market?
The net-zero movement is driving demand for ultra-high-performance glazing, such as triple-pane units, vacuum-insulated glass, and BIPV. Contract glazers are now required to provide detailed thermal modeling and carbon footprint data for their systems to help buildings meet strict certification standards.
Which sector is currently the largest consumer of contract glazing services?
The commercial sector, including office buildings, retail centers, and hotels, remains the largest consumer. However, the institutional sector (hospitals and schools) is growing rapidly due to public investments in infrastructure and a focus on occupant health and natural lighting.
What are the main cost drivers in a contract glazing project?
Main cost drivers include raw material prices (aluminum and glass), specialized coatings (Low-E), labor for installation, and engineering complexity. Logistics and the use of heavy machinery for high-rise installations also significantly impact the final contract value.
Is smart glass becoming a standard in contract glazing?
While smart glass (electrochromic glass) is growing in popularity due to its ability to control light and heat dynamically, it is currently used mostly in premium or flagship commercial projects. Its adoption is expected to increase as manufacturing costs decrease and its energy-saving benefits are better quantified.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
