Connected Aircraft Market
Connected Aircraft Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711642 | Published On : November 10, 2026 |
Format : 


 | Author : Ashraf Shehata
Connected Aircraft Market Size
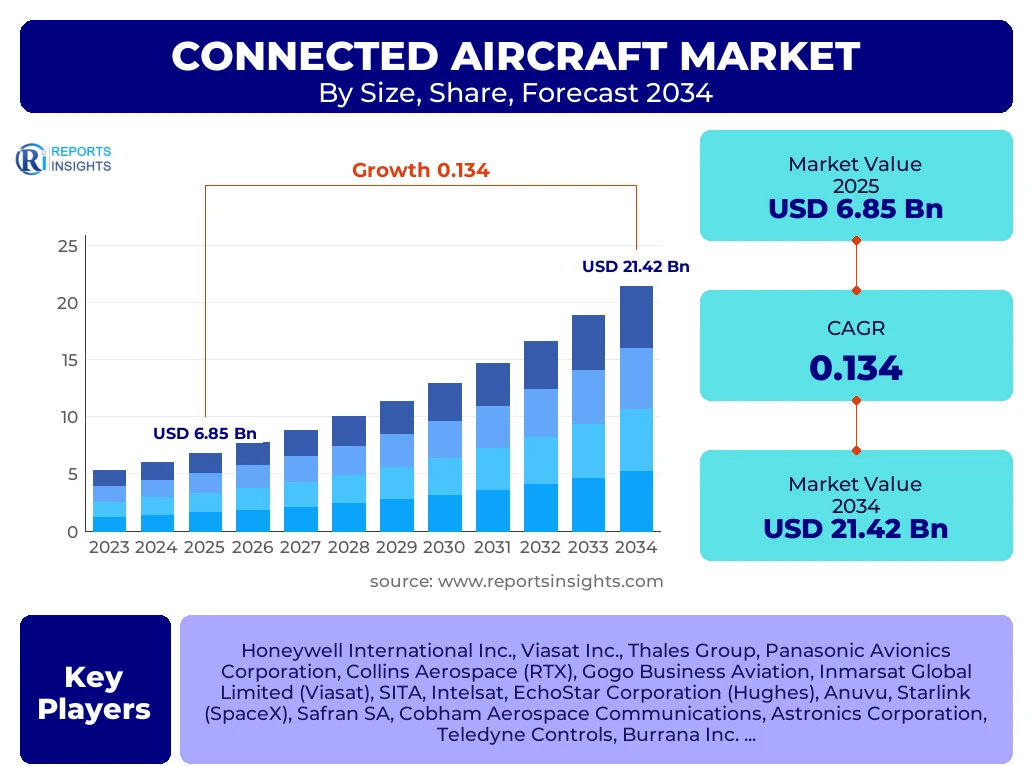
According to Reports Insights Consulting Pvt Ltd, The Connected Aircraft Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.4% between 2025 and 2034. The market is estimated at USD 7.78 Billion in 2026 and is projected to reach USD 21.42 Billion by the end of the forecast period in 2034.
Key Connected Aircraft Market Trends & Insights
The global connected aircraft landscape is undergoing a profound transformation driven by the convergence of advanced satellite communication (SATCOM) and the aviation industry’s shift toward data-centric operations. Current market intelligence indicates that the integration of Low Earth Orbit (LEO) satellite constellations is the most significant trend, offering lower latency and higher bandwidth compared to traditional Geostationary (GEO) systems. This shift is enabling airlines to provide "at-home" connectivity experiences to passengers while simultaneously feeding real-time telemetry data to ground-based maintenance teams. Strategic benchmarking reveals that market leaders are increasingly focusing on multi-orbit solutions that combine the coverage of GEO with the speed of LEO to ensure seamless global roaming, particularly over polar routes where connectivity was historically intermittent.
- Largest Region: North America currently holds the largest market share, driven by a mature aviation infrastructure and the presence of major connectivity providers like Viasat and Gogo.
- Fastest Growing Region: Asia-Pacific is documented as the fastest-growing region, fueled by the rapid expansion of middle-class air travel in India and China and the modernization of regional airline fleets.
- Largest Segment: Commercial Aviation remains the dominant segment by value, accounting for over 65% of the market share as airlines prioritize In-Flight Connectivity (IFC) as a key competitive differentiator.
- Technology Trend: The adoption of Ka-band and Ku-band high-throughput satellites (HTS) is accelerating, providing the necessary infrastructure for data-intensive applications.
- Operational Insight: Beyond passenger Wi-Fi, there is a surging trend toward "Digital Cockpit" solutions that utilize real-time weather updates and flight path optimization to reduce fuel consumption.
Key Takeaways Connected Aircraft Market Size & Forecast
The market trajectory for connected aircraft is characterized by a steady upward momentum, supported by a significant backlog of aircraft orders and a growing retrofit market for aging narrow-body and wide-body fleets. Market analysis highlights that the transition from legacy Air-to-Ground (ATG) systems to advanced satellite-based hardware is a primary revenue driver. Furthermore, the defense sector is increasingly investing in connected platforms to facilitate Network-Centric Warfare (NCW) capabilities, ensuring that military assets remain synchronized in real-time across contested environments. The forecast period anticipates a move toward software-defined cabins, where connectivity hardware becomes standardized, and value-added services provide the primary margin for service providers.
- Leading Country: The United States leads the global market, supported by massive investments in both commercial IFC and military secure-communications.
- Fleet Modernization: Over 40% of the current global commercial fleet is expected to undergo connectivity retrofitting by 2030.
- Data Utilization: Predictive maintenance facilitated by connected sensors is projected to reduce airline operational costs by up to 5% annually by 2034.
- Market Maturity: While narrow-body aircraft are the primary volume drivers for hardware installation, wide-body aircraft generate higher service revenue due to longer flight durations and higher data consumption.
- Strategic Partnerships: Collaboration between satellite operators and aircraft OEMs (Boeing and Airbus) is becoming essential for line-fit connectivity solutions.
Connected Aircraft Market Drivers Analysis
The expansion of the connected aircraft market is fundamentally propelled by the exponential rise in passenger demand for high-speed, ubiquitous internet access during transit. In the modern era, connectivity is no longer viewed as a luxury but as a basic utility, compelling airlines to invest in advanced hardware to maintain brand loyalty and capture high-value business travelers. Additionally, the drive for operational efficiency is a critical catalyst; airlines are leveraging real-time data streaming to optimize flight routes, monitor engine health, and reduce turnaround times at airports. This dual-purpose utility—enhancing passenger experience and optimizing fleet performance—creates a robust investment case for aviation stakeholders across the globe.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Demand for In-Flight Connectivity (IFC) | +4.2% | Global | 2025 - 2034 |
| Implementation of LEO Satellite Constellations | +3.5% | North America & Europe | 2026 - 2030 |
| Operational Efficiency & Predictive Maintenance | +2.8% | Asia-Pacific & MEA | 2025 - 2034 |
| Modernization of Military Communication Systems | +2.1% | United States & China | 2025 - 2028 |
Connected Aircraft Market Restraints Analysis
Despite the optimistic growth projections, the market faces significant headwinds related to the high capital expenditure required for both line-fit and retrofit installations. The technical complexity of installing radomes and wiring on existing airframes involves substantial downtime, which translates to lost revenue for airlines. Furthermore, the industry is navigating a complex regulatory landscape where different jurisdictions have varying standards for radio frequency allocations and cybersecurity protocols. Concerns over data privacy and the potential for cyber-attacks on flight control systems remain a major deterrent for certain stakeholders, necessitating expensive and time-consuming certification processes.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Installation and Maintenance Costs | -2.5% | Emerging Markets (LAMEA) | 2025 - 2030 |
| Cybersecurity Risks & Data Privacy Regulations | -1.8% | European Union & USA | 2025 - 2034 |
| Regulatory Hurdles & Spectrum Allocation | -1.2% | Global | 2025 - 2028 |
Connected Aircraft Market Opportunities Analysis
The next decade presents lucrative opportunities for players who can integrate Artificial Intelligence (AI) and Machine Learning (ML) with connected aircraft data streams. By processing the vast amounts of information generated by connected sensors, service providers can offer advanced analytics for fuel management and proactive component replacement, opening new revenue streams in the aftermarket services sector. Additionally, the rise of Urban Air Mobility (UAM) and eVTOL (electric Vertical Take-off and Landing) aircraft represents a nascent but high-potential segment that will require 100% connectivity for safe autonomous operations and air traffic management. The expansion of 5G Air-to-Ground networks in densely populated regions also offers a lower-cost alternative to satellite connectivity for short-haul domestic flights.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI-Driven Fleet Analytics | +3.2% | North America & Europe | 2027 - 2034 |
| Expansion into Urban Air Mobility (UAM) | +2.5% | China & USA | 2028 - 2034 |
| Development of 5G Air-to-Ground (ATG) Networks | +1.9% | Asia-Pacific | 2026 - 2032 |
Connected Aircraft Market Challenges Impact Analysis
A primary challenge within the connected aircraft ecosystem is the rapid obsolescence of hardware. Satellite technology and data standards evolve at a pace that often outstrips the 20-year lifecycle of a typical commercial aircraft, leading to situations where installed systems become underpowered or incompatible with newer constellations. Additionally, the physical challenge of maintaining signal stability during high-speed travel through different atmospheric conditions and handovers between satellite beams can lead to "dead zones," frustrating users. Furthermore, the supply chain for specialized aerospace-grade semiconductors and antenna components remains vulnerable to geopolitical tensions, which can delay installation schedules and increase project costs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Latency and Bandwidth Limitations | -1.5% | Transoceanic Routes | 2025 - 2030 |
| Interoperability Between Legacy and New Hardware | -1.3% | Global Fleets | 2025 - 2029 |
| Supply Chain Volatility for Aerospace Components | -1.0% | Global | 2025 - 2027 |
Connected Aircraft Market - Updated Report Scope
This comprehensive market report provides a granular analysis of the global connected aircraft ecosystem, encompassing hardware, software, and service components across commercial, business, and military aviation sectors. The scope includes an in-depth evaluation of connectivity technologies such as Satellite (Ka-band, Ku-band, L-band) and Air-to-Ground (ATG) systems. Furthermore, the report examines the value chain from OEMs and component manufacturers to service providers and end-users, offering strategic insights into market penetration, competitive positioning, and the regulatory landscape across major geographic regions. The analysis is supported by quantitative data and qualitative assessments to provide a holistic view of the market’s evolution through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.85 Billion |
| Market Forecast in 2034 | USD 21.42 Billion |
| Growth Rate | 13.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Honeywell International Inc., Viasat Inc., Thales Group, Panasonic Avionics Corporation, Collins Aerospace (RTX), Gogo Business Aviation, Inmarsat Global Limited (Viasat), SITA, Intelsat, EchoStar Corporation (Hughes), Anuvu, Starlink (SpaceX), Safran SA, Cobham Aerospace Communications, Astronics Corporation, Teledyne Controls, Burrana Inc., Global Eagle Entertainment. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the connected aircraft market reveals a sophisticated ecosystem where diverse technologies meet specific operational needs. The commercial sector remains the primary engine of growth, particularly narrow-body aircraft which are being retrofitted at an unprecedented rate to cater to domestic travelers. Connectivity solutions are increasingly differentiated by frequency bands, with Ka-band gaining significant traction for its high-speed capabilities, while Ku-band remains preferred for its extensive global coverage. Operational applications are expanding beyond basic telemetry into complex AI-driven optimizations that integrate the aircraft as an "Edge Node" in the broader enterprise cloud, fundamentally changing how airlines manage their assets.
- By Type:
- Commercial Aircraft: Narrow-body, Wide-body, Regional Jets.
- Military Aircraft: Fighter Jets, Transport, Surveillance, UAVs.
- Business Jets: Ultra-Long Range, Large-Cabin, Mid-size.
- By Connectivity Technology:
- Satellite Communications (SATCOM): Ka-band, Ku-band, L-band.
- Air-to-Ground (ATG) Systems: 4G/LTE, 5G.
- By Application:
- Passenger Experience: Streaming, Browsing, E-commerce, Gaming.
- Flight Operations: Real-time Weather, Electronic Flight Bag (EFB), Fuel Optimization.
- Maintenance: Health Monitoring (HUMS), Predictive Analytics.
- By Offering:
- Hardware: Satcom Terminals, WAPs, Cabin Servers, Radomes.
- Software: Connectivity Management Platforms, Cybersecurity Suites.
- Services: Subscription Services, Managed Network Services.
Regional Highlights
- North America: The largest market share holder, North America benefits from a high concentration of major technology providers and a competitive airline landscape that prioritizes passenger amenities. The U.S. Department of Defense's modernization programs further bolster the military connected aircraft segment.
- Europe: Europe is a key hub for innovation, particularly in green aviation and regulatory standards. The presence of Airbus and major carriers like Lufthansa and Air France-KLM ensures steady demand for line-fit and retrofit connectivity solutions.
- Asia-Pacific: Identified as the fastest-growing region, APAC is seeing massive investments in aviation infrastructure in countries like India, China, and Vietnam. The rapid entry of LCCs (Low-Cost Carriers) into the connected space is a significant growth catalyst.
- Middle East: Home to "Mega-Carriers" such as Emirates and Qatar Airways, this region focuses on premium connectivity experiences for long-haul wide-body flights, driving high revenue per aircraft.
- Latin America & Africa: These regions are in the early adoption phase, with growth primarily driven by the modernization of regional fleets and the gradual rollout of satellite coverage in previously underserved areas.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Connected Aircraft Market.- Honeywell International Inc.
- Viasat Inc.
- Thales Group
- Panasonic Avionics Corporation
- Collins Aerospace (RTX)
- Gogo Business Aviation
- Inmarsat Global Limited
- SITA
- Intelsat
- EchoStar Corporation (Hughes)
- Anuvu
- Starlink (SpaceX)
- Safran SA
- Cobham Aerospace Communications
- Astronics Corporation
- Teledyne Controls
- Burrana Inc.
- Global Eagle Entertainment
- Gilat Satellite Networks
- Bae Systems
Frequently Asked Questions
What is the current size of the global Connected Aircraft market?
The global Connected Aircraft market is estimated at USD 6.85 Billion in 2025 and is projected to reach USD 21.42 Billion by 2034, growing at a CAGR of 13.4% during the forecast period.
Which technology is currently dominating the connectivity segment?
Satellite communication (SATCOM) dominates the market, specifically Ka-band and Ku-band systems, due to their ability to provide high-speed internet and global coverage, including transoceanic routes.
Who are the leading players in the connected aircraft industry?
Key leaders include Honeywell International, Viasat, Thales Group, Panasonic Avionics, and Collins Aerospace. Newer entrants like Starlink (SpaceX) are also rapidly gaining market share with LEO satellite solutions.
What are the primary drivers for the growth of this market?
Growth is primarily driven by rising passenger expectations for high-speed Wi-Fi, airline focus on operational efficiencies through real-time data, and the deployment of Low Earth Orbit (LEO) satellite constellations.
Which region is expected to grow at the fastest rate through 2034?
The Asia-Pacific region is expected to exhibit the fastest growth rate due to the expansion of commercial aviation fleets in China and India and increasing investments in digital cabin technologies.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
