Compostable Paper Tray Market
Compostable Paper Tray Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711722 | Published On : November 13, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Compostable Paper Tray Market Size
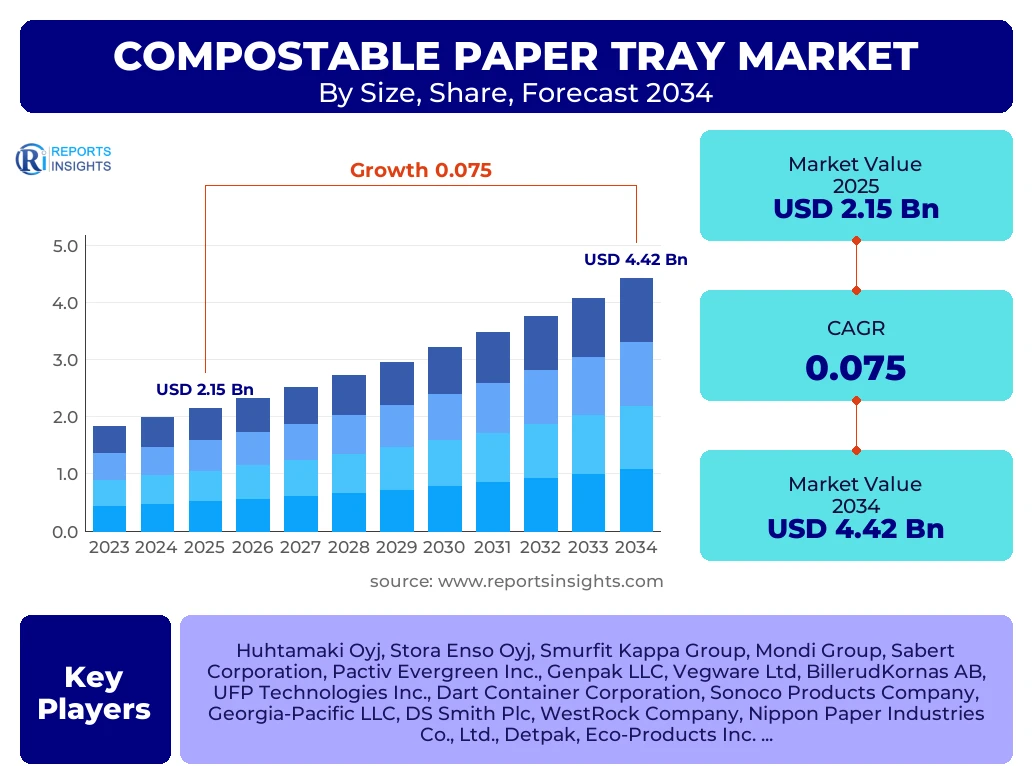
According to Reports Insights Consulting Pvt Ltd, The Compostable Paper Tray Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.5% between 2025 and 2034. The market is estimated at USD 2.31 Billion in 2026 and is projected to reach USD 4.42 Billion by the end of the forecast period in 2034.
The global valuation of the compostable paper tray sector reflects a fundamental shift in the packaging paradigm, driven by the urgent need to mitigate plastic pollution and transition toward a circular economy. Enterprise-level adoption of fiber-based solutions has accelerated as multinational food service brands and retail chains seek to align their ESG (Environmental, Social, and Governance) goals with consumer expectations. The technological evolution in molded fiber manufacturing, particularly the development of high-barrier coatings that do not compromise compostability, has expanded the utility of these trays from dry goods to high-moisture and high-fat food applications.
Market expansion is further bolstered by rigorous legislative frameworks, particularly in the European Union and North America, where single-use plastic bans have become more stringent. The 2025-2034 forecast period is expected to witness significant capital investment in "Wet Press" and "Dry Press" thermoforming technologies, which allow for the production of smoother, more durable, and aesthetically pleasing compostable trays that rival traditional plastic alternatives in performance. As manufacturing efficiencies improve, the price gap between conventional polymers and compostable paper-based materials is narrowing, facilitating broader adoption across emerging economies in the Asia-Pacific region.
Key Compostable Paper Tray Market Trends & Insights
The global market is currently navigating a period of intense innovation, characterized by the integration of PFAS-free (per- and polyfluoroalkyl substances) moisture and grease barriers. As health concerns regarding "forever chemicals" rise, market leaders are pivoting toward seaweed-based or aqueous coatings to ensure 100% home-compostability. Furthermore, the rise of e-commerce grocery and food delivery services has necessitated the development of robust, leak-proof compostable trays that can withstand the rigors of logistics without losing structural integrity. Competitive benchmarking reveals that companies focusing on sugarcane bagasse and bamboo fiber are gaining significant traction due to the rapid renewability of these raw materials compared to traditional wood pulp.
- Largest Region: North America remains the largest market by revenue, supported by a highly developed retail sector and early adoption of sustainable packaging by major fast-food franchises.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, with a projected CAGR exceeding 8.8% due to rapid urbanization, increasing disposable income, and new plastic-reduction mandates in China and India.
- Leading Segment by Material: Sugarcane Bagasse currently holds the largest market share owing to its excellent thermal properties and cost-effectiveness in high-volume production.
- Leading Segment by End-Use: The Food Service sector, particularly Quick Service Restaurants (QSRs), dominates the market share as they transition away from expanded polystyrene (EPS) trays.
- Technological Shift: There is a marked transition toward "Transfer Molded" and "Thermoformed Fiber" technologies to produce high-precision, smooth-surface trays suitable for premium retail packaging.
Key Takeaways Compostable Paper Tray Market Size & Forecast
The strategic outlook for the compostable paper tray market is defined by a move toward vertical integration, where packaging manufacturers secure direct supply chains for agricultural residues like wheat straw and bagasse. This ensures price stability and a lower carbon footprint for the final product. Analysts highlight that the 2026-2034 window will be characterized by "hyper-localization" of production facilities to reduce transportation emissions and costs. Moreover, the integration of smart packaging features, such as QR codes for compostability instructions and brand storytelling, is becoming a standard value-add for premium food brands.
- Regulatory Influence: The EU’s Packaging and Packaging Waste Regulation (PPWR) is a primary catalyst, forcing a total phase-out of non-recyclable or non-compostable food service packaging by the early 2030s.
- Cost Convergence: Scale of production is expected to bring the cost of compostable paper trays within a 10-15% margin of conventional plastic trays by 2029, significantly lowering the barrier to entry for SMEs.
- Material Innovation: Bamboo-based fiber trays are emerging as a high-growth sub-segment due to their superior tensile strength and premium aesthetic appeal in the organic food market.
- Market Concentration: While the market remains fragmented, strategic M&A (Mergers and Acquisitions) activity is increasing as larger packaging conglomerates acquire niche compostable technology startups.
- Retail Dominance: The "Fresh Produce" retail segment in Europe and North America is the most significant driver for deep-form compostable trays, replacing traditional PVC and PET punnets.
Compostable Paper Tray Market Drivers Analysis
The primary drivers of the compostable paper tray market include a combination of consumer sentiment, legislative mandates, and the inherent sustainability of the feedstock. As global awareness regarding microplastic contamination increases, consumers are actively choosing brands that utilize plastic-free packaging. This consumer pull is complemented by the push of government regulations, such as the ban on single-use plastics in various jurisdictions, which leaves businesses with no choice but to adopt compostable or highly recyclable alternatives. Additionally, the versatility of molded fiber, which can be engineered for microwave and oven safety, has opened new revenue streams in the frozen and ready-to-eat meal categories.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Ban on Single-Use Plastics | +2.4% | European Union, Canada, China | 2025 - 2034 |
| E-commerce and Food Delivery Expansion | +1.8% | Global / Asia-Pacific | 2025 - 2030 |
| Corporate ESG Commitments | +1.5% | North America / Western Europe | 2025 - 2034 |
| Advancements in PFAS-free Coatings | +1.2% | United States, Germany | 2026 - 2032 |
Compostable Paper Tray Market Restraints Analysis
Despite the positive growth trajectory, several restraints challenge the widespread adoption of compostable paper trays. The most significant is the lack of standardized industrial composting infrastructure in many regions, which leads to compostable items being sent to landfills where they may not degrade optimally. Additionally, the technical limitations of paper-based materials in high-moisture environments—without the use of synthetic liners—remains a hurdle. Fluctuations in the price of raw materials like wood pulp and agricultural waste can also lead to price volatility, making long-term contracting difficult for smaller retailers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inadequate Composting Infrastructure | -1.2% | United States, Latin America, SE Asia | 2025 - 2034 |
| Higher Production Costs vs. Plastic | -0.9% | Global / Emerging Markets | 2025 - 2028 |
| Raw Material Price Volatility | -0.5% | Global | 2025 - 2030 |
Compostable Paper Tray Market Opportunities Analysis
Significant opportunities exist in the development of "Home Compostable" certified trays, which allow consumers to dispose of packaging in domestic compost bins, bypassing the need for industrial facilities. The expansion into healthcare and medical packaging is another burgeoning opportunity, where compostable trays can be used for single-use surgical instruments or medication delivery, reducing the clinical waste footprint. Furthermore, the integration of bio-based barriers derived from starch or cellulose provides a technological edge for companies looking to capture the high-end gourmet and organic food sectors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Home-Compostable Barriers | +2.1% | United Kingdom, France, Germany | 2026 - 2034 |
| Expansion into Medical/Surgical Trays | +1.3% | United States, Japan | 2027 - 2034 |
| Use of Alternative Fibers (Hemp, Seaweed) | +0.8% | Europe, Coastal Asia | 2028 - 2034 |
Compostable Paper Tray Market Challenges Impact Analysis
The primary challenge remains the "Greenwashing" perception, where consumers are confused by varying labels such as biodegradable, compostable, and oxo-degradable. Harmonizing international standards for compostability is crucial to maintaining consumer trust. Additionally, the energy-intensive nature of the "Wet Press" manufacturing process presents a challenge in meeting carbon neutrality targets. Manufacturers must invest in renewable energy sources for their production facilities to ensure the product's lifecycle remains truly sustainable from cradle to grave.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Standardization of Labeling Laws | -0.7% | Global | 2025 - 2029 |
| Energy Intensity of Production | -0.4% | China, India, United States | 2025 - 2034 |
| Performance Gap in High-Heat Apps | -0.3% | Global | 2025 - 2027 |
Compostable Paper Tray Market - Updated Report Scope
The scope of this market analysis encompasses the entire value chain of the compostable paper tray industry, from raw material sourcing (agricultural residues, recycled paper, virgin pulp) to manufacturing technologies and diverse end-use applications. This report provides a detailed examination of the competitive landscape, highlighting the strategic maneuvers of top-tier players and the innovative disruptions caused by emerging startups. The study covers geographical nuances across six major regions, providing granular data on consumption patterns, regulatory environments, and technological adoption rates to offer a 360-degree view of the market's future trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.15 Billion |
| Market Forecast in 2034 | USD 4.42 Billion |
| Growth Rate | 7.5% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Huhtamaki Oyj, Stora Enso Oyj, Smurfit Kappa Group, Mondi Group, Sabert Corporation, Pactiv Evergreen Inc., Genpak LLC, Vegware Ltd, BillerudKornas AB, UFP Technologies Inc., Dart Container Corporation, Sonoco Products Company, Georgia-Pacific LLC, DS Smith Plc, WestRock Company, Nippon Paper Industries Co., Ltd., Detpak, Eco-Products Inc., Pac Moore Products, Be Green Packaging. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the compostable paper tray market reveals a diverse array of specialized products tailored to specific food safety and logistics requirements. The material segment is currently led by sugarcane bagasse, which is favored for its environmental profile and functional resilience. However, wood pulp remains a significant player in high-strength industrial and medical applications. In terms of application, the fresh produce segment is witnessing the highest rate of conversion from plastic punnets to molded fiber trays, driven by supermarkets' initiatives to eliminate plastic from the vegetable and fruit aisles. The transition to aqueous coatings is also creating a sub-segment of trays that are easier to recycle within existing paper streams if composting is unavailable.
- By Material:
- Sugarcane Bagasse (Leading segment due to rapid renewability)
- Bamboo Fiber (Premium segment with high growth)
- Wood Pulp (Virgin and Recycled)
- Other Agricultural Residues (Wheat straw, Hemp)
- By Technology:
- Transfer Molded (Standard food service trays)
- Thermoformed Fiber (High-definition, smooth finish trays)
- Vacuum Formed
- By End-Use Industry:
- Food Service (Fast food, catering, institutional)
- Retail & Supermarkets (Fresh meat, produce, bakery)
- Ready-to-eat Meals (Microwavable and ovenable trays)
- Healthcare & Pharmaceuticals
Regional Highlights
- North America: Holds the highest revenue share, driven by a mature food service industry and the rapid expansion of municipal composting programs in states like California and New York.
- Europe: The most regulated market with the highest per-capita consumption of compostable packaging, propelled by the EU's Circular Economy Action Plan and national bans in France and Germany.
- Asia-Pacific: The fastest-growing region, where massive manufacturing hubs in China and Vietnam are pivoting from plastic export to molded fiber production to meet global and domestic demand.
- Latin America: Emerging market with high potential in the fresh fruit export sector (e.g., Chile, Brazil), where compostable trays provide a competitive edge in European export markets.
- Middle East & Africa: Steady growth observed in the UAE and Saudi Arabia, particularly in the premium hospitality and tourism sectors seeking sustainable brand images.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Compostable Paper Tray Market.- Huhtamaki Oyj
- Stora Enso Oyj
- Smurfit Kappa Group
- Mondi Group
- Sabert Corporation
- Pactiv Evergreen Inc.
- Genpak LLC
- Vegware Ltd
- BillerudKornas AB
- UFP Technologies Inc.
- Dart Container Corporation
- Sonoco Products Company
- Georgia-Pacific LLC
- DS Smith Plc
- WestRock Company
- Nippon Paper Industries Co., Ltd.
- Detpak
- Eco-Products Inc.
- Be Green Packaging
- Footprint
Frequently Asked Questions
What are compostable paper trays made of?
Compostable paper trays are primarily manufactured from natural fibers such as sugarcane bagasse, bamboo, wood pulp, or wheat straw. These materials are processed into a pulp and molded into shapes using heat and pressure. Most modern trays use bio-based aqueous coatings to provide moisture resistance without using traditional plastics.
Are compostable paper trays microwave and oven safe?
Yes, many high-quality compostable paper trays, specifically those made from molded fiber, are designed to be microwave-safe. Specialized ovenable versions can withstand temperatures up to 400°F (200°C) for a limited time, making them suitable for ready-to-eat meal applications.
How long does it take for a paper tray to decompose?
In an industrial composting facility, these trays typically break down within 30 to 90 days. For home-compostable certified trays, the process may take 180 days or longer depending on the moisture and temperature of the compost pile.
What is the difference between "biodegradable" and "compostable" trays?
Biodegradable is a generic term meaning a material will eventually break down, but it doesn't specify the timeframe or the residue left behind. "Compostable" is a regulated term (e.g., ASTM D6400 or EN 13432) ensuring the material breaks down into nutrient-rich soil without leaving toxic residues within a specific timeframe.
Why is the Asia-Pacific region growing so fast in this market?
The APAC region is seeing a massive shift due to the combination of large-scale manufacturing capabilities, abundant agricultural waste for feedstock, and new government policies in China and India aimed at reducing single-use plastic waste in the food delivery sector.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
