Colorless Polyimide Films Market
Colorless Polyimide Films Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711750 | Published On : November 15, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Colorless Polyimide Films Market Size
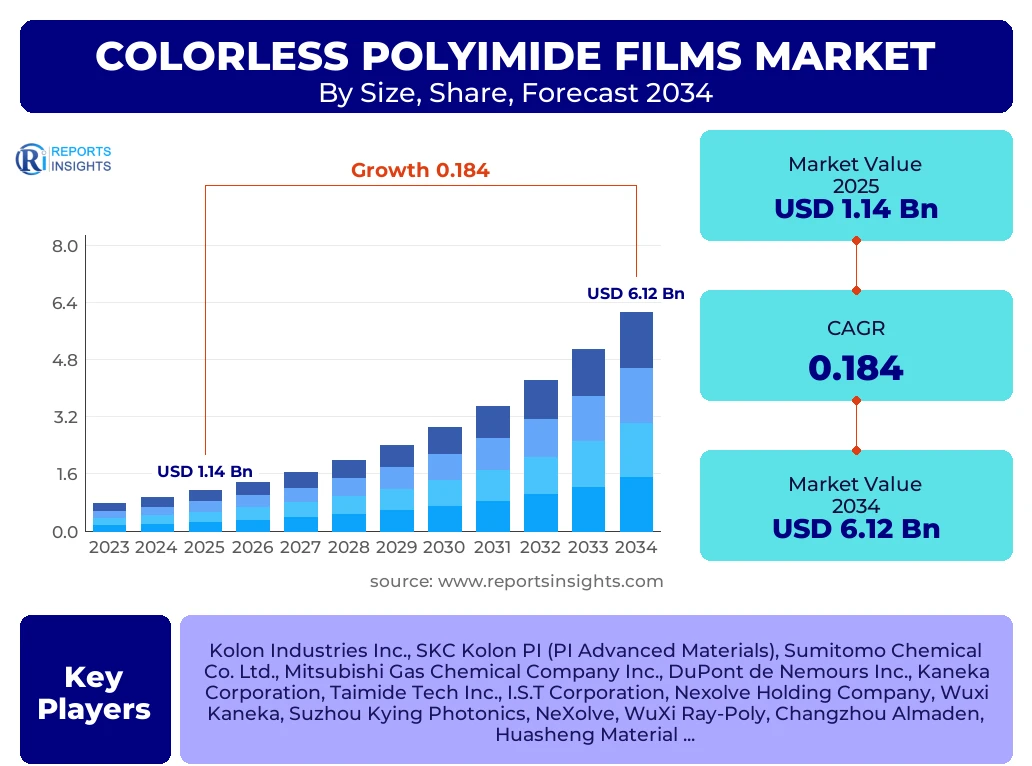
According to Reports Insights Consulting Pvt Ltd, The Colorless Polyimide Films Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.4% between 2025 and 2034. The market is estimated at USD 1.35 Billion in 2026 and is projected to reach USD 6.12 Billion by the end of the forecast period in 2034.
Key Colorless Polyimide Films Market Trends & Insights
The global Colorless Polyimide (CPI) films market is undergoing a significant transformation driven by the rapid evolution of flexible electronics and the global push toward high-performance optoelectronic materials. Traditionally, polyimide films have been known for their exceptional thermal and mechanical stability but were limited by their inherent amber or yellowish tint, which rendered them unsuitable for display applications. The development of colorless variants has bridged this gap, allowing manufacturers to leverage the durability of polyimides in applications requiring high optical clarity. The market is currently witnessing a surge in demand from the smartphone industry, particularly for foldable and rollable devices where CPI films serve as a robust alternative to ultra-thin glass. Additionally, advancements in monomer synthesis and polymerization techniques are enabling the production of films with lower yellow indices and higher glass transition temperatures, further expanding their utility in harsh environments such as space exploration and next-generation solar energy harvesting.
- Largest Region: Asia-Pacific remains the dominant force in the market, accounting for over 55% of the total market share due to the concentration of major display manufacturers and consumer electronics giants in South Korea, China, and Japan.
- Fastest Growing Region: Asia-Pacific is also expected to maintain the highest growth rate, fueled by massive investments in OLED and AMOLED production facilities and a robust supply chain for electronic components.
- Largest Segment by Application: Flexible Displays represent the largest segment, driven by the commercialization of foldable smartphones and the increasing adoption of flexible OLED panels in automotive dashboards and wearable technology.
- Leading Material Trend: There is a growing shift toward hybrid CPI films that incorporate inorganic nanoparticles to enhance scratch resistance and surface hardness without compromising optical transparency.
Key Takeaways Colorless Polyimide Films Market Size & Forecast
The market trajectory for Colorless Polyimide films is steeply upward, reflecting the broader transition from rigid to flexible substrates across multiple high-tech industries. Market analysis indicates that while the initial adoption was slow due to high production costs and technical hurdles in achieving perfect transparency, the current decade is seeing these barriers fall. Stakeholders are focusing on vertical integration to secure the supply of specialized fluorinated monomers, which are critical precursors for CPI production. The forecast period between 2025 and 2034 suggests a phase of "mass-market maturity" where CPI films will not only be found in premium flagship devices but also in mid-range electronics and large-scale industrial applications. The integration of 5G technology is also acting as a catalyst, as CPI films offer low dielectric constants, making them ideal for high-frequency communication components.
- Market Growth Catalyst: The transition from Ultra-Thin Glass (UTG) to CPI in specific foldable niches due to the latter's superior impact resistance and lower weight.
- Dominant Country: South Korea leads the market in terms of technological innovation and production capacity, spearheaded by industry leaders like Kolon Industries and SKC.
- Sector Convergence: The convergence of the automotive and electronics sectors is creating a new demand stream for transparent, heat-resistant films used in smart windows and curved head-up displays (HUDs).
- Forecast Reliability: Market valuations are supported by confirmed capacity expansions from key players and multi-year supply agreements with major smartphone OEMs.
Colorless Polyimide Films Market Drivers Analysis
The primary driver for the Colorless Polyimide films market is the relentless pursuit of flexibility in consumer electronics. As consumers demand larger screens in more portable formats, the industry has turned to foldable designs. CPI films provide the necessary combination of optical transparency, thermal stability (withstanding high-temperature manufacturing processes), and mechanical flexibility (surviving hundreds of thousands of fold cycles). Furthermore, the expansion of the 5G infrastructure requires materials with low dielectric loss and high thermal resistance, where CPI films outperform traditional plastics. The shift toward renewable energy also plays a role, as CPI films are increasingly used as substrates for flexible thin-film solar cells, which require lightweight and durable materials for integration into building-integrated photovoltaics (BIPV).
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Foldable Display Production | +7.2% | South Korea, China, USA | 2025 - 2034 |
| Adoption in 5G Antenna & FPCBs | +4.5% | Global, China, Japan | 2025 - 2030 |
| Demand for Flexible Solar Cells | +3.8% | Europe, North America | 2027 - 2034 |
| Automotive HUD and Smart Window Integration | +2.9% | Germany, Japan, USA | 2026 - 2034 |
Colorless Polyimide Films Market Restraints Analysis
Despite the high growth potential, the Colorless Polyimide films market faces several significant restraints. The most prominent is the high cost of raw materials. The synthesis of colorless polyimides requires specialized monomers, often fluorinated, which are expensive to produce and have limited supply chains. Additionally, the manufacturing process for CPI films is technically demanding; maintaining high optical clarity (low yellow index) while ensuring high thermal stability requires precise control over the polymerization environment. Competition from Ultra-Thin Glass (UTG) also poses a threat, as UTG offers better scratch resistance and a more "glass-like" feel, which many premium smartphone users prefer. These factors can limit the adoption of CPI films to specific segments where impact resistance and extreme flexibility are more critical than surface hardness.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production Costs & Raw Material Scarcity | -3.5% | Global | Ongoing |
| Competition from Ultra-Thin Glass (UTG) | -2.8% | Asia-Pacific, North America | 2025 - 2030 |
| Technical Challenges in Achieving Zero Yellow Index | -1.5% | Global Manufacturing Hubs | 2025 - 2028 |
Colorless Polyimide Films Market Opportunities Analysis
The next frontier for Colorless Polyimide films lies in the aerospace and defense sectors, where there is a constant need for materials that can withstand extreme temperature fluctuations and UV radiation without losing transparency. CPI films are being tested for use in flexible sensors and solar arrays for satellites and space stations. Another significant opportunity exists in the healthcare sector, particularly in the development of wearable medical devices and biosensors that require biocompatible, flexible, and transparent substrates. Furthermore, as the world moves toward 6G technology in the future, the demand for even more sophisticated low-loss dielectric materials will open new doors for modified CPI films with tailored electronic properties.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Space Exploration and Satellite Components | +4.2% | USA, Russia, India, China | 2028 - 2034 |
| Next-Gen 6G Communication Materials | +3.1% | South Korea, Japan, Finland | 2030 - 2034 |
| Wearable Healthcare & Biosensors | +2.7% | Germany, USA, Japan | 2026 - 2034 |
Colorless Polyimide Films Market Challenges Impact Analysis
One of the critical challenges in the CPI market is balancing conflicting physical properties. Generally, increasing the transparency and lowering the yellow index of a polyimide film can lead to a decrease in its thermal stability or mechanical strength. Achieving a "perfect" balance that meets the stringent requirements of semiconductor manufacturing processes (which often exceed 300 degrees Celsius) remains a significant R&D challenge. Environmental regulations regarding the use of fluorinated compounds also present a long-term challenge, as manufacturers must find ways to produce these films using more sustainable or "green" chemistry without compromising performance. Market fragmentation and the presence of low-cost alternatives for less demanding applications also pressure the profit margins of premium CPI producers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Maintaining Thermal Stability at High Transparency | -2.2% | Global | Ongoing |
| Regulatory Hurdles for Fluorinated Monomers | -1.8% | European Union, USA | 2027 - 2034 |
| Scaling Production for Large-Area Displays | -1.2% | China, South Korea | 2025 - 2029 |
Colorless Polyimide Films Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global Colorless Polyimide (CPI) films market, covering technological advancements, competitive landscapes, and regional growth patterns. The scope includes a detailed breakdown of the value chain, from raw material suppliers to end-use industries, ensuring a holistic view of the market dynamics. By analyzing current trends and future projections, this report serves as a strategic guide for stakeholders looking to navigate the complexities of high-performance polymer markets.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.14 Billion |
| Market Forecast in 2034 | USD 6.12 Billion |
| Growth Rate | 18.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Kolon Industries Inc., SKC Kolon PI (PI Advanced Materials), Sumitomo Chemical Co. Ltd., Mitsubishi Gas Chemical Company Inc., DuPont de Nemours Inc., Kaneka Corporation, Taimide Tech Inc., I.S.T Corporation, Nexolve Holding Company, Wuxi Kaneka, Suzhou Kying Photonics, NeXolve, WuXi Ray-Poly, Changzhou Almaden, Huasheng Material, Industrial Summit Technology, Shinmax Technology, Thin Film Technology, Saint-Gobain, Toray Industries. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Colorless Polyimide films market is segmented primarily by application and end-use industry, reflecting its versatile nature. The application segment is dominated by flexible displays, as the smartphone industry aggressively pursues foldable technology. However, the Flexible Printed Circuit Board (FPCB) segment is growing rapidly due to the miniaturization of electronic devices and the need for heat-resistant substrates that can handle high-speed data transmission. By end-use, the electronics sector holds the lion's share, but the automotive sector is emerging as a high-growth area with the rise of electric vehicles (EVs) and autonomous driving systems that utilize curved displays and advanced sensor arrays. Thickness-wise, the market is seeing a push toward films below 25 micrometers to accommodate the extreme thinness required for foldable screen stacks.
- By Application:
- Flexible Displays (Smartphone, Tablet, Laptop, Wearable)
- Solar Cells (Thin-film PV, Space-based Solar)
- Flexible Printed Circuit Boards (FPCBs)
- Lighting (Flexible OLED Lighting)
- Touch Panels & Sensors
- By End-Use Industry:
- Consumer Electronics
- Aerospace & Defense
- Automotive (Interior Displays, HUDs)
- Energy (Solar PV)
- Medical & Healthcare
- By Thickness:
- Below 25 Micrometers
- 25-50 Micrometers
- Above 50 Micrometers
Regional Highlights
- Asia-Pacific (APAC): This region is the absolute leader in the market. South Korea is the primary hub for CPI technology, driven by the presence of Samsung and LG, who have pioneered foldable display technology. China is rapidly catching up, with significant government backing for domestic display manufacturing and a growing ecosystem of CPI film producers like Changzhou Almaden. Japan remains a critical supplier of the high-purity monomers and chemical precursors needed for film production.
- North America: The market here is driven by the aerospace and defense sectors. NASA and private space companies are exploring CPI films for solar sails and satellite insulation. Additionally, the presence of major tech companies like Apple and Google, who are heavily invested in R&D for next-generation devices, ensures a steady demand for high-performance transparent films.
- Europe: Europe's market is characterized by strong demand from the automotive industry. German automakers are increasingly integrating curved, transparent displays into high-end vehicle cockpits. Furthermore, the region's focus on renewable energy provides opportunities for CPI use in flexible solar panels and energy-efficient building materials.
- Middle East & Africa (MEA) and Latin America: These regions represent emerging markets where growth is linked to the adoption of consumer electronics and the expansion of telecommunications infrastructure, although they currently hold a smaller share of the global market.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Colorless Polyimide Films Market. These companies are categorized based on their production capacity, R&D investment, and strategic partnerships with OEMs.
- Kolon Industries Inc.
- PI Advanced Materials (Formerly SKC Kolon PI)
- Sumitomo Chemical Co. Ltd.
- Mitsubishi Gas Chemical Company Inc.
- DuPont de Nemours, Inc.
- Kaneka Corporation
- Taimide Tech Inc.
- I.S.T Corporation
- Nexolve Holding Company
- Wuxi Kaneka
- Suzhou Kying Photonics
- Changzhou Almaden
- WuXi Ray-Poly
- Shinmax Technology
- Huasheng Material
- Toray Industries
- Saint-Gobain
- Thin Film Technology
- Industrial Summit Technology
- MGC Filsheet Co. Ltd.
Frequently Asked Questions
Analyze common user questions about the Colorless Polyimide Films market and generate a concise list of summarized FAQs reflecting key topics and concerns.
What is the main difference between Colorless Polyimide (CPI) and regular Polyimide (PI)?
The primary difference lies in optical clarity. Traditional PI films are yellow or amber due to charge transfer complexes in their molecular structure. CPI films are engineered using specific monomers (often fluorinated) that prevent this color formation, resulting in a film that is as transparent as glass while retaining the high thermal stability and flexibility of polyimide.
Why are Colorless Polyimide films preferred over Ultra-Thin Glass (UTG) in some foldable phones?
While UTG offers a better feel and scratch resistance, CPI films are significantly more impact-resistant and durable against drops. CPI is also lighter and can achieve tighter fold radii without the risk of shattering, making it highly suitable for early-generation foldable devices and specific industrial applications where ruggedness is prioritized.
Which industries are the biggest consumers of CPI films?
The electronics industry, specifically the display and flexible circuit board sectors, is the largest consumer. However, the aerospace industry uses CPI for its thermal insulation and UV resistance, and the automotive industry is increasingly adopting it for curved interior displays and smart windows.
What are the primary factors driving the high CAGR of the Colorless Polyimide market?
The high CAGR is primarily driven by the commercial explosion of foldable smartphones, the rapid rollout of 5G technology requiring low-dielectric materials, and the increasing demand for lightweight, flexible solar panels in the renewable energy sector.
Is the cost of Colorless Polyimide films expected to decrease in the future?
Yes, as manufacturing processes mature and economies of scale are achieved, the cost of CPI is expected to decline. However, because it requires expensive specialized monomers and complex synthesis, it will likely remain a premium material compared to standard PET or PEN films for the foreseeable future.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
