Coating Additives Market
Coating Additives Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711517 | Published On : November 04, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Coating Additives Market Size
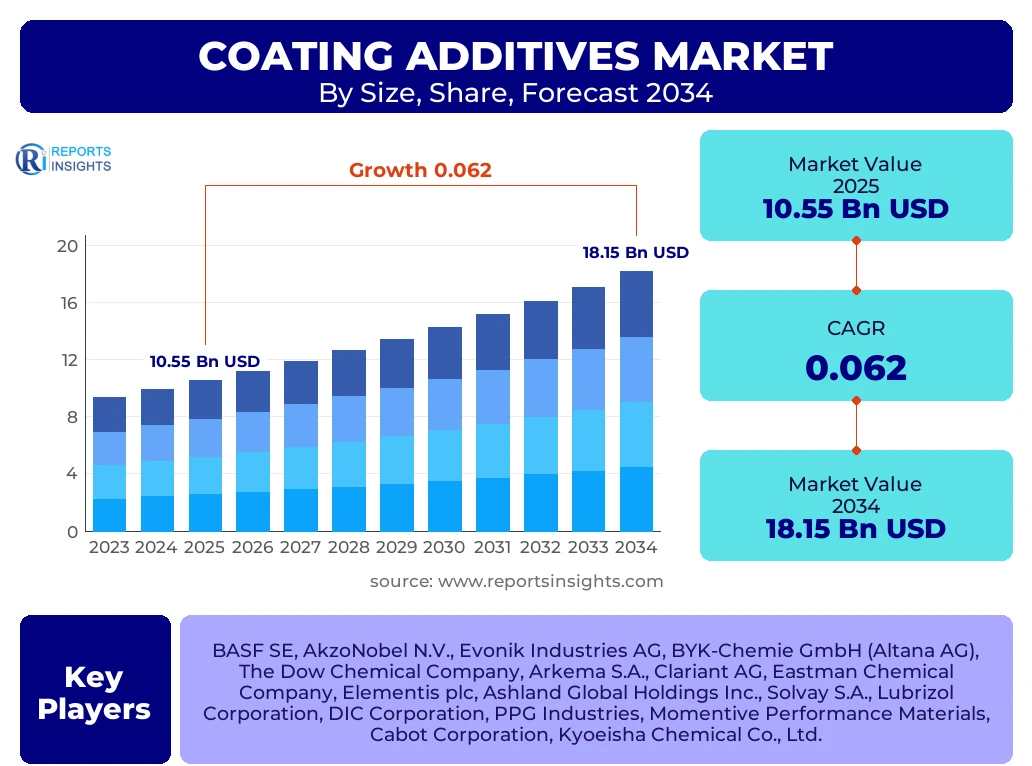
According to Reports Insights Consulting Pvt Ltd, The Coating Additives Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at 11.20 Billion USD in 2026 and is projected to reach 18.15 Billion USD by the end of the forecast period in 2034.
The global demand for coating additives is fundamentally anchored in the rising requirements for high-performance protective layers across diverse industrial landscapes. These chemical components, though constituting a small percentage of the total coating formulation, are indispensable for optimizing the application process and the final durability of the surface. The transition from solvent-borne to water-borne systems, particularly in developed economies, has catalyzed the development of advanced rheology modifiers and wetting agents capable of maintaining performance without high VOC emissions. As infrastructure projects accelerate in emerging economies, the market is witnessing a sustained upward trajectory in volume and value.
Technological sophistication in the manufacturing of additives is leading to the creation of multi-functional products that serve multiple purposes simultaneously, such as combining anti-foaming properties with improved pigment dispersion. This evolution reduces the complexity of formulations for end-users, primarily in the automotive, aerospace, and construction sectors. The forecast period reflects a maturing market in Western regions characterized by specialty high-margin products, while the Asia-Pacific region remains the primary volume driver due to massive industrialization and urbanization cycles.
Key Coating Additives Market Trends & Insights
The global coating additives landscape is currently shaped by a profound shift toward sustainability, technological convergence, and specialized functional requirements. Users and stakeholders are increasingly prioritizing environmental compliance, leading to the rapid adoption of bio-based additives and low-VOC formulations. Competitive benchmarking indicates that leading players are pivoting from commodity chemicals to high-value specialty additives that provide unique surface properties like self-healing, anti-microbial resistance, and super-hydrophobicity. Regional insights suggest that while North America and Europe lead in regulatory-driven innovation, the Asia-Pacific region remains the epicenter of production and consumption, driven by the expanding middle class and infrastructure modernization.
- Largest Region: Asia-Pacific currently holds the dominant share of the global market, accounting for over 45% of total value, fueled by the industrial powerhouses of China and India.
- Fastest Growing Region: South East Asia and parts of Latin America are expected to exhibit the highest CAGR due to burgeoning construction activities and the relocation of manufacturing hubs.
- Largest Segment by Share: Rheology modifiers remain the largest functional segment as they are critical across nearly all coating types to ensure proper viscosity and application thickness.
- Sustainability Shift: There is a massive transition toward green chemistry, with manufacturers replacing traditional alkylphenol ethoxylates (APEs) with eco-friendly alternatives.
- Automotive Innovation: The rise of Electric Vehicles (EVs) is demanding specialized thermal management coatings and lightweight material protection, creating a niche but highly profitable additive segment.
Key Takeaways Coating Additives Market Size & Forecast
The strategic outlook for the coating additives market is defined by a consistent expansion of the industrial base and a tightening of environmental standards globally. Analysis of market data suggests that the integration of nanotechnology and advanced polymer science is providing manufacturers with the tools to meet the rigorous demands of the 21st-century architectural and automotive sectors. The forecast indicates that while raw material price volatility remains a concern, the shift toward premium, high-efficiency additives will sustain value growth across all major geographies.
- Global Market Maturity: The market is moving toward a more consolidated structure where R&D capabilities determine market leadership rather than just production capacity.
- Leading Countries: China, the United States, and Germany remain the most critical markets, collectively representing more than 60% of global demand and innovation output.
- Formulation Trends: Water-borne additives are outpacing solvent-borne counterparts, growing at a rate nearly 1.5 times faster as global VOC regulations become more stringent.
- End-Use Dominance: The architectural sector continues to be the primary consumer of coating additives, though the industrial and marine sectors show higher growth in specialized anti-corrosive additives.
- Investment Focus: Major players are investing heavily in digitalizing their chemical formulation processes to shorten the time-to-market for new additive solutions.
Coating Additives Market Drivers Analysis
The primary catalysts for the coating additives market include the resurgence of global construction activity and the increasing demand for high-durability surfaces in the transportation sector. As modern architecture pushes the boundaries of design, there is a subsequent need for coatings that can withstand extreme weather conditions, pollution, and mechanical stress. Furthermore, the rapid growth of the electronics industry requires specialized coatings with anti-static and conductive properties, further pushing the demand for sophisticated additive chemistries.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Infrastructure and Urbanization | +2.1% | China, India, Brazil | 2025 - 2034 |
| Regulatory Compliance (Low VOC) | +1.5% | European Union, North America | 2025 - 2030 |
| Automotive Sector Recovery & EV Growth | +1.2% | Germany, Japan, South Korea | 2026 - 2032 |
| Technological Advancements in Nanomaterials | +0.9% | United States, South Korea | 2027 - 2034 |
Coating Additives Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from the volatility of raw material prices, primarily driven by fluctuations in the petrochemical sector. Additionally, the complexity and cost associated with complying with diverse and evolving international regulatory frameworks, such as REACH in Europe, pose substantial barriers for smaller manufacturers. These factors often lead to increased production costs which cannot always be passed down to the end-consumer in price-sensitive markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Fluctuations | -1.1% | Global | Ongoing |
| Stringent Environmental Regulations | -0.8% | EU (REACH), North America | 2025 - 2029 |
| High Cost of Specialty Additives | -0.5% | Developing Nations | 2025 - 2034 |
Coating Additives Market Opportunities Analysis
The emerging frontier for coating additives lies in the development of "smart" and functional coatings. Opportunities abound in the creation of bio-based and renewable additives that align with the circular economy goals of global conglomerates. Furthermore, the expansion of the aerospace and defense sectors in emerging markets provides a fertile ground for specialized additives that offer extreme heat resistance and radar-absorbing properties. The integration of AI in additive discovery also presents a significant opportunity to reduce R&D cycles.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bio-based and Eco-friendly Additives | +1.8% | Global, especially EU | 2026 - 2034 |
| Advanced Smart Coatings | +1.3% | USA, Germany, Israel | 2028 - 2034 |
| Marine & Offshore Protective Additives | +0.7% | South East Asia, Middle East | 2025 - 2034 |
Coating Additives Market Challenges Impact Analysis
One of the most pressing challenges is the supply chain fragility highlighted by recent geopolitical tensions, which affects the availability of critical chemical precursors. Moreover, the industry must overcome the technical hurdle of maintaining performance in water-borne systems compared to traditional solvent-borne formulations, especially in high-stress industrial applications. Ensuring global standardization of product quality and safety also remains a complex logistical challenge for multinational corporations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Disruptions | -0.9% | Global | 2025 - 2027 |
| Technical Limitations of Green Alternatives | -0.6% | Industrial Sector | 2025 - 2030 |
| Geopolitical Instability | -0.4% | Eastern Europe, Middle East | Ongoing |
Coating Additives Market - Updated Report Scope
The scope of this comprehensive market analysis encompasses the entire value chain of the coating additives industry, from raw material procurement to end-use application. The report evaluates various chemical classes including acrylics, urethanes, fluoropolymers, and silicones across diverse functions such as rheology modification, wetting and dispersion, and anti-foaming. It provides a detailed breakdown of market dynamics across key geographies, offering strategic insights into the competitive landscape and future technological shifts that will define the industry for the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | 10.55 Billion USD |
| Market Forecast in 2034 | 18.15 Billion USD |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, AkzoNobel N.V., Evonik Industries AG, BYK-Chemie GmbH (Altana AG), The Dow Chemical Company, Arkema S.A., Clariant AG, Eastman Chemical Company, Elementis plc, Ashland Global Holdings Inc., Solvay S.A., Lubrizol Corporation, DIC Corporation, PPG Industries, Momentive Performance Materials, Cabot Corporation, Kyoeisha Chemical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The coating additives market is intricately segmented to reflect the diverse chemical functionalities and application requirements across different industries. Segmentation is primarily based on chemical type, functional performance, and end-user requirements, allowing for a granular understanding of growth pockets. The shift toward specialized formulations is driving growth in the high-performance additives segment, while the push for environmental sustainability is redefining the market for water-borne and powder-based systems. Understanding these segments is crucial for stakeholders to align their product development and marketing strategies with the most lucrative opportunities.
- By Type:
- Acrylics: Widely used for their versatility and durability in architectural and automotive applications.
- Urethanes: Favored for high-performance industrial coatings requiring superior chemical and abrasion resistance.
- Fluoropolymers: Specialized for extreme environmental conditions and non-stick properties.
- Silicones: Essential for defoaming and surface slip characteristics.
- Metallic Additives: Used for aesthetic finishes and functional properties like electrical conductivity.
- By Function:
- Rheology Modifiers: The largest segment, controlling the flow and application thickness of coatings.
- Dispersing & Wetting Agents: Critical for ensuring uniform color distribution and surface adhesion.
- Defoamers: Necessary for eliminating air bubbles during the manufacturing and application process.
- Leveling Agents: Ensures a smooth, defect-free surface finish.
- UV Stabilizers: Protects surfaces from degradation caused by prolonged sunlight exposure.
- By Formulation:
- Water-borne: The fastest-growing segment due to environmental regulations and health safety.
- Solvent-borne: Still dominant in high-performance heavy industrial applications where water-borne systems may fail.
- Powder-based: Gaining traction in appliances and automotive parts due to zero VOC emissions.
- Radiation-Cured: Growing in the packaging and electronics sector for ultra-fast curing times.
- By End-Use:
- Architectural: The primary volume driver, encompassing residential and commercial building finishes.
- Automotive: Requires high-value additives for aesthetics, UV protection, and anti-corrosion.
- Industrial: Focuses on durability and protection for machinery and infrastructure.
- Marine: Demands specialized anti-fouling and salt-water resistant additives.
- Wood & Furniture: Emphasizes aesthetics and scratch resistance.
Regional Highlights
The regional distribution of the coating additives market reveals a landscape influenced by varying levels of industrial maturity and regulatory frameworks. The Asia-Pacific region stands as the dominant force, driven by the massive manufacturing output of China and the rapid urbanization of India. In North America and Europe, the market is characterized by a focus on high-value, sustainable specialty chemicals, where stringent environmental laws mandate the transition to low-VOC products. Emerging regions like Latin America and the Middle East are showing significant growth potential as they invest in infrastructure and diversify their industrial bases.
- Asia-Pacific: The largest market globally, holding nearly half of the market share. It is the manufacturing hub for construction and electronics, driving massive demand for bulk additives.
- North America: A leader in the development of advanced additive technologies, particularly in the aerospace and defense sectors. The U.S. remains the primary contributor in this region.
- Europe: Characterized by the strictest environmental regulations globally, leading the world in the adoption of bio-based and sustainable additives. Germany is the regional powerhouse.
- Latin America: Growing steadily, with Brazil and Mexico as the primary markets, driven by the automotive assembly industry and infrastructure projects.
- Middle East & Africa: Focused primarily on industrial and marine coatings, especially in the oil and gas sector where extreme corrosion protection is required.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Coating Additives Market.- BASF SE
- AkzoNobel N.V.
- Evonik Industries AG
- BYK-Chemie GmbH (Altana AG)
- The Dow Chemical Company
- Arkema S.A.
- Clariant AG
- Eastman Chemical Company
- Elementis plc
- Ashland Global Holdings Inc.
- Solvay S.A.
- Lubrizol Corporation
- DIC Corporation
- PPG Industries
- Momentive Performance Materials
- Cabot Corporation
- Kyoeisha Chemical Co., Ltd.
- Allnex
- Heubach GmbH
- Patcham FZC
Frequently Asked Questions
What are the primary functions of coating additives in industrial applications?
Coating additives serve critical functions including rheology modification (controlling flow and viscosity), wetting and dispersion (ensuring uniform pigment distribution), defoaming (removing air bubbles), and surface protection (providing UV resistance and anti-corrosive properties). They are essential for enhancing both the application process and the long-term durability of the coating.
How are environmental regulations impacting the coating additives market?
Environmental regulations, particularly those targeting Volatile Organic Compounds (VOCs), are forcing a shift from solvent-borne to water-borne and powder-based systems. This has led to increased R&D in green chemistry and bio-based additives to ensure performance remains high while meeting strict standards like REACH and EPA mandates.
Which end-use industry is expected to see the highest growth for coating additives?
While the architectural sector remains the largest by volume, the automotive sector, especially with the rise of Electric Vehicles (EVs), and the electronics sector are expected to see significant growth in the demand for specialized, high-performance additives for thermal management and functional surface properties.
What role does nanotechnology play in the future of coating additives?
Nanotechnology is a major driver of innovation, enabling the creation of additives that provide superior scratch resistance, self-healing capabilities, and anti-microbial properties without altering the transparency or texture of the coating. It allows for high-performance features at much lower concentration levels than traditional additives.
Why is the Asia-Pacific region dominant in the coating additives market?
The Asia-Pacific region dominates due to its massive industrial base, particularly in China and India, high levels of construction activity, and the presence of major manufacturing hubs for electronics and automotive parts. Increasing urbanization and a growing middle class further fuel the demand for high-quality architectural coatings.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
