Cloud Data Warehouse Market
Cloud Data Warehouse Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711233 | Published On : October 21, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Cloud Data Warehouse Market Size
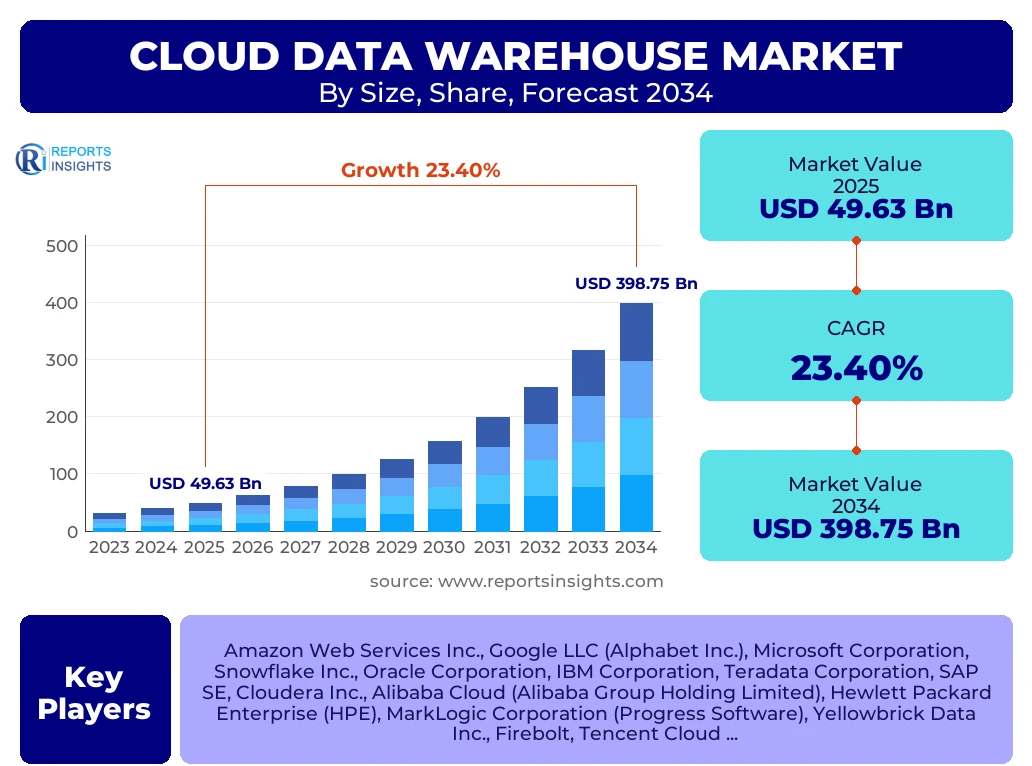
According to Reports Insights Consulting Pvt Ltd, The Cloud Data Warehouse Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 23.4% between 2025 and 2034. The market is estimated at USD 61.24 Billion in 2026 and is projected to reach USD 398.75 Billion by the end of the forecast period in 2034.
Key Cloud Data Warehouse Market Trends & Insights
The global cloud data warehouse market is undergoing a significant transformation driven by the convergence of artificial intelligence and high-performance computing. Enterprises are increasingly moving away from legacy on-premise systems to embrace serverless architectures that offer unparalleled scalability and cost-efficiency. Current market trends indicate a strong shift toward the "Data Lakehouse" model, which combines the structured management of data warehouses with the flexibility of data lakes. Furthermore, the integration of generative AI and machine learning directly into the warehousing layer is enabling businesses to run predictive analytics without moving large datasets, thereby reducing latency and egress costs. Competitive benchmarking reveals that major providers are focusing on multi-cloud and inter-cloud capabilities to prevent vendor lock-in and enhance disaster recovery protocols.
- North America remains the largest regional market due to early cloud adoption and the presence of major technology hyperscalers.
- The Asia-Pacific region is documented as the fastest-growing market, fueled by rapid digitalization in India, China, and Southeast Asia.
- Public Cloud deployment currently holds the largest market share as organizations prioritize OpEx-based models over capital-intensive infrastructure.
- The BFSI (Banking, Financial Services, and Insurance) segment is the leading vertical, utilizing cloud warehouses for real-time fraud detection and regulatory compliance reporting.
Key Takeaways Cloud Data Warehouse Market Size & Forecast
The long-term forecast for the cloud data warehouse market suggests a robust expansion as data democratization becomes a core business strategy. Market participants are focusing on high-concurrency workloads and the ability to handle both structured and semi-structured data types. Regional insights suggest that while established economies lead in value, emerging economies are skipping traditional infrastructure phases and moving directly to cloud-native environments. The drive toward real-time insights is necessitating the adoption of streaming data ingestion, which is projected to become a standard feature of modern cloud data warehousing solutions by 2028.
- Total market valuation is expected to surpass the USD 300 billion threshold before 2033, reflecting the critical nature of data storage and processing.
- The United States and China are the primary contributors to global market revenue, representing nearly 55% of the total market share combined.
- Security and compliance enhancements, particularly around GDPR and CCPA, are becoming significant product differentiators for market leaders.
- The Small and Medium Enterprise (SME) segment is expected to witness the highest CAGR as pay-as-you-go pricing models lower the barrier to entry for advanced analytics.
Cloud Data Warehouse Market Drivers Analysis
The primary driver for the cloud data warehouse market is the exponential growth in data volume generated by IoT devices, social media, and digital transactions. As organizations strive to become data-driven, the need for agile, scalable, and cost-effective storage solutions has become paramount. Traditional data warehouses often struggle with the elasticity required to handle peak loads, whereas cloud-native solutions allow for the independent scaling of compute and storage resources, ensuring optimal performance during high-demand periods.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Exponential Increase in Big Data Analytics Demand | +6.2% | Global (Strong in US & Germany) | 2025 - 2034 |
| Adoption of Serverless Computing Architectures | +5.5% | North America and Western Europe | 2025 - 2030 |
| Shift from CapEx to OpEx Business Models | +4.8% | Asia-Pacific and Latin America | 2025 - 2034 |
| Integration of AI and Machine Learning Workflows | +6.9% | Global | 2026 - 2034 |
Cloud Data Warehouse Market Restraints Analysis
Despite the rapid growth, the market faces significant hurdles related to data privacy and security. Organizations in highly regulated sectors such as healthcare and government often express concerns regarding the sovereignty of data stored in public clouds. Furthermore, the complexity of migrating massive volumes of legacy data to the cloud can result in significant downtime and high initial transition costs, which may deter some traditional enterprises from immediate adoption.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Sovereignty and Regulatory Compliance Issues | -3.2% | European Union (GDPR focus) | 2025 - 2034 |
| High Egress Costs and Hidden Cloud Fees | -2.5% | Global | 2025 - 2028 |
| Shortage of Skilled Cloud Architects and Data Engineers | -2.1% | Emerging Markets | 2025 - 2030 |
Cloud Data Warehouse Market Opportunities Analysis
The emergence of Edge Computing presents a significant opportunity for cloud data warehouse providers to extend their reach. By processing data closer to the source and then syncing with a centralized cloud warehouse, businesses can achieve near-instantaneous insights. Additionally, the rise of the "Data Marketplace" concept allows companies to monetize their anonymized datasets, creating new revenue streams and increasing the utility of the warehousing infrastructure.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Vertical-Specific Data Solutions | +4.5% | North America and Japan | 2026 - 2034 |
| Hybrid and Multi-Cloud Ecosystem Development | +5.2% | Global | 2025 - 2034 |
| Democratization via Low-Code/No-Code Analytics | +3.8% | Global | 2027 - 2034 |
Cloud Data Warehouse Market Challenges Impact Analysis
One of the most pressing challenges is the issue of vendor lock-in, where the cost and technical difficulty of moving data between different cloud providers become prohibitive. As enterprises adopt multi-cloud strategies, the lack of standardization in SQL dialects and data formats across different proprietary warehouses remains a technical bottleneck. Additionally, maintaining performance consistency across geographically dispersed regions while ensuring low latency is a constant engineering challenge for service providers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interoperability and Data Portability Hurdles | -2.8% | Global | 2025 - 2034 |
| Complexity in Managing Multi-Cloud Environments | -2.4% | Enterprise-level Organizations | 2025 - 2034 |
Cloud Data Warehouse Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global cloud data warehouse industry, providing granular insights into deployment models, organization sizes, and end-user verticals. It evaluates the competitive landscape by profiling key market participants and assessing their strategic initiatives, such as mergers, acquisitions, and technological innovations. The report also investigates the impact of macro-economic factors, including inflation and digital transformation trends, on the market's long-term trajectory from 2025 to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 49.63 Billion |
| Market Forecast in 2034 | USD 398.75 Billion |
| Growth Rate | 23.4% CAGR |
| Number of Pages | 278 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Amazon Web Services Inc., Google LLC (Alphabet Inc.), Microsoft Corporation, Snowflake Inc., Oracle Corporation, IBM Corporation, Teradata Corporation, SAP SE, Cloudera Inc., Alibaba Cloud (Alibaba Group Holding Limited), Hewlett Packard Enterprise (HPE), MarkLogic Corporation (Progress Software), Yellowbrick Data Inc., Firebolt, Tencent Cloud, Panoply (Sisu Data), Databricks Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The cloud data warehouse market is segmented primarily by deployment model and organization size to reflect the diverse needs of the global business landscape. Large enterprises currently dominate the market as they possess the resources to manage complex data migrations and require high-performance analytics for global operations. However, the SME segment is expected to see significant growth due to the introduction of flexible pricing tiers and managed services that eliminate the need for in-house database administrators. On the basis of verticals, the IT and Telecom sector is a major consumer, utilizing data warehousing for network optimization and churn prediction.
- By Deployment:
- Public Cloud: The leading segment due to low entry costs and high scalability.
- Private Cloud: Preferred by organizations with stringent security requirements.
- Hybrid Cloud: Gaining traction as companies balance legacy assets with cloud innovation.
- By Organization Size:
- Large Enterprises: Account for the majority of revenue share.
- Small and Medium-Sized Enterprises (SMEs): Fastest growing segment due to cloud accessibility.
- By Vertical:
- BFSI: Utilizing warehouses for risk modeling and customer 360 views.
- Healthcare: Growing use in genomic research and patient outcome analytics.
- Retail and E-commerce: Critical for inventory management and personalized marketing.
- Manufacturing: Implementation for supply chain visibility and predictive maintenance.
Regional Highlights
- North America: This region holds the largest market share, approximately 38% in 2025. The high concentration of tech-heavy organizations and the rapid adoption of AI-driven analytics drive this dominance. The United States is the primary revenue contributor, focused on advanced cybersecurity and multi-cloud strategies.
- Asia-Pacific: Identified as the fastest-growing region with a projected CAGR of over 26%. This is driven by large-scale digital transformation projects in China and India, alongside the expansion of regional cloud providers like Alibaba and Tencent.
- Europe: Maintains a steady growth rate, characterized by a heavy emphasis on data privacy and sovereignty. The United Kingdom, Germany, and France are the key markets, with increasing investments in sovereign cloud solutions to comply with local regulations.
- Middle East and Africa: Experiencing growth through government-led smart city initiatives and the modernization of the oil and gas sector.
- Latin America: Developing market with significant potential in Brazil and Mexico as financial institutions modernize their data infrastructure.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cloud Data Warehouse Market.- Amazon Web Services Inc.
- Google LLC (Alphabet Inc.)
- Microsoft Corporation
- Snowflake Inc.
- Oracle Corporation
- IBM Corporation
- Teradata Corporation
- SAP SE
- Cloudera Inc.
- Alibaba Cloud (Alibaba Group Holding Limited)
- Hewlett Packard Enterprise (HPE)
- MarkLogic Corporation
- Yellowbrick Data Inc.
- Firebolt
- Tencent Cloud
- Panoply
- Databricks Inc.
- SingleStore
- Exasol
- Actian Corporation
Frequently Asked Questions
What is a Cloud Data Warehouse and how does it differ from traditional databases?
A Cloud Data Warehouse is a centralized repository stored in a cloud environment, optimized for analytical processing rather than transactional processing. Unlike traditional databases, cloud warehouses allow for the elastic scaling of compute and storage, utilize columnar storage for faster queries, and offer a pay-as-you-go pricing model that eliminates large upfront hardware costs.
What are the key benefits of migrating to a Cloud Data Warehouse?
Key benefits include enhanced scalability, lower total cost of ownership (TCO), improved performance for complex analytical queries, and seamless integration with modern BI tools and AI/ML frameworks. It also enables better data accessibility for remote teams and reduces the burden on internal IT departments for maintenance and patching.
Which industry vertical is adopting Cloud Data Warehousing most rapidly?
The BFSI (Banking, Financial Services, and Insurance) and Retail sectors are the most rapid adopters. BFSI uses it for real-time risk assessment and fraud detection, while Retail leverages it for hyper-personalized customer experiences and complex supply chain optimization.
How does the "Data Lakehouse" trend impact the Cloud Data Warehouse market?
The Data Lakehouse architecture merges the features of a data lake (low-cost storage for all data types) with a data warehouse (high-performance structure and ACID compliance). This trend is simplifying data architectures by allowing organizations to run all their analytical and AI workloads on a single platform, reducing data redundancy.
What are the primary security concerns for Cloud Data Warehousing?
Primary concerns include data breaches, unauthorized access, and lack of visibility over data residency. Modern providers address these through end-to-end encryption, multi-factor authentication (MFA), role-based access control (RBAC), and compliance certifications like SOC2, HIPAA, and GDPR to ensure data integrity and privacy.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
