Chemical Vapor Deposition Market
Chemical Vapor Deposition Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711129 | Published On : October 11, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Chemical Vapor Deposition Market Size
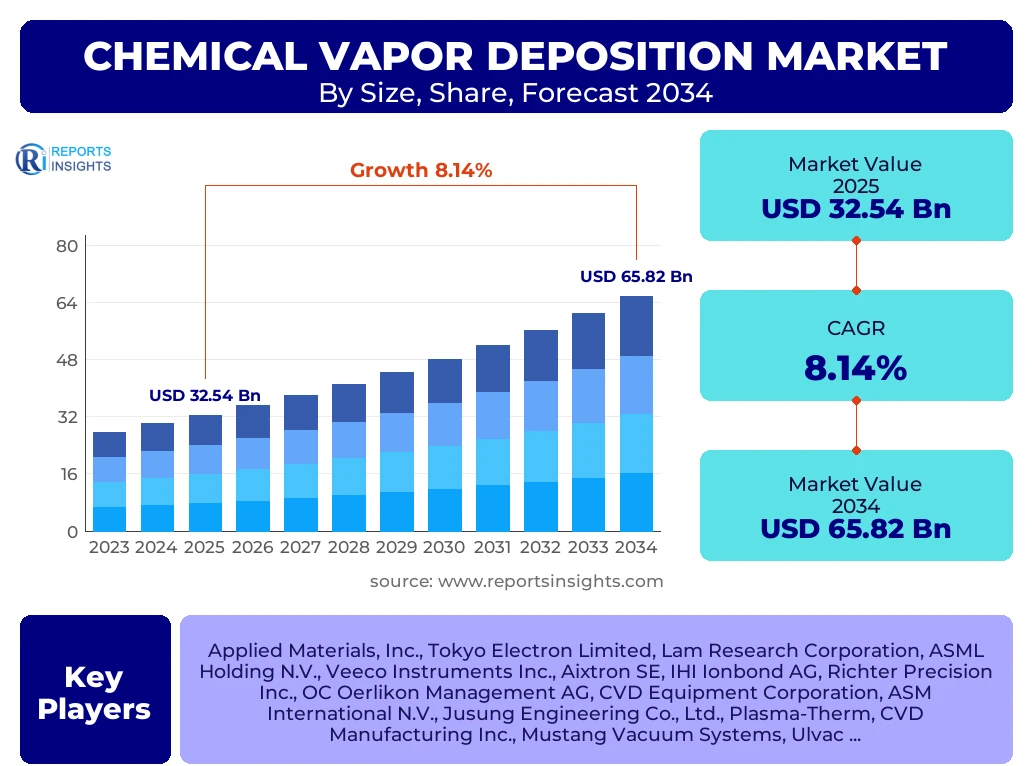
According to Reports Insights Consulting Pvt Ltd, The Chemical Vapor Deposition Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.14% between 2025 and 2034. The market is estimated at USD 35.19 Billion in 2026 and is projected to reach USD 65.82 Billion by the end of the forecast period in 2034.
Key Chemical Vapor Deposition Market Trends & Insights
The Chemical Vapor Deposition (CVD) market is undergoing a significant transformation driven by the escalating demand for advanced semiconductor components and high-performance industrial coatings. As the electronics industry moves toward sub-7nm process nodes, the precision offered by CVD techniques, particularly Atomic Layer Deposition (ALD) and Plasma Enhanced Chemical Vapor Deposition (PECVD), has become indispensable. Furthermore, the integration of Artificial Intelligence (AI) and the expansion of 5G infrastructure are catalyzing the need for sophisticated thin-film layers that provide superior electrical insulation and thermal management. Market participants are increasingly focusing on sustainable precursor chemistries to align with global environmental regulations, while simultaneously optimizing vacuum system efficiencies to reduce operational overhead.
Current insights indicate a robust shift toward Metal-Organic Chemical Vapor Deposition (MOCVD) for the production of high-brightness LEDs and power electronics based on Gallium Nitride (GaN) and Silicon Carbide (SiC). The transition toward electric vehicles (EVs) has further intensified the demand for CVD-coated components that can withstand extreme voltages and temperatures. Geographically, the Asia-Pacific region maintains its lead due to the concentration of semiconductor foundries and consumer electronics manufacturing hubs, while North America and Europe are witnessing a resurgence in domestic manufacturing through government-backed initiatives like the CHIPS Act. Competitive benchmarking reveals that leading players are prioritizing strategic mergers and R&D collaborations to secure intellectual property in next-generation nanotechnology applications.
- Largest Region: Asia-Pacific (APAC) remains the dominant regional market, accounting for over 45% of the total market share, driven by major semiconductor manufacturing in Taiwan, South Korea, and China.
- Fastest Growing Region: North America is projected to be the fastest-growing region during the forecast period, spurred by significant investments in domestic semiconductor fabrication and aerospace technology.
- Largest Segment by Technology: Plasma Enhanced Chemical Vapor Deposition (PECVD) holds the largest market share due to its versatility and lower processing temperatures compared to traditional thermal CVD.
- Leading Application Segment: Semiconductor and Microelectronics continue to be the primary revenue contributor, fueled by the global surge in demand for high-performance computing and mobile devices.
- Emerging Trend: The adoption of CVD for graphene and carbon nanotube synthesis is opening new frontiers in flexible electronics and advanced energy storage systems.
Key Takeaways Chemical Vapor Deposition Market Size & Forecast
The global Chemical Vapor Deposition market is characterized by high capital intensity and a rapid rate of technological obsolescence. Strategic analysis suggests that the market will continue to expand as industries beyond electronics—such as medical devices and renewable energy—adopt CVD for protective and functional coatings. The transition from 2D to 3D NAND structures in memory devices is a critical volume driver for the market, requiring multiple deposition cycles and higher material consumption. Investors and stakeholders should note that while the equipment segment generates significant upfront revenue, the materials and precursors segment provides a more consistent, long-term recurring revenue stream as the installed base of CVD systems grows globally.
- Primary Growth Catalyst: The ongoing miniaturization of electronic components requires atomic-level precision, which is only achievable through advanced CVD and ALD processes.
- Leading Country Market: China is the single largest country market, benefiting from massive state-led investments in self-sufficient semiconductor supply chains.
- Strategic Shift: There is a noticeable shift toward Low-Pressure Chemical Vapor Deposition (LPCVD) in the fabrication of high-quality polycrystalline silicon and dielectric layers.
- Sustainability Focus: Development of eco-friendly precursor gases and more efficient waste gas abatement systems is becoming a competitive differentiator for equipment manufacturers.
- Forecast Reliability: The market forecast remains resilient despite short-term economic fluctuations, underpinned by the structural transition toward a more digitized and electrified global economy.
Chemical Vapor Deposition Market Drivers Analysis
The Chemical Vapor Deposition market is primarily propelled by the unrelenting demand for miniaturized electronic devices and the expansion of the global semiconductor industry. As consumer electronics, automotive telematics, and industrial IoT devices require more powerful yet smaller chips, the necessity for high-precision thin-film deposition increases. Additionally, the rapid growth of the solar energy sector, specifically the production of high-efficiency thin-film solar cells, provides a secondary yet powerful growth engine for CVD technology.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Semiconductor Miniaturization (Sub-7nm Nodes) | +3.2% | Taiwan, South Korea, USA | 2025 - 2034 |
| Expansion of 5G and IoT Infrastructure | +1.8% | Global | 2025 - 2030 |
| EV Battery & Power Electronics Demand | +1.5% | China, Germany, Japan | 2026 - 2034 |
| Thin-Film Solar Cell Adoption | +1.2% | India, China, EU | 2025 - 2034 |
Chemical Vapor Deposition Market Restraints Analysis
Despite strong growth prospects, the market faces significant hurdles related to high initial capital investment and complex operational requirements. The cost of advanced CVD systems, particularly MOCVD and ALD reactors, can be prohibitive for smaller enterprises. Furthermore, stringent environmental regulations regarding the handling and disposal of toxic precursor gases and by-products pose a logistical and financial challenge for manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure (CAPEX) | -1.4% | Global | 2025 - 2034 |
| Strict Environmental & Safety Regulations | -0.9% | Europe, North America | 2025 - 2034 |
| Scarcity of Skilled Technical Personnel | -0.5% | Global | 2025 - 2030 |
Chemical Vapor Deposition Market Opportunities Analysis
The emergence of new materials such as graphene and transition metal dichalcogenides (TMDs) presents a massive opportunity for the CVD market. These materials are expected to revolutionize fields ranging from flexible electronics to supercapacitors. Additionally, the expansion of CVD applications into the biomedical field for biocompatible coatings on implants and surgical tools offers a high-margin growth path for specialized equipment providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Graphene & Carbon Nanotube Synthesis | +2.1% | UK, USA, South Korea | 2027 - 2034 |
| Biomedical & Medical Device Coatings | +1.1% | Germany, USA, Japan | 2026 - 2034 |
| Advanced Aerospace Components | +0.8% | USA, France | 2025 - 2034 |
Chemical Vapor Deposition Market Challenges Impact Analysis
The primary challenges involve the technical limitations of maintaining film uniformity over large substrates and the increasing complexity of multi-layered deposition. As wafer sizes increase and feature sizes decrease, ensuring consistency across the entire surface becomes exponentially difficult. Additionally, supply chain volatility for rare-earth precursors and high-purity chemicals can lead to production delays and cost fluctuations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Substrate Uniformity & Step Coverage | -0.7% | Japan, Taiwan | 2025 - 2034 |
| Supply Chain Volatility for Precursors | -0.6% | Global | 2025 - 2028 |
| Inter-process Contamination Risks | -0.4% | Global | 2025 - 2034 |
Chemical Vapor Deposition Market - Updated Report Scope
This report provides an exhaustive analysis of the global Chemical Vapor Deposition landscape, covering technological advancements, competitive dynamics, and regional market shifts. It encompasses a detailed breakdown of equipment types, material precursors, and end-use industries, offering strategic insights for stakeholders to navigate the complex market environment. The scope includes historical data from 2020 to 2024, a base year of 2025, and a comprehensive forecast period extending to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 32.54 Billion |
| Market Forecast in 2034 | USD 65.82 Billion |
| Growth Rate | 8.14% CAGR |
| Number of Pages | 268 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Applied Materials, Inc., Tokyo Electron Limited, Lam Research Corporation, ASML Holding N.V., Veeco Instruments Inc., Aixtron SE, IHI Ionbond AG, Richter Precision Inc., OC Oerlikon Management AG, CVD Equipment Corporation, ASM International N.V., Jusung Engineering Co., Ltd., Plasma-Therm, CVD Manufacturing Inc., Mustang Vacuum Systems, Ulvac, Inc., Oxford Instruments plc, Kurt J. Lesker Company |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Chemical Vapor Deposition market is segmented based on category, technology, and application to provide a granular view of growth opportunities. The technology segment is currently dominated by PECVD due to its ability to operate at lower temperatures, preserving the integrity of sensitive substrates. However, MOCVD is witnessing rapid growth in the optoelectronics sector. From an application perspective, the semiconductor industry remains the cornerstone of the market, though significant growth is observed in the energy sector for thin-film PV and battery components.
- By Category:
- CVD Equipment (Atmospheric, Low-pressure, Plasma-enhanced)
- CVD Materials (Gaseous precursors, Liquid precursors, Solid precursors)
- CVD Services (Coating services, Maintenance, and Training)
- By Technology:
- Plasma Enhanced Chemical Vapor Deposition (PECVD)
- Low-Pressure Chemical Vapor Deposition (LPCVD)
- Atmospheric Pressure Chemical Vapor Deposition (APCVD)
- Metal-Organic Chemical Vapor Deposition (MOCVD)
- Atomic Layer Deposition (ALD)
- Laser-Induced CVD
- Photo-Initiated CVD
- By Application:
- Semiconductors and Microelectronics (Logic, Memory, Sensors)
- Solar Cells (Photovoltaics)
- Cutting Tools and Wear-resistant Parts
- Medical Devices and Implants
- Optical Coatings (Lenses, Mirrors)
- Aerospace and Defense (Thermal barriers)
- Energy Storage (Li-ion batteries, Supercapacitors)
Regional Highlights
The regional landscape is dominated by the Asia-Pacific region, which accounts for the largest share of the market value. This is primarily attributed to the presence of world-leading semiconductor manufacturing hubs in Taiwan, South Korea, and China. These nations are investing heavily in domestic chip production to secure supply chains, directly benefiting CVD equipment manufacturers. China, in particular, is a significant growth engine as it seeks to reduce reliance on foreign technology.
- Asia-Pacific: Largest market share; home to the world's leading foundries (TSMC, Samsung, SK Hynix); fastest growing adoption of MOCVD for LED manufacturing.
- North America: Leading in R&D for advanced ALD and next-generation logic chips; strong presence of aerospace and defense industries requiring specialized CVD coatings.
- Europe: Hub for automotive electronics and high-precision medical devices; focus on sustainable and eco-friendly CVD precursors; strong research base in Germany and the UK for graphene.
- Latin America & MEA: Emerging markets with increasing investments in renewable energy projects and mining infrastructure, driving demand for wear-resistant industrial coatings.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Chemical Vapor Deposition Market. These companies are at the forefront of technological innovation, focusing on enhancing deposition uniformity, increasing throughput, and reducing the environmental footprint of CVD processes.
- Applied Materials, Inc.
- Tokyo Electron Limited
- Lam Research Corporation
- ASML Holding N.V.
- Veeco Instruments Inc.
- Aixtron SE
- IHI Ionbond AG
- Richter Precision Inc.
- OC Oerlikon Management AG
- CVD Equipment Corporation
- ASM International N.V.
- Jusung Engineering Co., Ltd.
- Plasma-Therm
- CVD Manufacturing Inc.
- Mustang Vacuum Systems
- Ulvac, Inc.
- Oxford Instruments plc
- Kurt J. Lesker Company
- Dentons
- Thin Film Equipment S.r.l.
Frequently Asked Questions
What is the projected market size of the Chemical Vapor Deposition market by 2034?
The global Chemical Vapor Deposition market is projected to reach approximately USD 65.82 Billion by 2034, growing at a CAGR of 8.14% from 2025.
Which technology segment holds the largest share in the CVD market?
Plasma Enhanced Chemical Vapor Deposition (PECVD) currently holds the largest share because it allows for lower processing temperatures and high-quality film deposition, making it ideal for semiconductor manufacturing.
Why is the Asia-Pacific region dominant in the Chemical Vapor Deposition market?
Asia-Pacific dominates due to its status as a global hub for semiconductor and electronics manufacturing, led by major industry players and government investments in Taiwan, South Korea, and China.
What are the primary applications of CVD outside of the electronics industry?
Beyond electronics, CVD is widely used for producing high-efficiency solar cells, wear-resistant coatings for cutting tools, biocompatible surfaces for medical implants, and thermal barrier coatings in the aerospace industry.
What are the key challenges facing the Chemical Vapor Deposition market?
Key challenges include high initial capital costs for equipment, the technical difficulty of achieving atomic-level uniformity on large substrates, and strict environmental regulations regarding precursor gas emissions.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
