Chemical Protective Clothing Market
Chemical Protective Clothing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711912 | Published On : November 21, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Chemical Protective Clothing Market Size
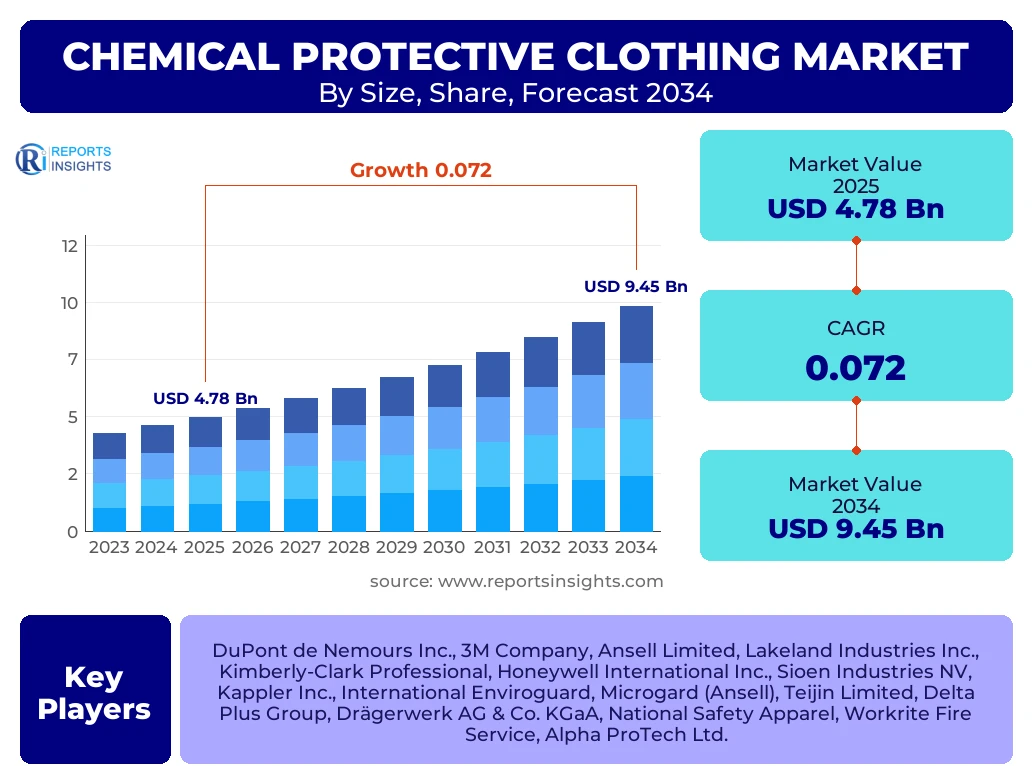
According to Reports Insights Consulting Pvt Ltd, The Chemical Protective Clothing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 5.12 Billion in 2026 and is projected to reach USD 9.45 Billion by the end of the forecast period in 2034.
Key Chemical Protective Clothing Market Trends & Insights
The global landscape for chemical protective clothing is undergoing a transformative shift driven by rigorous occupational health mandates and the integration of advanced material science. Current market trends indicate a move toward multi-hazard protection garments that offer not only chemical resistance but also flame retardancy and antistatic properties. Industrial stakeholders are increasingly prioritizing ergonomic designs that reduce worker fatigue without compromising the integrity of the barrier against hazardous substances. Furthermore, the rise of the pharmaceutical and biotechnology sectors, particularly in emerging economies, has catalyzed the demand for high-purity cleanroom apparel that prevents cross-contamination while protecting the wearer from volatile organic compounds and potent active pharmaceutical ingredients.
- Largest Region: North America remains the dominant regional market, underpinned by stringent OSHA and EPA regulations that mandate high-tier protective gear across chemical manufacturing and oil and gas sectors.
- Fastest Growing Region: Asia-Pacific is set to witness the highest CAGR, fueled by rapid industrialization in China, India, and Vietnam, alongside increasing safety awareness in the regional manufacturing base.
- Largest Segment by Type: The coveralls and suits segment holds the majority market share due to their comprehensive body protection capabilities required in high-risk environments.
- Leading Material Segment: Polyethylene-based materials continue to lead the market share owing to their cost-effectiveness and high resistance to a wide range of industrial chemicals.
Key Takeaways Chemical Protective Clothing Market Size & Forecast
Strategic analysis of the chemical protective clothing market reveals a robust trajectory supported by the continuous expansion of the global chemical processing industry. Forecasts suggest that the adoption of reusable chemical protective clothing is gaining momentum as enterprises seek to align their safety protocols with sustainability goals, reducing landfill waste generated by disposable alternatives. The integration of "Smart PPE" featuring embedded sensors to monitor heat stress and exposure levels is also identified as a critical growth frontier. Market leaders are focusing on the development of lightweight, breathable fabrics that maintain high permeation resistance, addressing the long-standing challenge of heat strain in industrial environments.
- Dominant Country: The United States leads global consumption, driven by a mature chemical industry and high replacement rates of protective gear.
- Growth Catalyst: Strengthening of EN ISO standards and ASTM international guidelines is compelling manufacturers to upgrade product specifications, boosting market value.
- Material Innovation: Increasing utilization of non-woven fabrics and specialty laminates is enhancing the durability-to-weight ratio of modern protective suits.
- End-Use Leadership: The healthcare and pharmaceutical segment is emerging as a critical volume driver, particularly for Type 4, 5, and 6 protective clothing.
Chemical Protective Clothing Market Drivers Analysis
The primary catalyst for the chemical protective clothing market is the escalating global emphasis on workplace safety and the reduction of occupational hazards. Governments worldwide are implementing stricter legal frameworks to minimize chemical-related injuries and long-term health complications, such as dermal toxicity and respiratory issues. This regulatory pressure forces industries to invest in high-quality Personal Protective Equipment (PPE) as part of their risk management strategies.
Additionally, the expansion of the oil and gas industry, particularly in downstream activities such as refining and petrochemical processing, creates a steady demand for specialized clothing. As exploration moves into more hostile environments and chemical processing becomes more complex, the requirement for garments that can withstand aggressive solvents and corrosive agents becomes paramount for operational continuity and worker safety.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Workplace Safety Regulations | +2.4% | European Union & North America | 2025–2034 |
| Expansion of Pharmaceutical Manufacturing | +1.8% | India, China, & Ireland | 2026–2030 |
| Growth in Petrochemical Infrastructure | +1.5% | GCC Countries & USA | 2025–2034 |
Chemical Protective Clothing Market Restraints Analysis
A significant restraint facing the market is the high cost associated with advanced chemical protective materials. Developing fabrics that offer high permeation resistance while remaining breathable requires substantial R&D investment, which often results in premium pricing. For small and medium-sized enterprises (SMEs) in developing regions, the initial capital expenditure for high-tier reusable suits can be a barrier to adoption.
Furthermore, the environmental impact of disposable chemical protective clothing is coming under increased scrutiny. Most disposable suits are made from non-biodegradable synthetic polymers, leading to significant waste management challenges. As global industries shift toward circular economy models, the reliance on single-use protective gear may face regulatory pushback or environmental taxes, potentially slowing market growth in certain segments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Procurement Costs for Premium Gear | -1.1% | Latin America & Southeast Asia | 2025–2029 |
| Environmental Concerns over Disposable Waste | -0.8% | Europe (Green Deal Impact) | 2027–2034 |
Chemical Protective Clothing Market Opportunities Analysis
The development of bio-based and recyclable materials presents a massive opportunity for manufacturers to differentiate their offerings. By creating chemical-resistant fabrics that can be safely recycled or are derived from sustainable sources, companies can capture the growing segment of environmentally conscious industrial buyers. This transition aligns with global ESG (Environmental, Social, and Governance) targets and can open new procurement channels in the public sector.
Another major opportunity lies in the integration of IoT and wearable technology. Incorporating sensors that can detect chemical breaches in real-time or monitor the physiological vital signs of the wearer (such as core body temperature) provides an added layer of safety. These "smart" garments can prevent heat-related illnesses and provide data-driven insights for safety officers to improve site-wide protection protocols.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of IoT-Integrated Smart PPE | +2.1% | Global Industrial Hubs | 2028–2034 |
| Eco-friendly & Recyclable Fabric Innovation | +1.6% | Germany, Japan, & Canada | 2026–2034 |
Chemical Protective Clothing Market Challenges Impact Analysis
The primary challenge in this sector is maintaining the balance between maximum protection and wearer comfort. Traditional chemical-resistant fabrics often lack breathability, leading to rapid heat accumulation and physiological stress for workers. This can result in reduced productivity or, in extreme cases, workers bypassing safety protocols to find relief, which introduces significant liability and safety risks.
Additionally, the global supply chain volatility for raw synthetic polymers can impact production timelines and pricing. Fluctuations in the cost of raw materials like polypropylene and specialized coatings can lead to thin profit margins for manufacturers and unpredictable pricing for end-users, complicating long-term procurement contracts in the industrial and healthcare sectors.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Heat Stress and Ergonomic Limitations | -0.9% | Middle East & Tropical Regions | 2025–2034 |
| Raw Material Price Volatility | -0.7% | Global Manufacturing Base | 2025–2028 |
Chemical Protective Clothing Market - Updated Report Scope
This comprehensive market report provides a detailed analysis of the chemical protective clothing industry from 2020 to 2034. It encompasses a granular evaluation of material performance, design innovations, and regulatory compliance across various high-risk industrial applications. The scope includes a thorough investigation of the competitive landscape, highlighting strategic maneuvers such as mergers, acquisitions, and product launches that are shaping the future of industrial safety.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.78 Billion |
| Market Forecast in 2034 | USD 9.45 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | DuPont de Nemours Inc., 3M Company, Ansell Limited, Lakeland Industries Inc., Kimberly-Clark Professional, Honeywell International Inc., Sioen Industries NV, Kappler Inc., International Enviroguard, Microgard (Ansell), Teijin Limited, Delta Plus Group, Drägerwerk AG & Co. KGaA, National Safety Apparel, Workrite Fire Service, Alpha ProTech Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The chemical protective clothing market is segmented based on product type, material, end-use industry, and protection level to provide a comprehensive view of the market dynamics. The coveralls and suits segment remains the cornerstone of the market, offering comprehensive dermal protection in high-risk zones. In terms of materials, polyethylene and polypropylene dominate the disposable market due to their excellent moisture barrier properties and chemical inertness. However, specialty materials like butyl rubber and Viton are gaining traction for high-end applications involving extremely aggressive or toxic substances where standard polymers fail.
- By Product Type: Coveralls, Gloves, Aprons, Footwear, Head Protection.
- By Material: PE, PP, PVC, Neoprene, Nitrile, Butyl, Fluoropolymers.
- By End-Use: Pharmaceuticals, Chemical Industry, Oil & Gas, Agriculture, Mining.
- By Protection Level: Level A, Level B, Level C, Level D (OSHA/EPA Standards).
Regional Highlights
- North America: The largest market share holder, driven by the presence of major chemical manufacturing hubs and the most stringent safety compliance standards (OSHA). The United States is the primary revenue generator in this region.
- Asia-Pacific: The fastest-growing region with a high concentration of manufacturing activities. China and India are experiencing massive growth in their chemical and pharmaceutical sectors, leading to a surge in PPE demand.
- Europe: A mature market focused on high-quality standards and sustainability. Germany and France are leading in the adoption of reusable and eco-friendly protective clothing under the REACH and Personal Protective Equipment (PPE) Regulation (EU) 2016/425.
- Middle East & Africa: Significant growth driven by the oil, gas, and petrochemical sectors in Saudi Arabia and the UAE, where specialized flame-resistant and chemical-resistant gear is a prerequisite.
- Latin America: Steady growth supported by the mining and agricultural sectors in Brazil and Chile, where protective gear is used for handling pesticides and hazardous minerals.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Chemical Protective Clothing Market.- DuPont de Nemours Inc.
- 3M Company
- Ansell Limited
- Lakeland Industries Inc.
- Kimberly-Clark Professional
- Honeywell International Inc.
- Sioen Industries NV
- Kappler Inc.
- International Enviroguard
- Microgard (Ansell)
- Teijin Limited
- Delta Plus Group
- Drägerwerk AG & Co. KGaA
- National Safety Apparel
- Workrite Fire Service
- Alpha ProTech Ltd.
- Uvex Group
- Trelleborg AB
- Lindström Group
Frequently Asked Questions
What is the current size of the global chemical protective clothing market?
The market is estimated to be valued at USD 5.12 Billion in 2026, with projections indicating a growth to USD 9.45 Billion by 2034, reflecting the increasing global focus on industrial safety.
Which industry is the largest consumer of chemical protective clothing?
The chemical processing industry remains the largest consumer, followed closely by the pharmaceutical and oil and gas sectors, due to the high risk of exposure to hazardous substances in these environments.
How do Level A and Level B protection differ in this market?
Level A provides the highest level of protection with a gas-tight, vapor-tight suit and self-contained breathing apparatus (SCBA), while Level B provides high-level respiratory protection but a lower level of skin protection (liquid-splash resistant rather than gas-tight).
What are the emerging trends in chemical protective clothing?
Key emerging trends include the integration of IoT for real-time monitoring, the development of sustainable/recyclable materials, and the use of lightweight laminates that improve worker mobility and comfort.
Which region offers the most significant growth opportunities?
The Asia-Pacific region offers the most significant growth opportunities due to rapid industrialization, increasing labor safety regulations, and the expansion of the pharmaceutical and manufacturing sectors in emerging economies.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
