Chemical Anchors Market
Chemical Anchors Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711333 | Published On : October 27, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Chemical Anchors Market Size
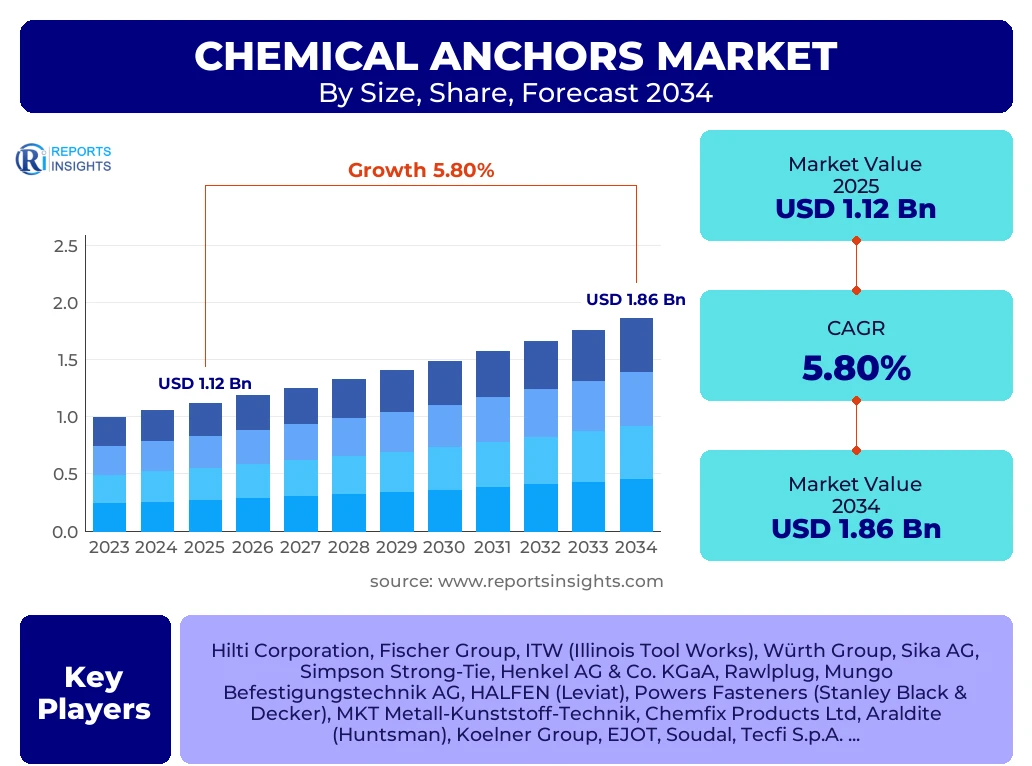
According to Reports Insights Consulting Pvt Ltd, The Chemical Anchors Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 1.18 Billion in 2026 and is projected to reach USD 1.86 Billion by the end of the forecast period in 2034.
Key Chemical Anchors Market Trends & Insights
The global chemical anchors market is undergoing a significant transformation driven by advancements in polymer science and an increasing emphasis on structural safety in seismic zones. Market trends indicate a decisive shift toward high-performance epoxy and vinyl ester resins that offer superior bond strength and longevity in harsh environments. Furthermore, the integration of digital technologies, such as QR-coded cartridges for installation tracking and automated dispensing systems, is enhancing onsite efficiency and reducing human error. Stakeholders are increasingly prioritizing sustainable formulations with low Volatile Organic Compound (VOC) emissions to align with green building certifications such as LEED and BREEAM.
- Asia Pacific is the largest and fastest-growing region, fueled by massive infrastructure projects in China, India, and Southeast Asia.
- The Epoxy Resin segment holds the largest market share due to its high load-bearing capacity and versatility in various substrate conditions.
- Infrastructure remains the dominant end-use segment, particularly in the construction of bridges, tunnels, and high-speed rail systems.
- Injection-type chemical anchors are gaining traction over capsule types due to their cost-effectiveness in large-scale applications and ease of use in deep-hole drilling.
Key Takeaways Chemical Anchors Market Size & Forecast
The chemical anchors market is characterized by robust growth in the residential and commercial sectors as renovation and retrofitting activities increase globally. Modern building codes are increasingly mandating the use of chemical anchoring systems over traditional mechanical anchors for heavy-duty applications, particularly in cracked concrete and masonry. The forecast period highlights a strong focus on research and development to produce resins that can be applied in extreme temperature ranges and underwater environments, expanding the application scope to offshore and maritime industries.
- China and India are identified as the leading countries in terms of production and consumption, driven by rapid urbanization and smart city initiatives.
- The transition from mechanical to chemical anchoring systems is a critical driver, as the latter distributes load more evenly and reduces stress on the base material.
- Post-installed rebar connections are becoming a primary growth sub-segment within the infrastructure vertical.
- Technological innovation in delivery systems, such as cordless electric dispensers, is significantly reducing installation time and physical strain on labor.
Chemical Anchors Market Drivers Analysis
The primary driver for the chemical anchors market is the global surge in infrastructure development and the aging of existing civil structures requiring rehabilitation. As governments invest in high-capacity transportation networks and energy infrastructure, the demand for reliable, high-strength fastening solutions has reached an all-time high. Additionally, the increasing frequency of seismic events has led to stricter building regulations, favoring chemical anchors for their ability to maintain structural integrity under dynamic loading conditions. The rise of modular and prefabricated construction also necessitates precise and durable anchoring solutions during assembly.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Infrastructure and Retrofitting Projects | +1.5% | Global (Strong in APAC and MEA) | 2025–2034 |
| Stringent Seismic and Fire Safety Regulations | +1.2% | Europe and North America | 2025–2030 |
| Advancements in Resin Chemistry (Low VOC) | +0.9% | Developed Economies | 2026–2032 |
Chemical Anchors Market Restraints Analysis
Despite the positive growth trajectory, the market faces restraints related to the technical complexity of installation and the higher initial cost compared to mechanical alternatives. Chemical anchors require specific environmental conditions, such as controlled temperature and humidity, for proper curing, which can delay projects in extreme climates. Furthermore, the shelf-life limitations of resin-based products pose logistical challenges for distributors and contractors. A significant barrier remains the lack of standardized global certifications, which forces manufacturers to seek multiple approvals (e.g., ETA, ICC-ES) for different regions, increasing compliance costs.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Sensitivity to Installation Conditions and Curing Time | -0.7% | Global (High in Cold/Humid Regions) | 2025–2034 |
| Higher Material Cost Relative to Mechanical Anchors | -0.5% | Developing Markets | 2025–2029 |
Chemical Anchors Market Opportunities Analysis
Opportunities in the chemical anchors market are increasingly found in the renewable energy sector, particularly for securing wind turbine foundations and solar panel mounting systems. The burgeoning offshore wind industry presents a niche yet high-value market for specialized underwater-curing epoxy resins. Additionally, the adoption of Building Information Modeling (BIM) allows manufacturers to integrate their product specifications directly into the design phase, streamlining the procurement process. There is also a significant opportunity for market players to develop bio-based resins to cater to the growing demand for zero-carbon construction materials.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Renewable Energy Infrastructure | +1.1% | Europe and APAC | 2027–2034 |
| Digital Integration with BIM and Smart Sensors | +0.8% | Global | 2026–2034 |
Chemical Anchors Market Challenges Impact Analysis
The market faces significant challenges regarding the shortage of skilled labor capable of performing precise chemical anchor installations. Improper cleaning of the drilled hole or incorrect mixing of resin components can lead to catastrophic structural failures, leading to liability concerns for manufacturers. Additionally, volatile raw material prices for petroleum-based resins create pricing uncertainty. Environmental regulations targeting certain chemicals used in resin hardening agents also require continuous reformulation, challenging the R&D departments of major market participants.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Skilled Labor Shortage and Installation Errors | -0.6% | Global | 2025–2034 |
| Volatile Raw Material Pricing | -0.4% | Global | 2025–2030 |
Chemical Anchors Market - Updated Report Scope
This report provides a comprehensive analysis of the global chemical anchors market, covering resin types, product configurations, and end-user applications across six major geographical regions. It evaluates the impact of macroeconomic factors, technological innovations, and regulatory shifts on the market's growth trajectory. The scope includes a detailed competitive landscape, profiling the strategic moves of industry leaders and the emergence of specialized regional players. The data is validated through primary and secondary research, ensuring a high level of accuracy for strategic decision-making.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.12 Billion |
| Market Forecast in 2034 | USD 1.86 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Hilti Corporation, Fischer Group, ITW (Illinois Tool Works), Würth Group, Sika AG, Simpson Strong-Tie, Henkel AG & Co. KGaA, Rawlplug, Mungo Befestigungstechnik AG, HALFEN (Leviat), Powers Fasteners (Stanley Black & Decker), MKT Metall-Kunststoff-Technik, Chemfix Products Ltd, Araldite (Huntsman), Koelner Group, EJOT, Soudal, Tecfi S.p.A., Bit United, DKT International. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the chemical anchors market reflects the diverse engineering requirements across various construction environments. By resin type, the epoxy segment remains the benchmark for heavy-duty applications due to its superior shrinkage resistance and high bond strength. However, hybrid systems are rapidly gaining popularity as they combine the benefits of different resins to offer faster curing times and improved usability in cold weather. By product type, the injection system is the dominant choice for professional contractors due to its flexibility in varying hole depths and diameters, whereas capsules are preferred for standardized, repetitive installations in overhead or vertical applications.
- Resin Type: Epoxy, Vinyl Ester, Polyester, and Hybrid systems designed for specific structural needs.
- Product Type: Injection Anchors (Cartridges) and Capsule Anchors (Glass or Foil).
- End-User: Extensive application in Infrastructure (bridges/tunnels), Industrial (machinery mounting), and Residential (structural repair).
- Material/Substrate: Specialized formulations for Cracked Concrete, Uncracked Concrete, and Hollow Masonry.
Regional Highlights
- Asia Pacific: Holds over 35% of the global market share and is the fastest-growing region. Massive government spending on urban rail, airports, and housing in China, India, and Vietnam is driving demand.
- Europe: A mature market characterized by stringent safety standards (EOTA/ETA). Focus is on high-performance resins for seismic retrofitting and historic building restoration.
- North America: Significant growth driven by the commercial construction sector and the updating of bridge infrastructure under the Infrastructure Investment and Jobs Act.
- Middle East & Africa: Rapidly emerging as a hub for mega-projects, especially in Saudi Arabia (Vision 2030) and the UAE, where chemical anchors are used in extreme heat conditions.
- Latin America: Steady demand from the mining and energy sectors, particularly for heavy equipment anchoring in Brazil and Chile.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Chemical Anchors Market.- Hilti Corporation
- Fischer Group
- ITW (Illinois Tool Works)
- Würth Group
- Sika AG
- Simpson Strong-Tie
- Henkel AG & Co. KGaA
- Rawlplug
- Mungo Befestigungstechnik AG
- HALFEN (Leviat)
- Powers Fasteners (Stanley Black & Decker)
- MKT Metall-Kunststoff-Technik
- Chemfix Products Ltd
- Araldite (Huntsman)
- Koelner Group
- EJOT
- Soudal
- Tecfi S.p.A.
- Bit United
- DKT International
Frequently Asked Questions
What is the main advantage of using chemical anchors over mechanical anchors?
Chemical anchors provide a stress-free fix in the base material, as they do not rely on expansion forces. This allows them to be placed closer to edges and with smaller spacing, making them ideal for high-load applications and cracked concrete where mechanical anchors might fail.
Which resin type is best for heavy-duty structural applications?
Epoxy resins are generally considered the best for heavy-duty applications due to their high bond strength, low shrinkage, and excellent resistance to chemicals and moisture. They are frequently used for post-installed rebar and critical structural connections.
How does temperature affect the installation of chemical anchors?
Temperature significantly impacts the curing time of the resin. High temperatures accelerate the curing process, reducing the working time, while low temperatures slow it down. Specialized winter-grade and summer-grade resins are available to ensure performance across different climates.
Are chemical anchors suitable for underwater applications?
Yes, specific epoxy and vinyl ester formulations are designed to cure underwater or in water-saturated holes. These are commonly used in maritime infrastructure, bridge pier repair, and wastewater treatment plants.
What role do global certifications play in the chemical anchors market?
Certifications like the European Technical Assessment (ETA) and the ICC-ES in the United States are crucial. They provide standardized testing for load capacity, seismic performance, and fire resistance, ensuring that products meet strict safety codes required for large-scale engineering projects.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
