Charging As A Service Market
Charging As A Service Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710890 | Published On : September 14, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Charging As A Service Market Size
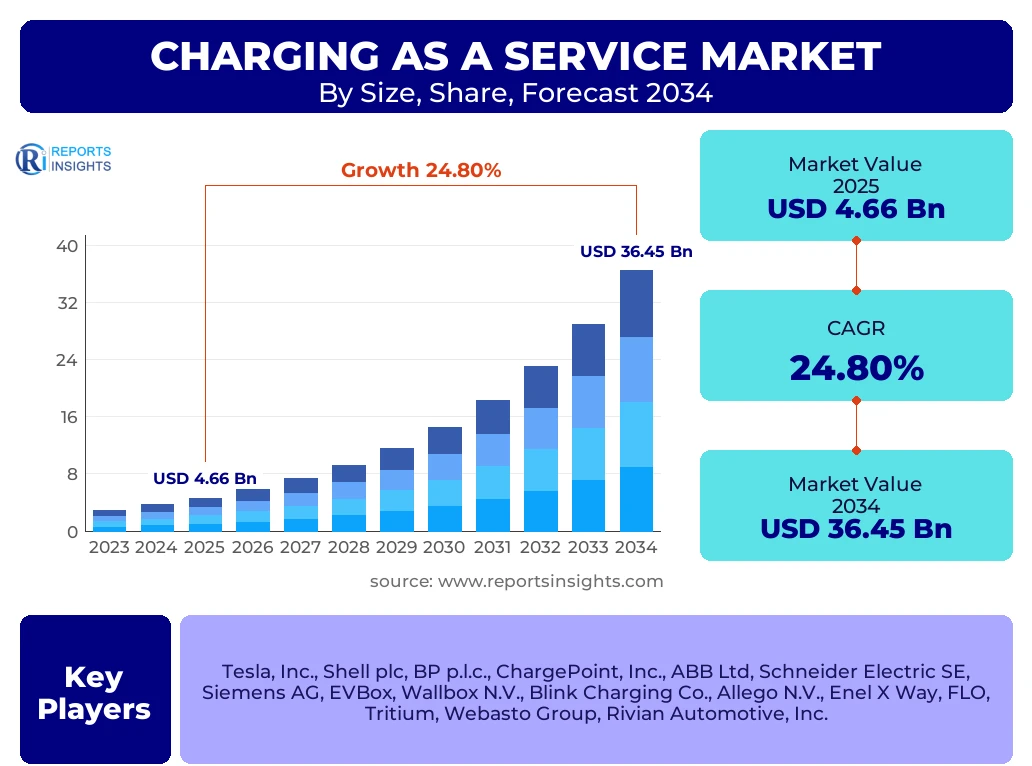
According to Reports Insights Consulting Pvt Ltd, The Charging As A Service Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 24.8% between 2026 and 2034. The market is estimated at USD 5.82 Billion in 2026 and is projected to reach USD 36.45 Billion by the end of the forecast period in 2034.
Key Charging As A Service Market Trends & Insights
The Charging as a Service (CaaS) market is undergoing a significant transformation as businesses shift from ownership-heavy capital expenditure models to subscription-based operational models. This transition is primarily driven by the rapid electrification of commercial fleets and the demand for scalable, turnkey infrastructure solutions that minimize upfront financial risk. Current market inquiries focus heavily on the integration of renewable energy sources, the development of smart grid technologies, and the role of software-defined charging platforms. Competitive benchmarking reveals that leading providers are increasingly bundling hardware, software, maintenance, and energy management into single-rate monthly subscriptions, which appeals to logistics companies and multi-unit residential developers alike. Furthermore, the convergence of CaaS with energy storage solutions is emerging as a critical trend to mitigate peak demand charges and enhance grid stability.
- Largest Region: North America currently holds the largest market share due to early adoption of fleet electrification and robust government support.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, fueled by massive infrastructure investments in China, India, and Southeast Asia.
- Leading Segment by Service Model: The Subscription-based model is the largest segment as it provides predictable operational costs for enterprise clients.
- Dominant Application Segment: Commercial Fleets (logistics and delivery) represent the largest revenue share owing to the high frequency of charging cycles.
Key Takeaways Charging As A Service Market Size & Forecast
The global trajectory for Charging as a Service is characterized by a move toward decentralized energy management and the democratization of EV infrastructure. Stakeholders are increasingly asking about the long-term viability of CaaS versus traditional procurement and the impact of regional regulations on cross-border charging interoperability. The forecast suggests a robust expansion as the automotive industry nears the tipping point of internal combustion engine (ICE) phase-outs. The market is not merely about providing electricity but is evolving into a complex ecosystem of data analytics, grid services, and customer experience management. Strategic partnerships between energy utilities and CaaS providers are expected to define the competitive landscape over the next decade.
- High Capital Efficiency: The CaaS model allows businesses to deploy charging stations without the burden of high initial investment, accelerating the ROI on EV transitions.
- Technological Integration: Advanced AI-driven software for load balancing and predictive maintenance is becoming a standard offering in CaaS contracts.
- Regional Leadership: The United States and China are the primary engines of market volume, while European nations lead in regulatory framework maturity.
- Energy Optimization: Managed charging services that utilize off-peak electricity rates are providing significant cost savings for large-scale fleet operators.
Charging As A Service Market Drivers Analysis
The primary catalyst for the CaaS market is the aggressive electrification targets set by major corporations and government bodies globally. As companies commit to Net Zero goals, the logistical challenge of fueling an electric fleet becomes a core operational hurdle. CaaS removes the technical and financial complexity of installing, maintaining, and managing these systems. Additionally, the proliferation of Electric Vehicle (EV) models with longer ranges and faster charging capabilities is necessitating more sophisticated infrastructure that CaaS providers are better equipped to manage than individual property owners.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Shift Toward Fleet Electrification | +8.5% | Global (High in Europe/North America) | 2025 - 2034 |
| Government Subsidies and Tax Credits (e.g., NEVI, IRA) | +6.2% | United States and EU Member States | 2025 - 2030 |
| Advancements in Smart Grid and V2G Technology | +4.1% | Japan, South Korea, and Germany | 2027 - 2034 |
Charging As A Service Market Restraints Analysis
Despite the optimistic growth projections, several factors act as brakes on the market. The most prominent restraint is the inadequate capacity of existing power grids in many urban and industrial areas, which often requires expensive upgrades that neither the provider nor the client wants to fund. Furthermore, the lack of standardized communication protocols between different hardware manufacturers and software platforms can lead to vendor lock-in, making potential clients hesitant to commit to long-term service contracts.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Grid Capacity Limitations and High Utility Upgrade Costs | -3.5% | Global (Developing Economies) | 2025 - 2034 |
| Lack of Standardization and Interoperability Issues | -2.1% | Middle East and Latin America | 2025 - 2029 |
Charging As A Service Market Opportunities Analysis
The integration of Vehicle-to-Grid (V2G) capabilities presents a massive opportunity for CaaS providers to turn EVs into mobile battery assets. By managing these assets, CaaS providers can sell energy back to the grid during peak demand, creating a secondary revenue stream that can lower subscription costs for the end-user. Additionally, the expansion of CaaS into the multi-unit dwelling (MUD) sector remains largely untapped, offering a significant growth runway as more urban residents transition to electric mobility.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of V2G and Energy Storage Systems | +5.4% | Scandinavia, California, Japan | 2026 - 2034 |
| Expansion into Residential Multi-Unit Dwellings | +4.8% | Urban Centers (Global) | 2025 - 2034 |
Charging As A Service Market Challenges Impact Analysis
Security and data privacy represent significant challenges as charging stations become IoT-connected endpoints. Protecting the payment data of users and the operational data of commercial fleets is paramount. Moreover, the volatility of electricity prices in certain regions can make it difficult for CaaS providers to offer fixed-rate long-term contracts without significant risk hedging, which may increase the price for the consumer.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks and Data Privacy Regulations | -1.8% | European Union (GDPR compliance) | 2025 - 2034 |
| Volatility in Global Electricity Markets | -2.4% | United Kingdom, Australia, Germany | 2025 - 2028 |
Charging As A Service Market - Updated Report Scope
The report provides an exhaustive analysis of the Charging as a Service (CaaS) landscape, covering the entire value chain from hardware components to advanced software management platforms. It examines various business models including monthly subscriptions, pay-per-use, and revenue-sharing agreements across residential, commercial, and industrial sectors. The scope includes detailed competitive analysis, technological roadmaps, and regional regulatory impacts across 25+ countries.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.66 Billion |
| Market Forecast in 2034 | USD 36.45 Billion |
| Growth Rate | 24.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Tesla, Inc., Shell plc, BP p.l.c., ChargePoint, Inc., ABB Ltd, Schneider Electric SE, Siemens AG, EVBox, Wallbox N.V., Blink Charging Co., Allego N.V., Enel X Way, FLO, Tritium, Webasto Group, Rivian Automotive, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to provide granular insights into the diverse applications and technological configurations available in the CaaS ecosystem. Analyzing these segments helps stakeholders identify high-growth niches, such as DC Fast Charging for heavy-duty logistics or subscription-based workplace charging programs. Each segment is evaluated based on current market value, growth potential, and the competitive landscape within that specific vertical.
- By Service Model:
- Subscription-based Model: The dominant model providing fixed monthly costs.
- Pay-per-use Model: Popular for public charging and occasional users.
- Managed Services: Comprehensive solutions including site design and installation.
- By Charging Type:
- Level 2 (AC): Standard for workplace and overnight residential charging.
- DC Fast Charging: Critical for highways and commercial fleet turnaround.
- Wireless/Inductive Charging: Emerging segment for premium and autonomous vehicles.
- By End-User:
- Commercial Fleets: Logistics, delivery, and public transit.
- Residential: Apartment complexes and condominiums.
- Public Locations: Shopping malls, airports, and parking garages.
- Corporate Workplaces: Employee incentive charging programs.
Regional Highlights
- North America: Currently the largest market share holder, driven by aggressive corporate sustainability mandates and substantial federal funding like the Bipartisan Infrastructure Law in the United States.
- Europe: Leads in regulatory maturity and interoperability standards. Countries like Norway, Germany, and the Netherlands are pioneers in integrating CaaS with urban planning.
- Asia-Pacific: The fastest-growing region due to the massive scale of EV adoption in China and the emerging manufacturing hubs in India and Southeast Asia. The region is a leader in low-cost hardware production.
- Latin America & MEA: These regions are in the early stages of adoption, with growth concentrated in major metropolitan hubs like São Paulo, Dubai, and Johannesburg, often driven by high-end commercial projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Charging As A Service Market.- Tesla, Inc.
- Shell plc (Shell Recharge)
- BP p.l.c. (bp pulse)
- ChargePoint, Inc.
- ABB Ltd
- Schneider Electric SE
- Siemens AG
- EVBox (ENGIE)
- Wallbox N.V.
- Blink Charging Co.
- Allego N.V.
- Enel X Way
- FLO (AddEnergie)
- Tritium
- Webasto Group
- Rivian Automotive, Inc. (Waypoints)
- EVgo Services LLC
- Star Charge
- Telo Charging
- FreeWire Technologies
Frequently Asked Questions
What is Charging as a Service (CaaS) and how does it differ from traditional charging station ownership?
CaaS is a service-based business model where customers pay a recurring fee (subscription) or a usage-based fee to access EV charging infrastructure, rather than buying the hardware outright. Unlike traditional ownership, the CaaS provider typically handles the installation, maintenance, software updates, and energy management, shifting the cost from a Capital Expenditure (CAPEX) to an Operational Expenditure (OPEX).
Which industries are the primary adopters of Charging as a Service?
The primary adopters are commercial fleet operators (logistics and delivery), multi-unit residential property managers, corporate offices, and hospitality sectors. These industries benefit from CaaS because it allows them to provide charging services to employees, residents, or fleet vehicles without the technical complexity and high initial costs of infrastructure management.
What are the key technological drivers in the CaaS market for 2026-2034?
Key drivers include the integration of AI for smart load management, the adoption of Vehicle-to-Grid (V2G) technology, and the development of ultra-fast DC charging solutions. These technologies allow CaaS providers to optimize energy costs and provide faster turnaround times for high-utilization vehicles like electric trucks and buses.
How do government regulations influence the growth of the CaaS market?
Governments influence the market through subsidies for infrastructure deployment, mandates for zero-emission vehicle sales, and the standardization of charging connectors and payment systems. Policies such as the US Inflation Reduction Act and the European Green Deal provide financial incentives that directly lower the cost for CaaS providers to expand their networks.
What is the expected market growth in the Asia-Pacific region compared to North America?
While North America currently holds the largest market share due to early corporate adoption, the Asia-Pacific region is expected to grow at the highest CAGR. This is due to rapid urbanization, massive government support for EV infrastructure in China and India, and a high concentration of EV manufacturers in the region, which accelerates the need for scalable charging services.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted