Cell Banking Outsourcing Market
Cell Banking Outsourcing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710959 | Published On : September 22, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Cell Banking Outsourcing Market Size
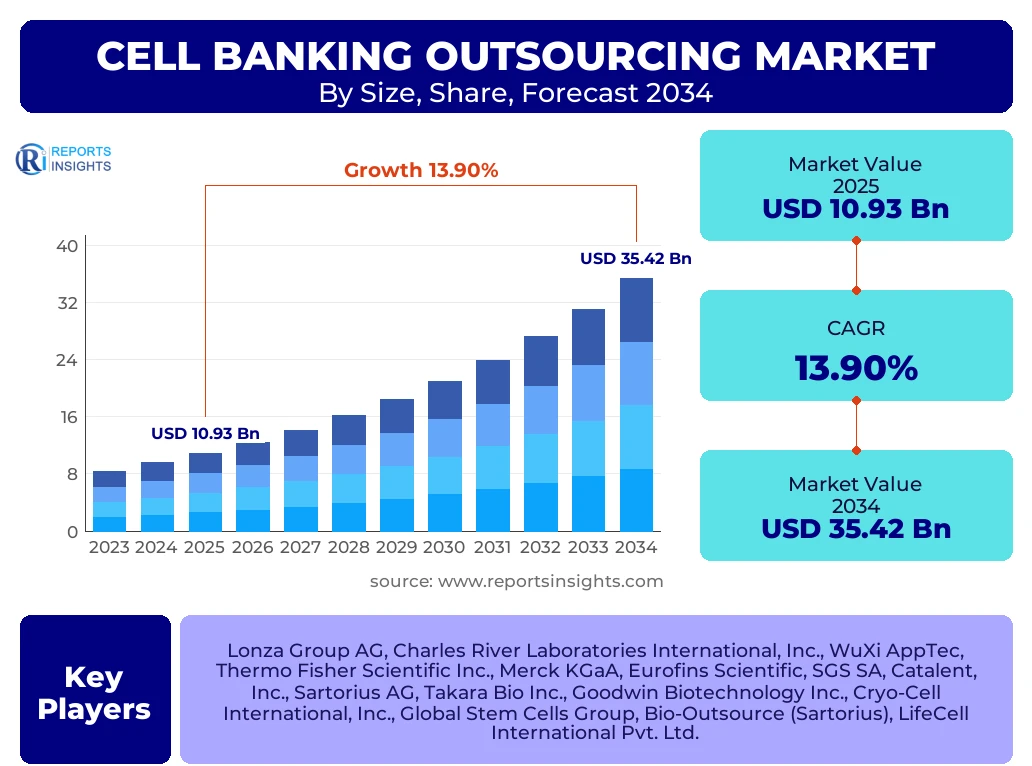
According to Reports Insights Consulting Pvt Ltd, The Cell Banking Outsourcing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.9% between 2026 and 2034. The market is estimated at USD 12.45 Billion in 2026 and is projected to reach USD 35.42 Billion by the end of the forecast period in 2034.
Key Cell Banking Outsourcing Market Trends & Insights
The Cell Banking Outsourcing market is undergoing a significant transformation driven by the escalating demand for advanced therapy medicinal products (ATMPs) and the increasing complexity of regulatory frameworks globally. Stakeholders are progressively shifting away from capital-intensive in-house storage solutions toward specialized Contract Development and Manufacturing Organizations (CDMOs) that offer state-of-the-art cryopreservation and master cell bank (MCB) characterization. A primary trend observed is the integration of automated robotic systems in cell handling, which minimizes human error and enhances the viability of sensitive cell lines. Furthermore, the rise of personalized medicine and autologous cell therapies has necessitated decentralized yet highly standardized cell banking protocols, leading to a surge in regional outsourcing partnerships to ensure logistical efficiency and maintain the cold chain integrity.
- North America currently stands as the largest region by market share, driven by a robust pipeline of clinical trials and high investment in regenerative medicine.
- The Asia-Pacific region is identified as the fastest-growing market due to rapid infrastructure development and expanding biopharmaceutical manufacturing hubs in China and India.
- The Master Cell Banking (MCB) segment holds the largest market share as it serves as the foundational resource for all subsequent production batches.
- Increased adoption of viral cell banking is becoming a critical sub-trend as the demand for viral vectors in gene therapy continues to skyrocket.
Key Takeaways Cell Banking Outsourcing Market Size & Forecast
The global outlook for the Cell Banking Outsourcing market remains highly bullish as pharmaceutical companies prioritize core competencies in drug discovery while delegating storage and characterization to expert third-party providers. The transition toward biologics and biosimilars is a major tailwind, requiring rigorous stability testing and long-term storage of working cell banks (WCB). Analysts note that the market is becoming increasingly consolidated, with tier-one players acquiring specialized niche laboratories to offer end-to-end "vein-to-vein" solutions. Regulatory harmonization across the EU and North America is also facilitating smoother cross-border cell line transfers, further incentivizing international outsourcing models.
- The United States is the leading country globally, accounting for over 35 percent of the total market value due to its advanced biotech ecosystem.
- The Stem Cell segment is expected to witness the highest growth rate within the cell type category, fueled by breakthroughs in degenerative disease research.
- Working Cell Bank (WCB) services are seeing increased volume as late-stage clinical trials transition into commercial manufacturing phases.
- Market volatility in supply chain logistics has led to a strategic emphasis on redundant storage locations across different geographic zones to mitigate risk.
Cell Banking Outsourcing Market Drivers Analysis
The primary catalysts for the Cell Banking Outsourcing market involve the rapid expansion of the biopharmaceutical sector and the inherent cost-efficiencies associated with third-party management. Maintaining high-standard cryogenic facilities requires significant capital expenditure and specialized personnel, which many emerging biotech firms prefer to outsource to manage burn rates effectively. Additionally, the stringent requirements of Good Manufacturing Practices (GMP) make it challenging for smaller entities to maintain compliance internally, making outsourcing a strategic necessity for market entry.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise in Cell and Gene Therapy (CGT) Approvals | +4.2% | Global (High in US/EU) | 2025 - 2034 |
| Cost Reduction and Risk Mitigation Strategies | +3.1% | Asia-Pacific, Latin America | 2026 - 2030 |
| Technological Advancements in Cryopreservation | +2.8% | Germany, Japan, USA | 2025 - 2034 |
Cell Banking Outsourcing Market Restraints Analysis
Despite the positive growth trajectory, the market faces restraints related to the high cost of specialized testing and the complex legal landscape regarding intellectual property. Many organizations remain hesitant to transfer proprietary cell lines to third parties due to fears of IP leakage or contamination during transit. Furthermore, the lack of standardized global regulations for certain emerging cell types creates hurdles for providers operating across multiple jurisdictions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory and Compliance Hurdles | -1.5% | European Union, China | 2025 - 2028 |
| Concerns Over Data Privacy and IP Security | -0.8% | Global | Ongoing |
Cell Banking Outsourcing Market Opportunities Analysis
The market is ripe with opportunities in the development of "smart banking" solutions, where IoT and AI are utilized to monitor cell health in real-time within cryogenic tanks. There is also a massive untapped potential in emerging markets where clinical trial density is increasing. Furthermore, the expansion of cell banking services into non-traditional areas like personalized nutrition and veterinary medicine offers new avenues for revenue diversification for established CDMOs.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Integrated Storage and Monitoring Systems | +2.5% | USA, South Korea | 2027 - 2034 |
| Expansion into Veterinary Regenerative Medicine | +1.2% | North America, Brazil | 2028 - 2034 |
| Growth in Emerging Biotech Hubs | +3.4% | India, Singapore, Ireland | 2026 - 2032 |
Cell Banking Outsourcing Market Challenges Impact Analysis
Operational challenges remain a significant factor, particularly the maintenance of a seamless ultra-cold supply chain across international borders. Any fluctuation in temperature or delay in logistics can compromise decades of research or millions of dollars in inventory. Additionally, the shortage of highly skilled labor capable of managing sophisticated cell banking protocols remains a bottleneck for the scaling of outsourcing facilities.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Logistical Complexities in Cold Chain Management | -1.1% | Africa, Southeast Asia | 2025 - 2030 |
| Skilled Workforce Deficit in Biotechnology | -0.9% | UK, Canada, USA | 2025 - 2034 |
Cell Banking Outsourcing Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global cell banking outsourcing landscape, evaluating current market dynamics, technological shifts, and the competitive environment. It covers various service types, including Master Cell Banking and Working Cell Banking, categorized by cell types such as stem cells and differentiated cells. The study provides granular data on revenue forecasts, regional growth patterns, and the strategic maneuvers of lead industry participants from 2025 through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.93 Billion |
| Market Forecast in 2034 | USD 35.42 Billion |
| Growth Rate | 13.9% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Lonza Group AG, Charles River Laboratories International, Inc., WuXi AppTec, Thermo Fisher Scientific Inc., Merck KGaA, Eurofins Scientific, SGS SA, Catalent, Inc., Sartorius AG, Takara Bio Inc., Goodwin Biotechnology Inc., Cryo-Cell International, Inc., Global Stem Cells Group, Bio-Outsource (Sartorius), LifeCell International Pvt. Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Cell Banking Outsourcing market is multidimensional, reflecting the diverse needs of the life sciences industry. The market is primarily divided by banking type, where Master Cell Banking (MCB) acts as the high-integrity source, and Working Cell Banking (WCB) serves as the routine production material. Further segmentation by cell type reveals a significant dominance in stem cell banking due to its extensive use in regenerative medicine. Application-based segments highlight the biopharmaceutical sector as the largest consumer, though gene therapy is growing at a faster rate due to recent clinical successes.
- By Type: Master Cell Banking, Working Cell Banking, Viral Cell Banking.
- By Cell Type: Stem Cells (Embryonic, Adult, IPSCs), Differentiated Cells (Human Cell Lines, Animal Cell Lines).
- By Application: Stem Cell Therapy, Biopharmaceutical Production, Gene Therapy, Vaccine Development, Toxicity Testing.
- By End-User: Pharmaceutical and Biopharmaceutical Companies, Contract Research Organizations (CROs), Academic and Research Institutes.
Regional Highlights
- North America: Holds the largest market share (approx. 38%) due to a high density of biotech startups, supportive government funding for regenerative medicine, and the presence of major industry players.
- Asia-Pacific: Forecasted as the fastest-growing region with a CAGR of 15.2%, driven by increasing healthcare expenditure in China and India and the emergence of these nations as global hubs for biosimilar production.
- Europe: A mature market characterized by stringent EMA regulations and a strong focus on advanced cell therapy research in Germany, France, and the UK.
- Latin America: Showing steady growth in cell banking for clinical trials, particularly in Brazil and Mexico, as companies look for diverse patient populations.
- Middle East and Africa: Growth is primarily centered in specialized medical hubs like the UAE and Israel, focusing on high-end stem cell research and storage.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cell Banking Outsourcing Market.- Lonza Group AG
- Charles River Laboratories International, Inc.
- WuXi AppTec
- Thermo Fisher Scientific Inc.
- Merck KGaA
- Eurofins Scientific
- SGS SA
- Catalent, Inc.
- Sartorius AG
- Takara Bio Inc.
- Goodwin Biotechnology Inc.
- Cryo-Cell International, Inc.
- Global Stem Cells Group
- Bio-Outsource
- LifeCell International Pvt. Ltd.
- Cordlife Group Limited
- Intertek Group plc
- BSI Group
- Reliance Life Sciences
Frequently Asked Questions
What is the primary difference between Master Cell Banking and Working Cell Banking in outsourcing?
Master Cell Banking (MCB) involves the creation of a large volume of cells from a single clone, stored for the long term to ensure a consistent source. Working Cell Banking (WCB) is derived from the MCB and is used for routine manufacturing. Outsourcing these ensures that both tiers meet stringent GMP standards and are stored in redundant, high-security environments.
Why are biopharmaceutical companies increasingly outsourcing cell banking services?
Companies outsource to reduce capital expenditure on specialized cryogenic facilities, access expert regulatory compliance knowledge, mitigate the risk of contamination, and leverage the advanced characterization technologies offered by specialized CDMOs.
How does the rise of gene therapy affect the Cell Banking Outsourcing market?
Gene therapy relies heavily on viral vectors. The need for specialized Viral Cell Banking to store and characterize the producer cells used in vector production has created a high-growth niche within the outsourcing market, requiring higher biosafety levels (BSL).
Which region is expected to show the highest growth in the coming decade?
The Asia-Pacific region is expected to show the highest CAGR due to favorable government policies, a lower cost of operation, and a rapidly expanding biomanufacturing infrastructure in countries like India, China, and South Korea.
What are the main regulatory standards governing cell banking outsourcing?
The market is primarily governed by Current Good Manufacturing Practices (cGMP), and guidelines from the FDA (US), EMA (Europe), and ICH (International Council for Harmonisation), which dictate the protocols for characterization, stability testing, and storage safety.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted