Cardiovascular Soft Tissue Repair Patch Market
Cardiovascular Soft Tissue Repair Patch Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711088 | Published On : October 06, 2026 |
Format : 


 | Author : Erika Grotto
Cardiovascular Soft Tissue Repair Patch Market Size
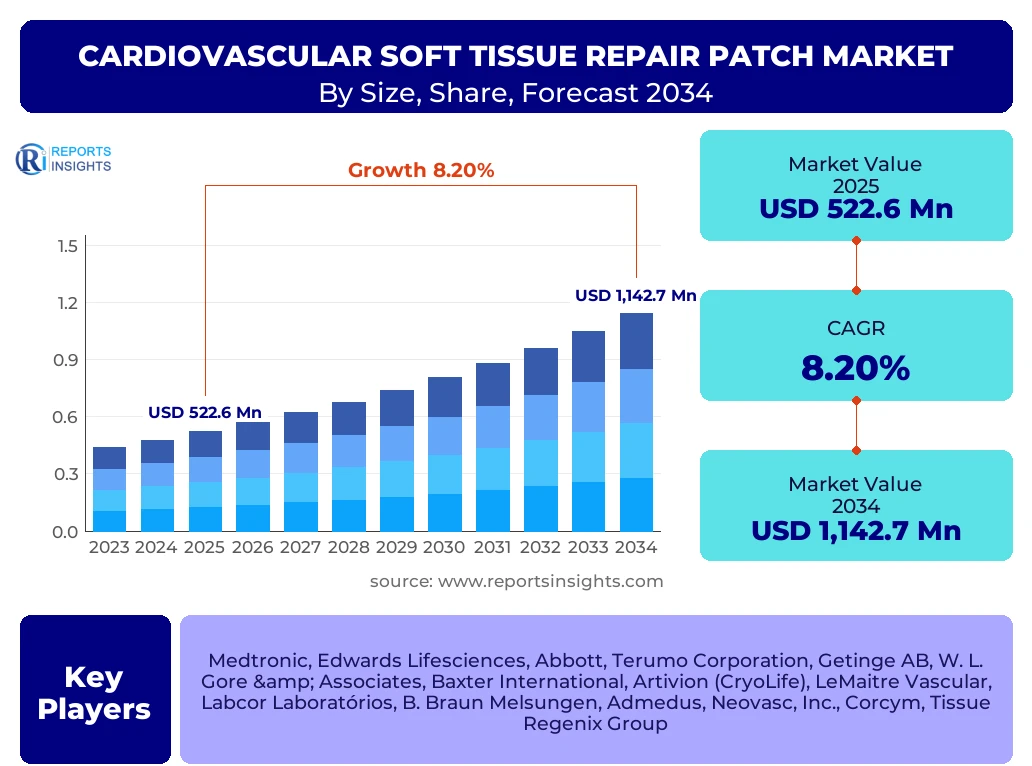
According to Reports Insights Consulting Pvt Ltd, The Cardiovascular Soft Tissue Repair Patch Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 565.4 Million in 2026 and is projected to reach USD 1,142.7 Million by the end of the forecast period in 2034.
Key Cardiovascular Soft Tissue Repair Patch Market Trends & Insights
The cardiovascular soft tissue repair patch market is undergoing a significant transformation driven by advancements in regenerative medicine and the increasing prevalence of congenital heart diseases and degenerative cardiac conditions. Modern surgical trends emphasize the transition from traditional synthetic materials, such as polytetrafluoroethylene (PTFE), toward biological and bio-engineered solutions that offer better biocompatibility and lower risks of calcification. Market intelligence indicates a surging demand for patches used in complex cardiac reconstructions, including septal defect repairs and great vessel reconstructions. High-growth regions are focusing on transcatheter-compatible patch designs, reflecting a broader shift toward minimally invasive cardiovascular surgeries that reduce patient recovery time and hospital stays.
- Largest Region: North America remains the largest regional market due to high healthcare expenditure and a robust regulatory framework for medical devices.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, fueled by expanding healthcare infrastructure in China and India and a rising geriatric population.
- Largest Segment by Share: Biological patches, specifically bovine pericardium patches, hold the largest market share due to their superior hemodynamic properties and reduced thrombogenicity.
- Leading Application: Septal defect repair remains the primary application area, though vascular repair is growing rapidly in the context of carotid endarterectomy.
Key Takeaways Cardiovascular Soft Tissue Repair Patch Market Size & Forecast
The forecast period from 2025 to 2034 is expected to witness a steady rise in market valuation, supported by the integration of tissue engineering and 3D bioprinting technologies. Stakeholders are increasingly investing in clinical trials to validate the long-term efficacy of extracellular matrix (ECM) based patches, which promote endogenous tissue growth rather than just providing a mechanical barrier. The market is also seeing a consolidation trend, where major medical device conglomerates are acquiring smaller, specialized biotech firms to enhance their regenerative medicine portfolios. Strategic focus is shifting toward emerging economies where the burden of rheumatic heart disease and untreated congenital defects remains high, presenting untapped opportunities for market expansion.
- The United States is the leading country in terms of value, driven by a high volume of pediatric cardiac surgeries and favorable reimbursement policies.
- Germany and France are the key contributors in the European market, focusing on advanced biocompatible materials and aortic root reconstructions.
- China represents a critical growth engine in APAC, with domestic manufacturers increasingly competing with global players through cost-effective biological patch offerings.
- Biological patches are expected to outpace synthetic alternatives in CAGR as surgeons prioritize materials that minimize the need for long-term anticoagulation therapy.
Cardiovascular Soft Tissue Repair Patch Market Drivers Analysis
The primary driver for the cardiovascular soft tissue repair patch market is the rising global incidence of cardiovascular diseases (CVDs), which remain the leading cause of mortality worldwide. Additionally, the increasing success rates of neonatal cardiac surgeries have led to a higher volume of procedures for congenital heart defects, such as atrial and ventricular septal defects. The growing preference for biological xenograft patches over synthetic options, due to their lower risk of infection and better integration with host tissues, is further propelling market growth across both developed and developing healthcare systems.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Congenital Heart Defects (CHD) | +2.4% | Global / Emerging Markets | 2025 - 2034 |
| Advancements in Tissue Engineering and Decellularization | +1.9% | North America / Europe | 2026 - 2032 |
| Increasing Geriatric Population and Degenerative Valve Diseases | +1.5% | Japan / Germany / USA | 2025 - 2034 |
| Preference for Minimally Invasive Cardiac Procedures | +1.2% | Developed Economies | 2027 - 2034 |
Cardiovascular Soft Tissue Repair Patch Market Restraints Analysis
Despite the positive growth outlook, the market faces restraints such as the high cost associated with advanced biological patches and the stringent regulatory approval processes required for xenograft-derived products. There are also concerns regarding the long-term durability of certain patch materials, particularly the risk of late-stage calcification in pediatric patients, which can necessitate re-interventions. Furthermore, the specialized skill set required for the precise placement of these patches in complex anatomical structures limits their adoption in rural or underfunded healthcare facilities.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Xenograft and Allograft Patches | -1.1% | Low-to-Middle Income Countries | 2025 - 2034 |
| Risk of Post-Surgical Calcification and Degradation | -0.8% | Pediatric Segment Globally | 2026 - 2030 |
| Strict Regulatory Hurdles for Animal-Derived Products | -0.6% | European Union (MDR) | 2025 - 2028 |
Cardiovascular Soft Tissue Repair Patch Market Opportunities Analysis
The integration of 3D bioprinting and the development of "off-the-shelf" tissue-engineered vascular grafts represent massive opportunities for market players. There is also a significant opportunity in the development of antimicrobial-coated patches to reduce the incidence of prosthetic valve endocarditis and other surgical site infections. Expanding into emerging markets like India, Brazil, and Southeast Asia, where the middle class is growing and healthcare access is improving, allows companies to establish long-term market presence through localized manufacturing and distribution partnerships.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-Absorbable and Scaffold-Based Patches | +2.1% | North America / Japan | 2027 - 2034 |
| Expansion into Untreated Congenital Heart Disease Markets | +1.7% | India / Africa / SE Asia | 2025 - 2034 |
| Utilization of 3D Bioprinting for Personalized Patch Designs | +1.3% | Innovation Hubs (USA, South Korea) | 2028 - 2034 |
Cardiovascular Soft Tissue Repair Patch Market Challenges Impact Analysis
The primary challenge lies in achieving a balance between material strength and biological integration; patches must be robust enough to withstand high arterial pressures while being flexible enough to facilitate natural tissue remodeling. Supply chain complexities for animal-derived materials, including ethical sourcing and sterilization challenges, also pose significant hurdles. Additionally, the competitive landscape is intensifying, with new entrants offering lower-cost alternatives that challenge the market share of established multinational corporations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Maintaining Biocompatibility and Thromboresistance | -0.9% | R&D Departments Globally | 2025 - 2034 |
| Ethical and Religious Concerns Regarding Xenografts | -0.5% | Middle East / Specific Patient Groups | 2025 - 2034 |
| Complex Reimbursement Landscapes for New Technologies | -0.7% | Global | 2025 - 2029 |
Cardiovascular Soft Tissue Repair Patch Market - Updated Report Scope
The scope of this report covers the global cardiovascular soft tissue repair patch market across various material types, applications, and end-user facilities. It provides a detailed analysis of the shift from synthetic polymers to advanced biological matrices, evaluating the clinical and economic impact of these technologies. The report examines the competitive dynamics between traditional market leaders and emerging biotech firms specializing in regenerative cardiology, offering a comprehensive forecast based on historical trends and future technological breakthroughs.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 522.6 Million |
| Market Forecast in 2034 | USD 1,142.7 Million |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic, Edwards Lifesciences, Abbott, Terumo Corporation, Getinge AB, W. L. Gore & Associates, Baxter International, Artivion (CryoLife), LeMaitre Vascular, Labcor Laboratórios, B. Braun Melsungen, Admedus, Neovasc, Inc., Corcym, Tissue Regenix Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on material composition, surgical application, and the primary point of care. Biological patches currently dominate the landscape due to their superior clinical outcomes in terms of host-tissue integration and reduced risk of thromboembolism. Synthetic patches, while cost-effective and durable, are increasingly reserved for specific vascular applications where high mechanical strength is the priority. The hospital segment remains the largest end-user, but there is a growing trend of complex cardiovascular procedures being performed in specialized cardiac centers and ambulatory settings.
- By Material Type:
- Biological Patches (Bovine Pericardium, Porcine Pericardium, Allografts)
- Synthetic Patches (Polytetrafluoroethylene (PTFE), Dacron/Polyester)
- Tissue-Engineered / Decellularized Extracellular Matrix (ECM)
- By Application:
- Septal Defect Repair (Atrial and Ventricular)
- Vascular Repair and Reconstruction (Carotid, Aortic, Peripheral)
- Cardiac Patch Grafting
- Heart Valve Repair and Reinforcement
- By End-User:
- Hospitals and Tertiary Care Centers
- Specialized Cardiac Surgery Units
- Ambulatory Surgical Centers (ASCs)
Regional Highlights
- North America: The largest market globally, characterized by high adoption of tissue-engineered patches and significant R&D investment from major players like Medtronic and Abbott.
- Europe: A mature market with a heavy focus on regulatory compliance and clinical efficacy, where Germany and the UK lead in cardiac surgical innovation.
- Asia-Pacific: The fastest-growing region, with China and India expanding their healthcare infrastructure and increasing the number of pediatric cardiac screening programs.
- Latin America: Showing steady growth in countries like Brazil and Mexico, driven by improving access to specialized cardiovascular care.
- Middle East & Africa: A developing market where the demand is focused on treating congenital heart defects and rheumatic heart disease in younger populations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cardiovascular Soft Tissue Repair Patch Market.- Medtronic plc
- Edwards Lifesciences Corporation
- Abbott Laboratories
- Terumo Corporation
- Getinge AB (Maquet)
- W. L. Gore & Associates, Inc.
- Baxter International Inc.
- Artivion, Inc. (formerly CryoLife)
- LeMaitre Vascular, Inc.
- Labcor Laboratórios Ltda.
- B. Braun Melsungen AG
- Admedus (Anteris Technologies)
- Neovasc, Inc.
- Corcym S.r.l.
- Tissue Regenix Group plc
- Biological Dynamics, Inc.
- Aziyo Biologics, Inc.
- Xeltis BV
Frequently Asked Questions
What is the primary material used in cardiovascular soft tissue repair patches?
The primary material used is bovine pericardium, which is favored for its excellent biocompatibility, ease of handling during surgery, and lower risk of thrombosis compared to synthetic alternatives like PTFE.
Which application segment holds the largest share of the market?
Septal defect repair is currently the largest application segment, driven by the high prevalence of congenital heart defects and the standardization of patch-based surgical closure techniques.
How does the growth of minimally invasive surgery affect the patch market?
Minimally invasive surgery is driving the development of thinner, more flexible patches that can be delivered via transcatheter systems, creating a new high-growth sub-segment within the market.
What are the main advantages of biological patches over synthetic ones?
Biological patches offer better integration with the patient's own tissue, exhibit lower rates of calcification in many cases, and generally do not require long-term aggressive anticoagulant therapy.
Which region is expected to see the highest growth rate through 2034?
Asia-Pacific is expected to see the highest growth rate due to massive investments in healthcare infrastructure, a rising patient pool for cardiac surgeries, and the emergence of regional manufacturing hubs.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
