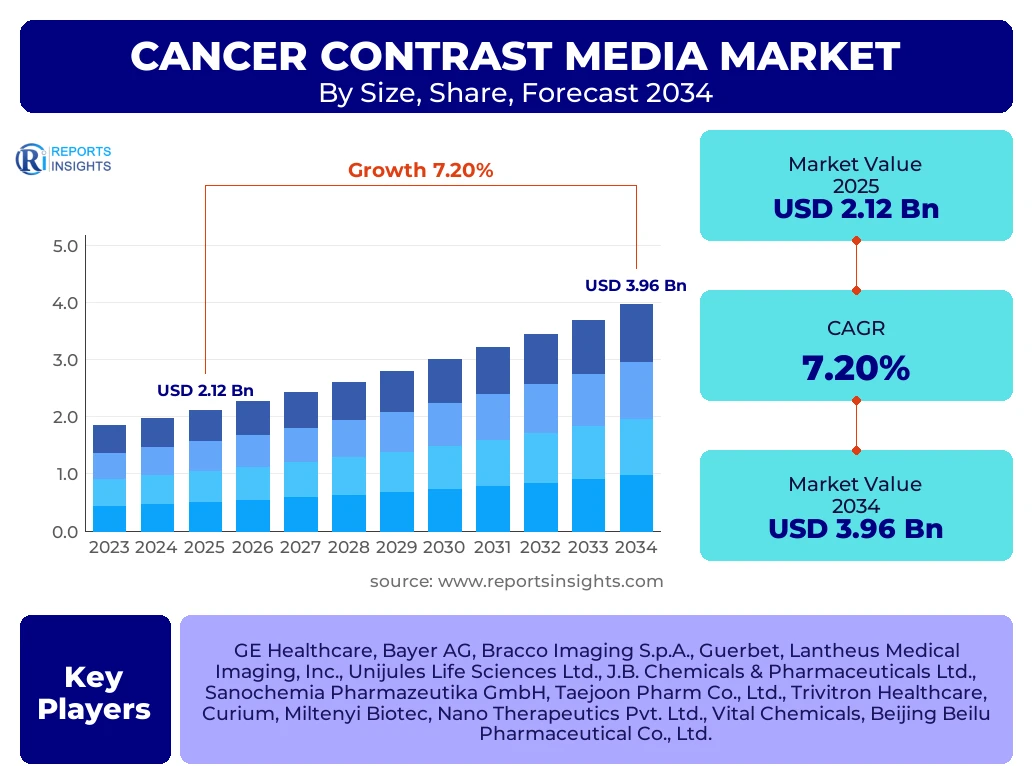
Cancer Contrast Media Market
Cancer Contrast Media Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711221 | Published On : October 19, 2026 |
Format : 


 | Author : Erika Grotto
Cancer Contrast Media Market Size
According to Reports Insights Consulting Pvt Ltd, The Cancer Contrast Media Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 2.28 Billion in 2026 and is projected to reach USD 3.96 Billion by the end of the forecast period in 2034.
Key Cancer Contrast Media Market Trends & Insights
The global landscape for cancer contrast media is currently undergoing a transformative phase driven by the integration of artificial intelligence (AI) and the shift toward precision oncology. Modern diagnostic protocols are increasingly relying on high-sensitivity contrast agents that allow for earlier detection of malignant tissues, particularly in complex cases such as dense breast tissue or early-stage pancreatic lesions. Furthermore, the market is seeing a significant move toward the development of macrocyclic gadolinium-based contrast agents (GBCAs), which offer higher stability and a lower risk of nephrogenic systemic fibrosis compared to older linear agents. These trends are further bolstered by the rising adoption of multi-modal imaging techniques, where contrast agents are optimized for simultaneous use across PET/CT and PET/MRI platforms to provide both anatomical and functional insights into tumor biology.
- Largest Region: North America remains the dominant regional market, accounting for a significant share due to high healthcare expenditure and advanced diagnostic infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, fueled by rapid expansion in healthcare facilities across China and India and a rising incidence of various cancer types.
- Largest Segment by Type: Iodinated contrast media continue to hold the largest market share owing to the high volume of CT scans performed globally for cancer staging and monitoring.
- Emerging Trend: The rise of theranostics, where contrast agents are paired with therapeutic isotopes to simultaneously diagnose and treat tumors, is creating new high-value opportunities.
Key Takeaways Cancer Contrast Media Market Size & Forecast
The market for cancer contrast media is fundamentally supported by the global imperative to reduce cancer mortality through early intervention. Analysis of current diagnostic pipelines indicates that the demand for MRI-specific contrast agents is growing at a faster rate than traditional X-ray agents, reflecting a clinical shift toward radiation-free imaging for long-term oncology surveillance. Strategic partnerships between contrast media manufacturers and medical imaging hardware providers are becoming more frequent, ensuring that new agents are perfectly calibrated for the latest high-field MRI and spectral CT scanners. This synergy is expected to drive higher diagnostic accuracy and reduce the required volume of contrast per patient, aligning with value-based healthcare models.
- The global market is anticipated to witness a steady expansion, reaching nearly USD 4 billion by 2034, driven by aging populations and lifestyle-related cancer surges.
- Hospitals and diagnostic imaging centers represent the primary end-users, with an increasing trend of specialized oncology clinics investing in in-house imaging suites.
- Regulatory approvals for generic contrast media are expected to increase price competition in mature markets, although premium, high-stability agents will maintain higher margins.
- Technological advancements in microbubble contrast agents for ultrasound are expanding the role of sonography in liver and breast cancer screening.
Cancer Contrast Media Market Drivers Analysis
The primary catalyst for the Cancer Contrast Media Market is the rising global burden of oncology-related diseases, which necessitates frequent and high-resolution imaging for diagnosis, staging, and treatment monitoring. Additionally, the rapid evolution of imaging technologies, such as the transition from standard CT to spectral and photon-counting CT, requires specialized contrast agents that can leverage these new hardware capabilities for better tissue differentiation. The growing emphasis on personalized medicine is also a significant driver, as contrast agents are increasingly used to assess tumor vascularity and predict response to anti-angiogenic therapies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Global Cancer Prevalence | +2.8% | Global (High in APAC) | Short-Long Term |
| Technological Advancements in CT/MRI | +1.5% | North America & Europe | Mid Term |
| Expansion of Diagnostic Centers | +1.2% | Emerging Markets | Short Term |
| Integration of AI in Radiology | +0.9% | Global | Mid-Long Term |
Cancer Contrast Media Market Restraints Analysis
Despite the growth, the market faces significant hurdles related to the safety profiles of certain agents, particularly the concerns surrounding gadolinium retention in the brain and other tissues. Regulatory bodies like the FDA and EMA have implemented stricter labeling and monitoring requirements, which can slow down product adoption and increase compliance costs. Furthermore, the high cost of advanced imaging procedures and the shortage of trained radiologists in developing nations limit the reach of contrast-enhanced diagnostics. The fluctuating prices of raw materials, particularly iodine, also place pressure on manufacturer margins.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Concerns Over Side Effects & Retention | -1.2% | Europe & North America | Short-Mid Term |
| High Cost of Advanced Imaging | -0.8% | Latin America & Africa | Mid Term |
| Shortage of Raw Materials (Iodine) | -0.5% | Global | Short Term |
Cancer Contrast Media Market Opportunities Analysis
The emergence of "targeted contrast agents" presents a revolutionary opportunity in the oncology sector. Unlike traditional agents that distribute generally through the bloodstream, targeted agents are conjugated with ligands that bind to specific biomarkers on tumor surfaces, allowing for unprecedented sensitivity in detecting micrometastases. Additionally, the market is ripe for expansion in emerging economies where government initiatives are aimed at decentralizing healthcare and improving early cancer detection rates. The development of eco-friendly and more biocompatible contrast agents also offers a path to differentiate products in a crowded marketplace.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Targeted Contrast Agents | +1.8% | Global (Research hubs) | Long Term |
| Government Screening Programs | +1.4% | China, India, Brazil | Mid Term |
| Emergence of Theranostic Platforms | +1.1% | United States, Germany | Mid-Long Term |
Cancer Contrast Media Market Challenges Impact Analysis
The Cancer Contrast Media Market must navigate complex regulatory landscapes that vary significantly between jurisdictions, complicating the launch of global products. Maintaining a secure supply chain for radioisotopes and rare-earth elements is another critical challenge, particularly in the face of geopolitical instability. Furthermore, the increasing pressure from payers and insurers to justify the cost-effectiveness of expensive contrast-enhanced scans versus traditional methods requires manufacturers to provide robust clinical evidence and real-world data.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complex Regulatory Approval Cycles | -0.7% | European Union, USA | Ongoing |
| Geopolitical Supply Chain Risks | -0.6% | Global | Short Term |
| Competition from Generic Entrants | -0.4% | Global | Ongoing |
Cancer Contrast Media Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the cancer contrast media landscape, covering global market dynamics, competitive benchmarking, and technological evolution. The scope includes detailed profiling of all major modalities and agent types, along with a granular analysis of end-user preferences and regional regulatory frameworks. It serves as a strategic roadmap for stakeholders looking to navigate the complexities of oncology diagnostics through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.12 Billion |
| Market Forecast in 2034 | USD 3.96 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | GE Healthcare, Bayer AG, Bracco Imaging S.p.A., Guerbet, Lantheus Medical Imaging, Inc., Unijules Life Sciences Ltd., J.B. Chemicals & Pharmaceuticals Ltd., Sanochemia Pharmazeutika GmbH, Taejoon Pharm Co., Ltd., Trivitron Healthcare, Curium, Miltenyi Biotec, Nano Therapeutics Pvt. Ltd., Vital Chemicals, Beijing Beilu Pharmaceutical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Cancer Contrast Media Market is segmented based on the biochemical composition of the agent and the imaging modality it serves. Iodinated agents remain the workhorse of clinical oncology due to their extensive use in CT-based staging. However, the MRI segment is expanding rapidly as clinicians prioritize the superior soft-tissue contrast provided by gadolinium-based agents for brain and spinal cord malignancies. Ultrasound microbubble agents are finding a niche in interventional oncology for real-time guidance during tumor ablation procedures. Segmentation by cancer type reveals that breast and lung cancer diagnostics account for the highest volume of contrast media consumption due to established screening programs.
- By Type:
- Iodinated Contrast Media
- Gadolinium-based Contrast Media
- Barium-based Contrast Media
- Microbubble Contrast Media
- By Modality:
- X-ray/Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Ultrasound
- By Application:
- Breast Cancer
- Lung Cancer
- Gastrointestinal Cancer
- Prostate Cancer
- Liver Cancer
- Others
Regional Highlights
The regional distribution of the market is characterized by varying levels of diagnostic adoption and healthcare infrastructure. North America is the largest market, driven by a high density of advanced imaging centers and a strong reimbursement framework for oncology procedures. Europe follows closely, with Germany and France leading in the adoption of macrocyclic agents due to proactive safety regulations. The Asia-Pacific region is identified as the fastest-growing market, largely due to the massive scaling of healthcare infrastructure in China and the increasing availability of MRI and CT services in secondary and tertiary cities. Latin America and the MEA region are seeing gradual growth, often supported by public-private partnerships aimed at modernizing cancer care facilities.
- North America: Market leader in value; characterized by high uptake of premium MRI agents.
- Europe: Leading in the transition to macrocyclic GBCAs and environmentally conscious contrast production.
- Asia-Pacific: Highest growth rate; driven by rising diagnostic awareness and medical tourism.
- Middle East & Africa: Increasing investment in oncology centers of excellence is boosting local demand.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cancer Contrast Media Market.- GE Healthcare
- Bayer AG
- Bracco Imaging S.p.A.
- Guerbet
- Lantheus Medical Imaging, Inc.
- Unijules Life Sciences Ltd.
- J.B. Chemicals & Pharmaceuticals Ltd.
- Sanochemia Pharmazeutika GmbH
- Taejoon Pharm Co., Ltd.
- Trivitron Healthcare
- Curium
- Miltenyi Biotec
- Nano Therapeutics Pvt. Ltd.
- Vital Chemicals
- Beijing Beilu Pharmaceutical Co., Ltd.
- Hengrui Medicine
- Subhra Pharma Private Limited
Frequently Asked Questions
What is the current market size of the Cancer Contrast Media Market?
The market is estimated to be valued at approximately USD 2.12 Billion in 2025 and is projected to grow significantly by 2034.
Which imaging modality dominates the use of contrast media in cancer?
Computed Tomography (CT) currently dominates the market due to its widespread use in cancer staging and the high volume of iodinated contrast media required for these scans.
What are the safety concerns associated with Gadolinium-based contrast agents?
The primary concern is gadolinium retention in the brain and other tissues, leading to a shift toward macrocyclic agents which are more stable and have a lower dissociation rate compared to linear agents.
Which region is expected to grow the fastest in the forecast period?
The Asia-Pacific region is expected to grow at the fastest CAGR due to increasing healthcare investments, a large patient population, and the expansion of diagnostic imaging networks.
How is AI impacting the cancer contrast media market?
AI is being used to enhance image quality from lower doses of contrast media, improve the speed of image interpretation, and help in the development of more effective targeted agents.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
