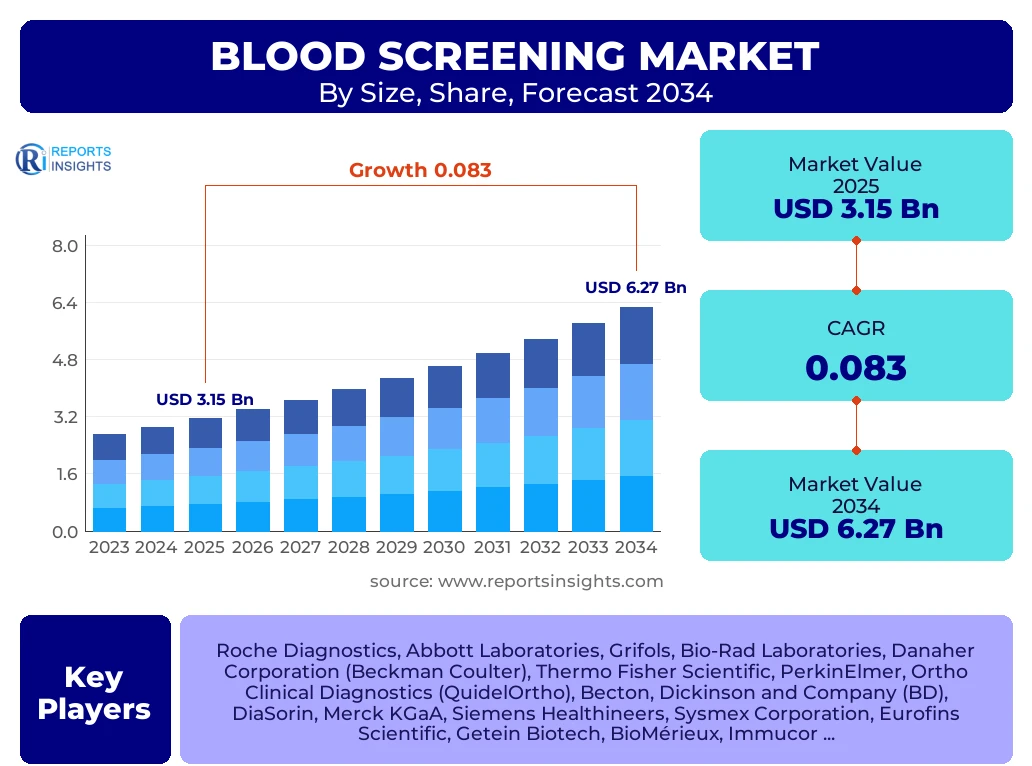
Blood Screening Market
Blood Screening Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711470 | Published On : November 03, 2026 |
Format : 


 | Author : Erika Grotto
Blood Screening Market Size
According to Reports Insights Consulting Pvt Ltd, The Blood Screening Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.3% between 2025 and 2034. The market is estimated at USD 3.41 Billion in 2026 and is projected to reach USD 6.27 Billion by the end of the forecast period in 2034.
Key Blood Screening Market Trends & Insights
The global blood screening landscape is currently undergoing a significant transformation, driven by the integration of high-throughput automation and the transition from traditional serological assays to more sensitive molecular diagnostic techniques. Stakeholders are increasingly focusing on reducing the "window period" of infectious diseases, leading to a surge in the adoption of Nucleic Acid Testing (NAT). The market is also witnessing a consolidation phase where major diagnostic players are acquiring niche technology firms to expand their multiplex testing capabilities, allowing for the simultaneous detection of multiple pathogens from a single blood sample. Furthermore, the rise of personalized medicine and the increasing requirement for precise blood typing and cross-matching in complex surgical procedures are steering the market toward more sophisticated, software-integrated screening ecosystems.
- North America remains the largest regional market, accounting for a dominant share due to stringent regulatory frameworks and high blood donation volumes.
- The Asia-Pacific region is identified as the fastest-growing market, propelled by rapidly improving healthcare infrastructure and government-led initiatives to mandate blood screening in emerging economies.
- The Reagents & Kits segment holds the largest market share by product, driven by the recurring need for consumables in high-volume testing environments.
- Nucleic Acid Testing (NAT) has emerged as the leading technology segment in terms of value, owing to its superior sensitivity in detecting viral loads compared to traditional ELISA methods.
- Blood Banks represent the largest end-user segment, as they serve as the primary hubs for large-scale donor screening and component separation.
Key Takeaways Blood Screening Market Size & Forecast
The Blood Screening Market is poised for robust expansion as healthcare systems worldwide prioritize the safety of blood transfusions and the prevention of Transfusion-Transmitted Infections (TTIs). The increasing frequency of blood donation camps, coupled with the rising prevalence of chronic diseases requiring blood components, ensures a steady demand for screening instruments and reagents. Technological convergence, such as the use of Artificial Intelligence (AI) in screening software for predictive analysis and error reduction, is expected to be a major growth catalyst over the next decade. The forecast indicates that while developed nations will focus on technological replacement and optimization, developing nations will provide significant volume-based growth as they align their national health policies with international blood safety standards.
- The United States is the leading country globally, supported by the presence of major industry players and a highly organized blood collection infrastructure.
- Technological advancements in Next-Generation Sequencing (NGS) are beginning to influence the blood screening market, offering potential for even more comprehensive donor profiling.
- Government mandates in countries like China and India regarding mandatory screening for HIV, Hepatitis B, and Hepatitis C are significantly boosting regional market valuations.
- The shift toward automated liquid handling and robotic workstations in blood banks is reducing manual errors and operational costs, improving overall market efficiency.
- The sustainability of the market is reinforced by a steady increase in the global geriatric population, which correlates with higher demand for surgeries and subsequent blood transfusions.
Blood Screening Market Drivers Analysis
The primary catalysts for the Blood Screening Market involve a combination of regulatory pressures, epidemiological shifts, and technological breakthroughs. As the global incidence of infectious diseases such as HIV, Hepatitis, and Zika virus continues to pose public health risks, the necessity for rigorous blood screening becomes paramount. This demand is further amplified by the modernization of blood banking facilities and the global push for "Zero Risk" transfusion policies, which encourage the adoption of high-sensitivity molecular assays over conventional methods.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Transfusion-Transmitted Infections (TTIs) | +2.4% | Global / Sub-Saharan Africa / SE Asia | 2025 - 2034 |
| Technological Shift toward Nucleic Acid Testing (NAT) | +1.9% | North America / Europe | 2025 - 2030 |
| Increasing Number of Voluntary Blood Donations | +1.5% | Asia Pacific / Latin America | 2026 - 2034 |
| Stringent Government Regulations for Blood Safety | +2.5% | European Union / USA | 2025 - 2034 |
Blood Screening Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant hurdles, particularly regarding the high capital expenditure required for advanced screening platforms. In many low-income regions, the cost of implementing NAT and maintaining high-throughput automated systems remains a barrier to universal blood safety. Additionally, the shortage of highly skilled laboratory personnel capable of operating sophisticated molecular diagnostic equipment restricts the full-scale deployment of advanced screening technologies in developing countries.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Screening Instruments | -1.2% | Emerging Markets / Africa | 2025 - 2028 |
| Lack of Skilled Workforce for Molecular Diagnostics | -0.8% | Asia Pacific / Latin America | 2025 - 2034 |
Blood Screening Market Opportunities Analysis
The evolution of the Blood Screening Market is opening new avenues for growth, particularly through the expansion of personalized medicine and the integration of digital health solutions. There is a massive opportunity for manufacturers to develop cost-effective, point-of-care (POC) blood screening devices for use in remote or resource-limited settings. Furthermore, the application of Next-Generation Sequencing (NGS) for rare blood group identification and comprehensive pathogen detection presents a high-value frontier for market participants seeking to differentiate their offerings.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of NGS for Comprehensive Donor Screening | +1.7% | USA / Germany / Japan | 2027 - 2034 |
| Expansion into Emerging Healthcare Markets | +2.1% | India / China / Brazil | 2026 - 2034 |
| Development of AI-driven Screening Software | +1.3% | Global / Tech-centric Hubs | 2028 - 2034 |
Blood Screening Market Challenges Impact Analysis
Market players must navigate complex regulatory environments that vary significantly across jurisdictions, often delaying the launch of new screening assays. The logistical challenges of maintaining a cold chain for temperature-sensitive reagents, especially in tropical climates, also pose a consistent threat to operational continuity. Moreover, the emergence of novel or variant pathogens requires constant R&D investment to ensure that existing screening kits remain effective against new viral strains.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent and Varied Regulatory Approval Processes | -1.1% | Global | 2025 - 2034 |
| Reagent Cold-Chain Logistics in Remote Areas | -0.7% | MEA / Southeast Asia | 2025 - 2030 |
Blood Screening Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global blood screening market, covering various technological platforms, product types, and end-user facilities. It provides a comprehensive outlook on the market's historical performance while projecting future growth based on current epidemiological trends and technological innovations. The report offers a deep dive into the competitive landscape, highlighting the strategic maneuvers of key market participants and the regulatory shifts influencing global trade in blood diagnostic products.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.15 Billion |
| Market Forecast in 2034 | USD 6.27 Billion |
| Growth Rate | 8.3% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Roche Diagnostics, Abbott Laboratories, Grifols, Bio-Rad Laboratories, Danaher Corporation (Beckman Coulter), Thermo Fisher Scientific, PerkinElmer, Ortho Clinical Diagnostics (QuidelOrtho), Becton, Dickinson and Company (BD), DiaSorin, Merck KGaA, Siemens Healthineers, Sysmex Corporation, Eurofins Scientific, Getein Biotech, BioMérieux, Immucor, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Blood Screening Market is segmented into products, technologies, and end-users to provide a granular view of the industry’s dynamics. The Product segment is dominated by Reagents & Kits due to their high replacement rate and essential role in every screening procedure. In terms of Technology, the market is shifting toward Nucleic Acid Testing (NAT) for its superior ability to detect viral presence earlier than traditional immunoassay methods. The End-User segment is primarily led by Blood Banks, which are the focal point for mandatory screening of donated blood units before clinical use.
- By Product:
- Reagents & Kits (Blood Grouping, Infectious Disease, Others)
- Instruments (Fully Automated, Semi-automated)
- Software & Services
- By Technology:
- Nucleic Acid Test (NAT) (Transcription-Mediated Amplification, Polymerase Chain Reaction)
- ELISA (Enzyme-Linked Immunosorbent Assay)
- Rapid Tests
- Next-Generation Sequencing (NGS)
- Western Blot
- By End-User:
- Blood Banks (Commercial and Public)
- Hospitals
- Reference/Diagnostic Laboratories
Regional Highlights
- North America: The largest market share holder, driven by the presence of advanced healthcare systems, high per capita healthcare spending, and stringent FDA regulations regarding blood safety.
- Europe: A significant market characterized by mature blood collection systems and early adoption of automated molecular screening platforms in countries like Germany, France, and the UK.
- Asia Pacific: The fastest-growing region, where massive population bases and expanding healthcare coverage in China and India are driving a surge in blood donation and mandatory screening protocols.
- Latin America: Showing steady growth due to increasing awareness of blood-borne diseases and government initiatives to modernize regional blood banking facilities.
- Middle East & Africa: A market with high growth potential, focused on curbing the spread of endemic infectious diseases through international collaborations and subsidized screening programs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Blood Screening Market.- Roche Diagnostics
- Abbott Laboratories
- Grifols, S.A.
- Bio-Rad Laboratories, Inc.
- Danaher Corporation (Beckman Coulter)
- Thermo Fisher Scientific Inc.
- PerkinElmer, Inc.
- Ortho Clinical Diagnostics (QuidelOrtho)
- Becton, Dickinson and Company (BD)
- DiaSorin S.p.A.
- Merck KGaA
- Siemens Healthineers
- Sysmex Corporation
- Eurofins Scientific
- Getein Biotech, Inc.
- BioMérieux SA
- Immucor, Inc.
- Trinity Biotech
- Maccura Biotechnology Co., Ltd.
- Bio-Techne
Frequently Asked Questions
What is the current market size and the projected growth of the Blood Screening Market?
The market is estimated at USD 3.15 Billion in 2025 and is projected to reach USD 6.27 Billion by 2034, growing at a CAGR of 8.3%. This growth is primarily fueled by increasing blood donations and the adoption of high-sensitivity molecular testing.
Which technology segment is expected to lead the Blood Screening Market?
Nucleic Acid Testing (NAT) is the leading technology segment. Its ability to detect infectious agents like HIV and Hepatitis at very early stages (shortening the window period) makes it the preferred choice for modern blood banks compared to traditional serology.
Who are the major players in the global blood screening industry?
The market is led by major diagnostic giants including Roche, Abbott Laboratories, Grifols, and Bio-Rad. These companies focus on continuous innovation in automation and reagents to maintain their market dominance.
What region offers the highest growth opportunities for blood screening manufacturers?
The Asia-Pacific region offers the highest growth opportunities due to rapid healthcare infrastructure development, increasing government healthcare spending, and the implementation of mandatory blood screening laws in populous nations like China and India.
What are the key challenges facing the Blood Screening Market?
Key challenges include the high cost associated with advanced automated instruments, the requirement for specialized laboratory technicians, and the logistical difficulties of maintaining reagent integrity in regions with underdeveloped cold-chain infrastructure.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
