Bioplastic Market
Bioplastic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_703091 | Published On : September 30, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Bioplastic Market Size
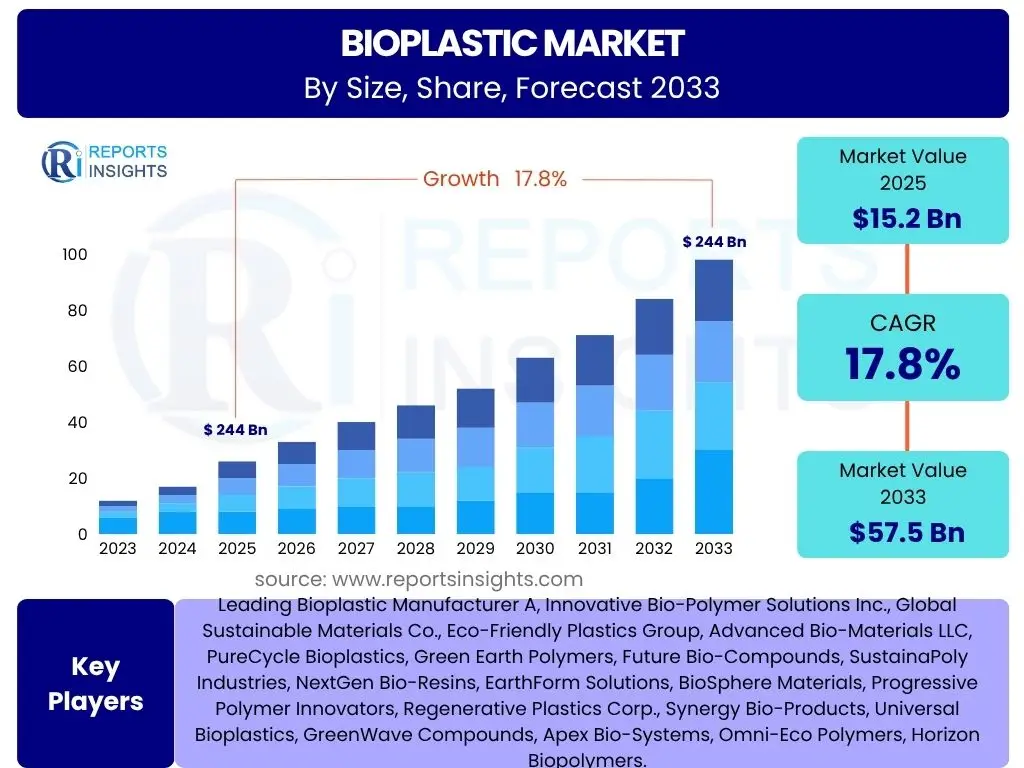
According to Reports Insights Consulting Pvt Ltd, The Bioplastic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.9% between 2026 and 2034. The market is estimated at USD 15.8 Billion in 2026 and is projected to reach USD 48.2 Billion by the end of the forecast period in 2034.
Key Bioplastic Market Trends & Insights
The global Bioplastic sector is undergoing a transformative shift driven by the transition toward a circular economy and the urgent need to decarbonize industrial value chains. Current trends indicate a significant migration from traditional petroleum-based polymers to bio-derived alternatives, propelled by stringent government regulations and shifting consumer sentiment. Stakeholders are increasingly focusing on second-generation feedstock, such as agricultural waste and non-food crops, to mitigate concerns regarding food security. Furthermore, technological advancements in polymerization processes are enhancing the mechanical and thermal properties of Bioplastic, making them suitable for high-performance applications in the automotive and electronics sectors. The market is also seeing a surge in strategic partnerships between chemical giants and biotechnology startups to scale up production capacities for Polyhydroxyalkanoates (PHA) and Polylactic Acid (PLA).
- Largest Region: Europe remains the dominant regional market, holding the largest share due to early adoption of the Plastic Tax and comprehensive frameworks such as the European Green Deal.
- Fastest Growing Region: Asia-Pacific is identified as the fastest-growing market, driven by massive manufacturing expansions in China and India, alongside emerging legislative bans on single-use plastics.
- Leading Segment by Type: Biodegradable plastics, specifically starch-based blends and PLA, currently hold the majority market share.
- Dominant Application Segment: Flexible and rigid packaging continues to be the primary application, accounting for over 60% of the total Bioplastic demand.
Key Takeaways Bioplastic Market Size & Forecast
The long-term outlook for the Bioplastic market remains highly optimistic as global brands commit to carbon neutrality and sustainable packaging targets. Analysis suggests that the integration of Bioplastic into municipal solid waste management systems—particularly industrial composting infrastructure—will be a critical factor in determining the speed of market penetration. While price parity with conventional plastics remains a challenge, the increasing scale of production and the rising cost of carbon credits are narrowing the gap. The forecast period 2025-2034 is expected to witness a diversification of the Bioplastic portfolio, with non-biodegradable bio-based plastics like Bio-PET and Bio-PE seeing steady growth in durable goods applications.
- Policy-Driven Growth: Mandatory recycled content and bio-based content requirements in the EU and North America are the primary catalysts for volume growth.
- Expansion of PHA Production: Polyhydroxyalkanoates (PHA) are expected to exhibit the highest CAGR among material types due to their marine-biodegradability and versatile properties.
- Supply Chain Localization: Countries in Southeast Asia and South America are leveraging their abundant biomass resources to establish localized bioplastic manufacturing hubs.
- Consumer Goods Integration: Leading consumer electronics and textile brands are actively replacing virgin polyester and nylon with bio-based alternatives to reduce Scope 3 emissions.
Bioplastic Market Drivers Analysis
The primary drivers for the Bioplastic market include the escalation of environmental regulations targeting single-use plastics and the collective movement toward corporate sustainability. As global carbon emission targets become more stringent, industries are compelled to seek renewable raw materials to satisfy both regulatory bodies and environmentally conscious consumers. Additionally, the volatility of crude oil prices acts as a catalyst, making bio-based alternatives more economically attractive over the long term.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory Bans on Single-Use Plastics | +4.2% | European Union, India, China | 2025-2034 |
| Corporate Sustainability Goals (Net Zero Targets) | +3.8% | Global (Multinational Corporations) | 2025-2030 |
| Advances in Bio-based Feedstock Technology | +2.5% | United States, Brazil, Thailand | 2027-2034 |
| Rising Consumer Preference for Eco-friendly Packaging | +3.1% | North America, Europe | 2025-2034 |
Bioplastic Market Restraints Analysis
Despite robust growth, the market faces significant restraints, most notably the high cost of production compared to conventional, fossil-fuel-based resins. The lack of standardized composting infrastructure in many developing regions also hinders the effective end-of-life management of biodegradable plastics, leading to contamination of existing recycling streams. Furthermore, the debate over land use for industrial crops versus food production remains a sensitive socio-economic constraint.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Price Premium Over Conventional Plastics | -3.5% | Global Markets | Short to Medium Term |
| Inadequate Composting and Recycling Infrastructure | -2.8% | Developing Economies (Africa, SE Asia) | 2025-2030 |
| Complexity in Waste Stream Separation | -1.5% | North America, Europe | Long Term |
Bioplastic Market Opportunities Analysis
The emergence of medical-grade Bioplastic for surgical implants and drug delivery systems represents a high-margin opportunity for manufacturers. Additionally, the development of bio-based engineering plastics for the automotive industry—aimed at lightweighting vehicles to improve fuel efficiency or EV range—offers a substantial untapped market. The potential for bio-based nylons and polyurethanes in the textile and footwear sectors also presents a significant growth avenue.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Medical and Healthcare Applications | +2.2% | Germany, United States, Japan | 2026-2034 |
| Automotive Lightweighting and Interior Parts | +1.9% | South Korea, Germany, China | 2025-2034 |
| Agricultural Mulch Films for Soil Health | +1.4% | India, Brazil, Australia | 2025-2030 |
Bioplastic Market Challenges Impact Analysis
Ensuring a consistent and sustainable supply of non-food feedstock is a primary challenge for the industry as it scales. There are also technical hurdles regarding the barrier properties of Bioplastic, which often require multi-layering or additives to match the performance of conventional PET or PE in food preservation. Furthermore, the varying international standards for "compostability" and "biodegradability" create confusion in cross-border trade and consumer labeling.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Feedstock Supply Chain Stability | -1.2% | Global | Medium Term |
| Performance Limitations in High-Moisture Environments | -1.8% | Tropical Regions | Short to Medium Term |
| Standardization and Certification Fragmentation | -0.9% | International Trade | 2025-2034 |
Bioplastic Market - Updated Report Scope
This report provides a granular analysis of the global Bioplastic landscape, covering material types, end-use industries, and geographic trends. It includes a detailed assessment of the competitive environment, focusing on production capacities, R&D investments, and strategic mergers. The scope encompasses both biodegradable (PLA, PHA, Starch Blends) and non-biodegradable bio-based plastics (Bio-PE, Bio-PET, Bio-PA), offering a comprehensive view of the industry's evolution through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 13.7 Billion |
| Market Forecast in 2034 | USD 48.2 Billion |
| Growth Rate | 14.9% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, NatureWorks LLC, TotalEnergies Corbion, Novamont S.p.A., Braskem, Mitsubishi Chemical Group, Biome Bioplastic, Danimer Scientific, Kaneka Corporation, FKuR Kunststoff GmbH, Arkema S.A., Yield10 Bioscience, PTT MCC Biochem, Solvay S.A., Toray Industries, Inc., Avantium, Corbion N.V., Teijin Limited. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Bioplastic market is segmented based on chemical composition and functional end-use. Currently, biodegradable plastics dominate the market volume, specifically starch blends which are widely utilized in shopping bags and agricultural films. However, the non-biodegradable bio-based segment, often referred to as "drop-in" Bioplastic, is gaining traction because these materials can be processed using existing machinery and are fully recyclable within traditional plastic streams. Packaging remains the cornerstone application, but diversification into technical textiles and automotive interiors is accelerating.
- By Type:
- Biodegradable: Polylactic Acid (PLA), Polyhydroxyalkanoates (PHA), Starch Blends, Polybutylene Adipate Terephthalate (PBAT), Polybutylene Succinate (PBS).
- Non-Biodegradable (Bio-based): Bio-Polyethylene (Bio-PE), Bio-Polyethylene Terephthalate (Bio-PET), Bio-Polyamide (Bio-PA), Bio-Polytrimethylene Terephthalate (Bio-PTT), Bio-Polypropylene (Bio-PP).
- By Application:
- Packaging: Flexible packaging, Rigid packaging (Bottles, Containers).
- Consumer Goods: Electronics, Housewares, Toys.
- Agriculture: Mulch films, Plant pots, Irrigation pipes.
- Automotive: Interior components, Under-the-hood parts.
- Textiles: Apparel, Industrial fabrics, Footwear.
- Other: Medical devices, Construction materials.
Regional Highlights
- Europe: Europe is the global leader in the Bioplastic market, underpinned by robust regulatory frameworks like the Circular Economy Action Plan. Countries such as Germany, Italy, and France are at the forefront of biodegradable plastic production and waste management innovation.
- Asia-Pacific: This region is the fastest-growing market due to massive investments in biopolymer production facilities in China and Thailand. The shift is also supported by increasing environmental awareness in India and Japan, coupled with the availability of abundant agricultural feedstock like sugarcane and cassava.
- North America: Market growth in the U.S. and Canada is driven by the expansion of the PLA sector and corporate sustainability mandates. The region is also a hub for R&D in synthetic biology and bio-based chemical engineering.
- Latin America: Brazil is a key player in the non-biodegradable bio-based market, utilizing its extensive sugarcane ethanol industry to produce Bio-Polyethylene (Bio-PE).
- Middle East & Africa: While currently a smaller share, growth is emerging in South Africa and the UAE, primarily focused on sustainable packaging solutions for the retail and export sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Bioplastic Market.- BASF SE
- NatureWorks LLC
- TotalEnergies Corbion
- Novamont S.p.A.
- Braskem
- Mitsubishi Chemical Group
- Biome Bioplastic
- Danimer Scientific
- Kaneka Corporation
- FKuR Kunststoff GmbH
- Arkema S.A.
- Yield10 Bioscience
- PTT MCC Biochem
- Solvay S.A.
- Toray Industries, Inc.
- Avantium
- Corbion N.V.
- Teijin Limited
- Futerro
- Tianan Biologic Material
Frequently Asked Questions
What is the main difference between bio-based and biodegradable plastics?
Bio-based plastics are made from renewable resources like corn or sugarcane but may not necessarily be biodegradable. Biodegradable plastics are designed to break down into water, CO2, and biomass under specific environmental conditions, regardless of whether they are bio-based or petroleum-derived.
Which industry is the largest consumer of Bioplastic?
The packaging industry is currently the largest consumer, utilizing Bioplastic for both flexible applications (such as shopping bags and films) and rigid applications (such as bottles and food containers), accounting for over 60% of global demand.
Why are Bioplastic more expensive than traditional plastics?
The higher cost is attributed to the smaller scale of production, high costs of raw materials (feedstock), and the specialized technology required for fermentation and polymerization. However, prices are expected to decrease as production scales up and technologies mature.
Can Bioplastic be recycled in standard recycling bins?
It depends on the type. Non-biodegradable bio-based plastics like Bio-PET and Bio-PE can be recycled in standard PET and PE streams. However, biodegradable plastics like PLA can contaminate traditional recycling streams and must be processed in industrial composting facilities.
What are second-generation feedstocks in Bioplastic?
Second-generation feedstocks refer to non-food sources such as agricultural residues (corn stover, wheat straw), wood waste, and dedicated energy crops. These are preferred to avoid competition with the food supply chain.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
