Biodegradable Tableware Packaging Products Market
Biodegradable Tableware Packaging Products Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711325 | Published On : October 27, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Biodegradable Tableware Packaging Products Market Size
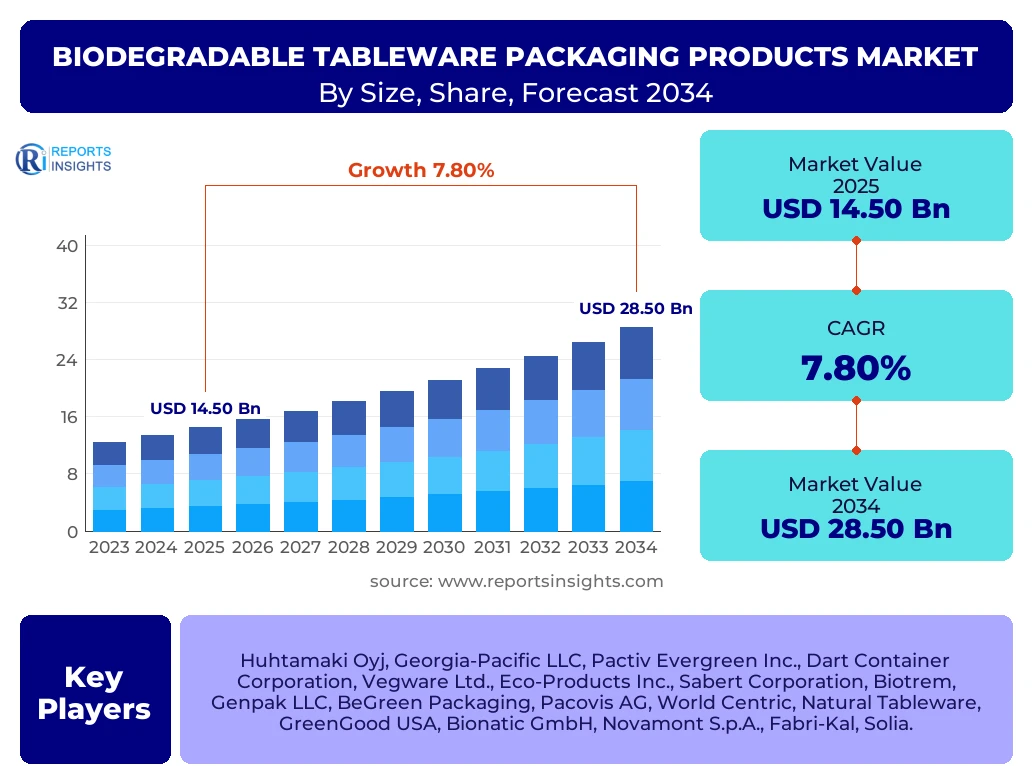
According to Reports Insights Consulting Pvt Ltd, The Biodegradable Tableware Packaging Products Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2025 and 2034. The market is estimated at USD 15.63 Billion in 2026 and is projected to reach USD 28.50 Billion by the end of the forecast period in 2034.
Key Biodegradable Tableware Packaging Products Market Trends & Insights
The global shift toward a circular economy has fundamentally altered the trajectory of the packaging industry, with biodegradable tableware emerging as a cornerstone of sustainable food service operations. Current market intelligence indicates that consumer sentiment is no longer merely "preferring" eco-friendly options but is actively demanding them, compelling Quick Service Restaurants (QSRs) and catering services to overhaul their supply chains. The integration of advanced material sciences, such as the use of agricultural waste (bagasse and wheat straw) and mushroom-based mycelium, is providing functional parity with traditional plastics. Furthermore, regional insights reveal that legislative frameworks, particularly in the European Union and parts of Asia-Pacific, are acting as primary catalysts for market expansion by mandating the phase-out of single-use plastics.
- Largest Region: Asia-Pacific currently holds the largest market share, driven by massive population centers and high street-food consumption.
- Fastest Growing Region: North America is projected to be the fastest-growing region due to rapid corporate adoption and stringent state-level environmental regulations.
- Largest Material Segment: Paper and Paperboard remain the dominant segments due to established recycling infrastructures and cost-effectiveness.
- Leading Application: The Food Service segment, including restaurants and cafes, accounts for the highest volume of consumption.
- Emerging Material: Bagasse (sugarcane fiber) is witnessing the highest growth rate among raw materials due to its superior thermal insulation and compostability.
Key Takeaways Biodegradable Tableware Packaging Products Market Size & Forecast
The convergence of regulatory pressure and corporate ESG (Environmental, Social, and Governance) goals is creating a robust environment for long-term capital investment in biodegradable manufacturing facilities. Market forecasts suggest that the proliferation of e-commerce and food delivery apps has intensified the demand for leak-proof, sturdy, yet compostable packaging solutions. Stakeholders are increasingly focusing on vertical integration to secure raw material supplies like bamboo and palm leaves, mitigating the risks of price volatility. The transition from fossil-fuel-based polymers to bio-based alternatives is not just a trend but a structural shift in the global packaging architecture, with high-performance bioplastics like PLA (Polylactic Acid) gaining traction for cold-food applications.
- China is the leading manufacturer and consumer of biodegradable tableware, benefiting from an extensive agricultural base for raw materials.
- The European Union’s Single-Use Plastics Directive serves as a blueprint for global regulatory standards, significantly boosting the demand for certified compostable products.
- The 7.8% CAGR reflects a resilient market that is less susceptible to economic downturns due to the essential nature of food packaging.
- Hybrid materials, combining paper with bio-coatings, are solving traditional moisture-barrier challenges in biodegradable packaging.
- Corporate partnerships between packaging giants and tech startups are accelerating the commercialization of seaweed-based and starch-based coatings.
Biodegradable Tableware Packaging Products Market Drivers Analysis
The primary driver for the biodegradable tableware market is the escalating global concern regarding plastic pollution in marine and terrestrial ecosystems. Governments worldwide are implementing bans or heavy taxes on conventional single-use plastics (SUPs), forcing the food service industry to adopt alternatives. This regulatory push is complemented by a significant demographic shift, as Millennial and Gen Z consumers prioritize brands that demonstrate environmental stewardship. The rise of "conscious consumerism" has made sustainability a key brand differentiator in the highly competitive food and beverage sector.
Technological advancements in manufacturing processes have also reduced the "green premium," making biodegradable options more price-competitive with traditional plastics. Automation in the molding of plant-based fibers has increased production efficiency and scale, allowing manufacturers to meet the high-volume requirements of global fast-food chains. Furthermore, the expansion of composting infrastructure in urban centers provides the necessary end-of-life pathway that validates the use of biodegradable materials, ensuring they do not end up in landfills where their environmental benefits would be minimized.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bans on Single-Use Plastics | +2.5% | European Union, India, Canada | Short to Medium Term |
| Consumer Preference for Eco-friendly Products | +1.8% | Global (North America/Europe) | Long Term |
| Growth in Online Food Delivery Services | +2.0% | China, USA, Southeast Asia | Medium Term |
| Advancements in Material Science | +1.5% | Germany, Japan, USA | Ongoing |
Biodegradable Tableware Packaging Products Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant restraints, primarily centered around the cost of raw materials. Bio-based polymers and specialized plant fibers are often more expensive to harvest and process than petroleum-based resins, leading to higher unit costs for the end-consumer. For small-scale food vendors and businesses in developing economies with thin profit margins, this price disparity remains a formidable barrier to adoption. The volatility of agricultural commodity prices also introduces unpredictability into the manufacturing cost structure.
Another major restraint is the performance limitation of certain biodegradable materials. While paper and bagasse are excellent for dry goods, they often struggle with high-temperature liquids or acidic foods without the use of synthetic liners, which can sometimes compromise their compostability status. Additionally, the lack of standardized industrial composting facilities in many regions means that "biodegradable" products often end up in general waste streams, leading to consumer skepticism and "greenwashing" allegations that can hinder brand trust and market maturity.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Raw Material and Production Costs | -1.2% | Emerging Markets (LATAM, Africa) | Short to Medium Term |
| Performance and Durability Issues | -0.8% | Global | Ongoing |
| Inadequate Composting Infrastructure | -1.0% | USA, Southeast Asia | Medium to Long Term |
Biodegradable Tableware Packaging Products Market Opportunities Analysis
The market presents substantial opportunities in the development of customized, brand-specific biodegradable packaging. As premium food brands look to enhance the "unboxing experience," there is a growing niche for aesthetically pleasing, high-quality biodegradable tableware that offers a tactile sense of luxury while remaining eco-friendly. Innovations in 3D printing and precision molding allow for complex geometries and textures that were previously unattainable with plant fibers. This opens doors in the hospitality and high-end catering segments where presentation is as critical as functionality.
Furthermore, the integration of "smart packaging" technologies into biodegradable materials represents a significant frontier. Developing sensors that can monitor food freshness or temperature, integrated directly into compostable trays or containers, provides a dual value proposition of food safety and sustainability. Expansion into untapped markets in the Middle East and Africa, where urbanization is accelerating and environmental awareness is rising, offers a first-mover advantage for manufacturers willing to localize production and utilize indigenous non-wood fibers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Smart/Active Packaging | +1.4% | Japan, South Korea, USA | Long Term |
| Expansion into Premium Catering & Hospitality | +1.2% | GCC Countries, Western Europe | Medium Term |
| Utilization of Agricultural Residues (Upcycling) | +1.6% | India, Brazil, Southeast Asia | Short to Medium Term |
Biodegradable Tableware Packaging Products Market Challenges Impact Analysis
The most pressing challenge in the biodegradable tableware market is the lack of global harmonization in certification standards. Different regions have varying definitions of "compostable" vs. "biodegradable," which creates confusion for multinational corporations and leads to trade barriers. For instance, a product certified for industrial composting in Europe might not meet the standards for home composting in the United States, complicating marketing and distribution strategies. This regulatory fragmentation increases the compliance burden on manufacturers and can delay the introduction of new products.
Supply chain vulnerability is another critical challenge. The reliance on specific agricultural crops, such as corn for PLA or sugarcane for bagasse, makes the industry susceptible to climate-change-induced crop failures and shifts in land-use policies. As the demand for biofuels and bio-based plastics increases, there is also an ethical challenge regarding "food vs. packaging," where land used for packaging materials might compete with land needed for food production. Navigating these ethical and environmental trade-offs requires sophisticated sustainability auditing and transparent sourcing practices.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Regulatory Fragmentation and Labeling Issues | -0.9% | Global Trade | Medium Term |
| Supply Chain Disruptions (Agricultural Volatility) | -1.1% | Global | Ongoing |
| Competition from Traditional Plastic Recycling | -0.7% | North America, Europe | Short Term |
Biodegradable Tableware Packaging Products Market - Updated Report Scope
This report provides a granular analysis of the global biodegradable tableware packaging industry, encompassing a multi-dimensional view of material types, product categories, and end-user segments. The scope includes historical data analysis from 2020 to 2024, a current assessment of the 2025 landscape, and a strategic forecast extending to 2034. The research methodology integrates primary insights from industry experts with secondary data from trade associations and governmental environmental agencies to ensure a high level of accuracy and practical utility for stakeholders.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 14.50 Billion |
| Market Forecast in 2034 | USD 28.50 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 245 Pages |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Huhtamaki Oyj, Georgia-Pacific LLC, Pactiv Evergreen Inc., Dart Container Corporation, Vegware Ltd., Eco-Products Inc., Sabert Corporation, Biotrem, Genpak LLC, BeGreen Packaging, Pacovis AG, World Centric, Natural Tableware, GreenGood USA, Bionatic GmbH, Novamont S.p.A., Fabri-Kal, Solia. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is intricately segmented to reflect the diverse applications and material preferences across different geographies. The Product Type segment is led by plates and cups, which together account for a significant portion of the total volume due to their ubiquity in the food service industry. In terms of Material, Paper and Paperboard dominate the market owing to their lightweight nature and mature recycling streams. However, the Bagasse segment is experiencing the fastest growth as it provides superior grease resistance and thermal stability compared to untreated paper. The End-User segmentation shows that while the Household segment is growing, the Food Service sector remains the primary engine of demand, particularly with the global explosion of delivery platforms.
- By Product Type:
- Plates (Round, Square, Compartmental)
- Bowls (Soup bowls, Serving bowls)
- Cups (Cold drink cups, Hot drink cups)
- Cutlery (Spoons, Forks, Knives, Sporks)
- Trays & Clamshells (Takeaway containers)
- By Material Type:
- Paper & Paperboard (Coated and Uncoated)
- Bagasse (Sugarcane Fiber)
- Bamboo (Pulp and Solid Wood)
- Polylactic Acid (PLA) (Corn-based bioplastic)
- Wood (Birch, Pine)
- Others (Palm Leaf, Wheat Straw, Seaweed)
- By End-User Application:
- Food Service (Fast Food, Fine Dining, Catering)
- Institutional (Schools, Corporate Offices, Hospitals)
- Household (Consumer Retail)
Regional Highlights
Regional dynamics are heavily influenced by the interplay of legislative mandates and consumer purchasing power. Asia-Pacific remains the largest market, accounting for approximately 40% of global demand, primarily due to the vast manufacturing base in China and the rapid phase-out of plastic across Southeast Asian nations. North America, specifically the United States and Canada, is witnessing a surge in demand driven by corporate sustainability pledges and municipal bans on expanded polystyrene (Styrofoam). Europe remains the most regulated market, where the "compostable" standard is the most rigorous, leading to high innovation in material coatings. Latin America and the MEA region are considered emerging frontiers, where market growth is tied to the expansion of tourism and international fast-food chains.
- Asia-Pacific: Largest market share; dominant in bamboo and bagasse production; high growth in India and China.
- North America: Fastest CAGR; driven by technological innovation and venture capital investment in bio-based startups.
- Europe: Focus on high-quality certification and circular economy models; highest adoption of PLA and bio-coatings.
- Middle East & Africa: Growing hospitality sector and tourism-driven demand for eco-friendly luxury packaging.
- Latin America: Increasing government focus on marine conservation, particularly in coastal regions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Biodegradable Tableware Packaging Products Market.- Huhtamaki Oyj
- Georgia-Pacific LLC
- Pactiv Evergreen Inc.
- Dart Container Corporation
- Vegware Ltd.
- Eco-Products Inc.
- Sabert Corporation
- Biotrem
- Genpak LLC
- BeGreen Packaging
- Pacovis AG
- World Centric
- Natural Tableware
- GreenGood USA
- Bionatic GmbH
- Novamont S.p.A.
- Fabri-Kal
- Solia
- Better All-Round
- Green Olive Environmental Technology
Frequently Asked Questions
What is the primary difference between biodegradable and compostable tableware?
Biodegradable tableware breaks down through natural processes, but may take a long time and leave residues. Compostable tableware is a subset that must break down under specific conditions (usually industrial) into nutrient-rich organic matter within a set timeframe without leaving toxic residues.
Which material is currently leading the biodegradable tableware market?
Paper and Paperboard are the leading materials due to their availability and cost. However, Bagasse (sugarcane fiber) is the fastest-growing material segment because of its excellent functional properties for hot and oily foods.
How are government regulations impacting the market forecast?
Regulations such as the EU Single-Use Plastics Directive and bans in countries like India and Canada are major drivers, contributing significantly to the projected 7.8% CAGR by forcing industries to switch from plastic to sustainable alternatives.
Can biodegradable tableware be used for hot liquids?
Yes, but it depends on the material and coating. Bagasse and specialized treated paper can handle high temperatures, whereas some PLA (bioplastic) products may soften or deform if the liquid exceeds 40-50 degrees Celsius.
Is the market for biodegradable tableware more expensive than traditional plastic?
Currently, biodegradable options carry a price premium of 10% to 30% over traditional plastics. However, as production scales and technology improves, this price gap is narrowing, making it more accessible for high-volume users.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
