Bioadhesives Wound Care Market
Bioadhesives Wound Care Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711868 | Published On : November 19, 2026 |
Format : 


 | Author : Erika Grotto
Bioadhesives Wound Care Market Size
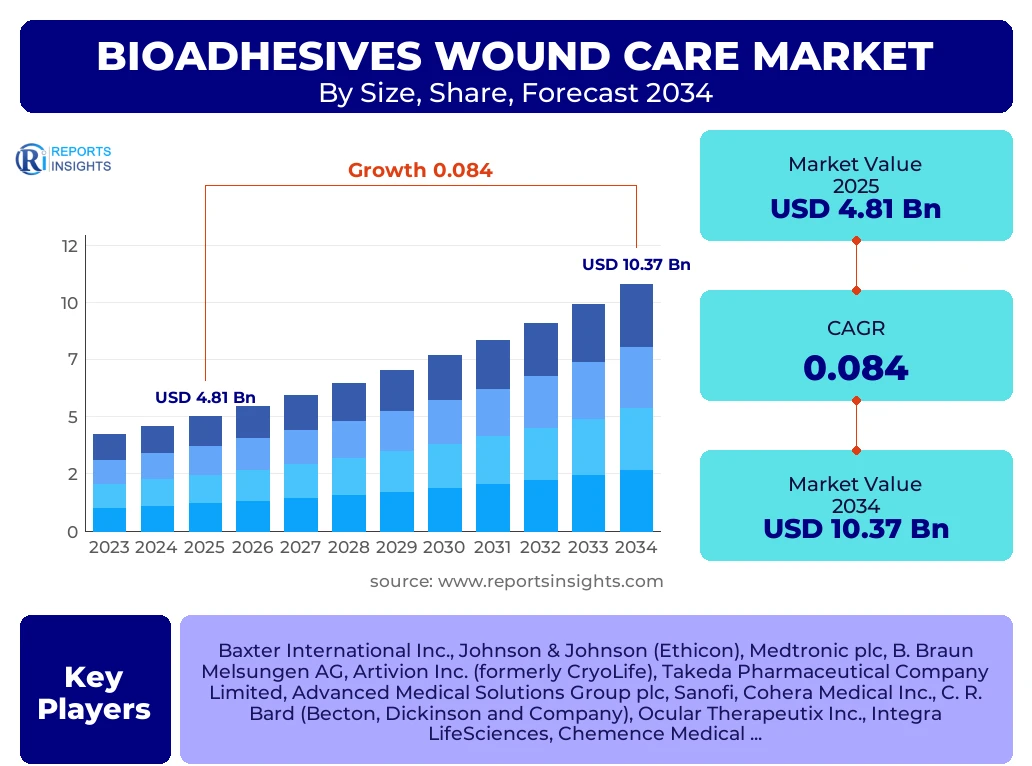
According to Reports Insights Consulting Pvt Ltd, The Bioadhesives Wound Care Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 5.21 Billion in 2026 and is projected to reach USD 10.37 Billion by the end of the forecast period in 2034.
Key Bioadhesives Wound Care Market Trends & Insights
The global bioadhesives wound care sector is undergoing a transformative phase driven by the convergence of biotechnology and surgical precision. Current market trends indicate a significant shift from traditional mechanical wound closure methods, such as sutures and staples, toward biological sealants that offer superior hemostatic properties and reduced risk of post-operative complications. Analysts have observed that the demand is increasingly centered on biomimetic materials that not only close wounds but also actively participate in the tissue regeneration process. Innovations in protein-engineered adhesives and polysaccharide-based glues are providing surgeons with tools that work effectively in moist physiological environments, which has historically been a challenge for synthetic adhesives. Furthermore, the integration of drug-delivery mechanisms within bioadhesive matrices is emerging as a critical trend, allowing for the localized release of antibiotics or growth factors directly at the wound site, thereby enhancing the overall clinical outcome and reducing hospital stay durations.
- Largest Region: North America currently holds the largest market share, driven by advanced healthcare infrastructure and high adoption rates of minimally invasive surgical procedures.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to expanding medical tourism, increasing geriatric populations, and significant investments in healthcare modernization in China and India.
- Largest Segment by Type: Fibrin-based bioadhesives remain the dominant segment in terms of revenue share, valued for their excellent biocompatibility and long-standing clinical track record.
- Largest Segment by Application: Surgical wound care represents the largest application area, particularly in cardiovascular and orthopedic surgeries where rapid hemostasis is vital.
Key Takeaways Bioadhesives Wound Care Market Size & Forecast
The long-term outlook for the bioadhesives wound care market remains highly bullish as healthcare providers prioritize patient comfort and infection control. The transition toward value-based care models is encouraging the use of high-performance bioadhesives that minimize the need for secondary procedures and reduce the incidence of surgical site infections (SSIs). Stakeholders are increasingly focusing on the development of "smart" adhesives that can respond to environmental stimuli or provide visual cues regarding the healing progress. As regulatory pathways for biological products become more defined, the market is expected to see a surge in specialized products tailored for specific anatomical sites, such as pulmonary sealants or dural adhesives. The forecast period anticipates a move toward hybrid formulations that combine the strength of synthetic polymers with the biological integration of natural proteins, bridging the gap between mechanical durability and physiological harmony.
- The global market is anticipated to double in value by 2034, reflecting the rising incidence of chronic wounds and surgical interventions worldwide.
- United States is the leading country in market value, supported by extensive R&D activities and the presence of major medical device manufacturers.
- Chronic wound management, including diabetic foot ulcers and pressure sores, is becoming a primary growth lever for bioadhesive adoption in outpatient settings.
- Technological advancements in cyanoacrylates and albumin-glutaraldehyde glues are expanding the scope of bioadhesives in trauma and emergency medicine.
- Sustainability is becoming a factor, with manufacturers exploring plant-derived bioadhesives to reduce the carbon footprint of medical waste.
Bioadhesives Wound Care Market Drivers Analysis
The primary driver for the bioadhesives wound care market is the global rise in surgical volumes, particularly minimally invasive surgeries (MIS). These procedures require precise, easy-to-apply closure methods that can operate within tight anatomical spaces where traditional suturing is difficult. Additionally, the increasing prevalence of chronic conditions like diabetes and obesity is leading to a higher incidence of non-healing wounds, which benefit significantly from the protective and healing-promotive properties of bioadhesives. The aging global population also contributes to market growth, as older patients often have fragile skin that is easily damaged by mechanical fasteners, making gentle biological adhesives the preferred clinical choice.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Minimally Invasive Surgeries (MIS) | +2.3% | Global (Strongest in North America & Europe) | 2025 - 2034 |
| Rising Geriatric Population & Chronic Wounds | +1.9% | Japan, Germany, United States | 2025 - 2034 |
| Technological Advancement in Hemostatic Agents | +1.5% | United States, Israel, Germany | 2026 - 2030 |
| Shift from Sutures to Sealants for Infection Control | +1.2% | United Kingdom, France, China | 2025 - 2034 |
Bioadhesives Wound Care Market Restraints Analysis
Despite the clinical benefits, the high cost of biological adhesives compared to traditional tapes, sutures, and staples remains a significant barrier, particularly in price-sensitive emerging markets. Many bioadhesives require specialized storage conditions, such as refrigeration or deep-freezing, which complicates the supply chain and increases the total cost of ownership for hospitals. Furthermore, the stringent and lengthy regulatory approval processes for biological products can delay the entry of innovative products into the market, limiting the options available to clinicians in certain jurisdictions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Biologics | -1.4% | India, Brazil, Southeast Asia | 2025 - 2034 |
| Complex Storage and Logistics Requirements | -0.8% | Africa, Latin America | 2025 - 2028 |
| Stringent Regulatory Approval Frameworks | -1.1% | European Union (MDR), United States (FDA) | 2025 - 2034 |
Bioadhesives Wound Care Market Opportunities Analysis
The expansion of healthcare infrastructure in developing economies presents a massive untapped opportunity for market participants. As middle-income populations grow in regions like Southeast Asia and Latin America, the demand for advanced surgical treatments is rising. There is also a significant opportunity in the development of bioadhesives for specialized applications, such as internal tissue sealing in neurosurgery or ophthalmic procedures. Furthermore, the rise of home healthcare and self-care models opens the door for easy-to-use, over-the-counter bioadhesive products for minor wound management, moving beyond the traditional hospital setting.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion in Emerging Healthcare Markets | +2.1% | China, India, Indonesia | 2027 - 2034 |
| Development of Bio-resorbable Internal Sealants | +1.8% | Germany, United States, Japan | 2026 - 2032 |
| Rise of Outpatient Surgery Centers | +1.4% | United States, Australia | 2025 - 2034 |
Bioadhesives Wound Care Market Challenges Impact Analysis
One of the persistent challenges in this market is the potential for adverse biological reactions or hypersensitivity to certain protein-based components, such as bovine thrombin or human fibrinogen. Ensuring the purity and safety of these biological materials is paramount but challenging. Additionally, the presence of strong competition from advanced synthetic sealants, which are often cheaper and easier to store, forces manufacturers of true bioadhesives to continuously prove their superior clinical value through expensive and time-consuming clinical trials.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Risk of Immunogenic Reactions | -0.9% | Global | Ongoing |
| Competition from Synthetic Alternatives | -1.2% | Global | 2025 - 2034 |
| Evidence-Based Clinical Data Requirements | -0.7% | Europe, North America | 2025 - 2030 |
Bioadhesives Wound Care Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the bioadhesives wound care market, encompassing biological glues, sealants, and hemostatic agents used across various clinical settings. The scope includes an evaluation of different material sources, ranging from human and animal-derived proteins to plant-based and marine-inspired polymers. It covers the full spectrum of applications, including surgical closure, trauma management, and chronic wound healing. The report further examines the competitive landscape, regulatory environment, and the impact of macro-economic factors on market dynamics across six major geographical regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.81 Billion |
| Market Forecast in 2034 | USD 10.37 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Baxter International Inc., Johnson & Johnson (Ethicon), Medtronic plc, B. Braun Melsungen AG, Artivion Inc. (formerly CryoLife), Takeda Pharmaceutical Company Limited, Advanced Medical Solutions Group plc, Sanofi, Cohera Medical Inc., C. R. Bard (Becton, Dickinson and Company), Ocular Therapeutix Inc., Integra LifeSciences, Chemence Medical, Vivostat A/S, Sealantis (Stryker), LifeBond, Adhesys Medical |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The bioadhesives wound care market is intricately segmented to reflect the diverse clinical needs and technological variations within the industry. By product type, the market is categorized into several biological categories, with fibrin sealants holding the lead due to their dual function as both an adhesive and a hemostatic agent. Gelatin and collagen-based products are also significant, often utilized in sponge or matrix formats for broad-surface wound management. Chitosan-based adhesives are gaining traction in emergency and military medicine due to their rapid clotting capabilities and natural antimicrobial properties. The application segment is dominated by surgical wounds, particularly in high-stakes environments like cardiac or neurosurgery where blood loss must be minimized instantaneously. However, the chronic wound segment is the fastest-growing application area, fueled by the global epidemic of metabolic diseases which necessitates long-term, biocompatible wound management solutions that traditional adhesives cannot provide.
- By Product Type
- Fibrin Sealants: Derived from human or animal plasma, used widely for hemostasis.
- Gelatin-based Adhesives: Often used as topical sealants or in combination with other agents.
- Chitosan-based Adhesives: Valued for biocompatibility and inherent antibacterial effects.
- Albumin-Glutaraldehyde: Known for high bond strength in vascular and pulmonary repairs.
- Collagen-based Adhesives: Primarily used for structural support and promoting tissue growth.
- By Application
- Surgical Wounds: Including Cardiovascular, Orthopedic, Neurological, and Plastic Surgery.
- Traumatic Wounds: Focused on emergency closure and rapid hemostasis in field conditions.
- Chronic Wounds: Including Diabetic Foot Ulcers (DFUs), Pressure Ulcers, and Venous Leg Ulcers.
- By End-User
- Hospitals: The primary setting for surgical applications and acute care.
- Ambulatory Surgical Centers (ASCs): Growing segment due to the rise of outpatient procedures.
- Specialty Clinics: Focused on dermatology and wound care management.
- Home Healthcare: Emerging segment for chronic wound maintenance and post-operative recovery.
Regional Highlights
North America remains the cornerstone of the bioadhesives wound care market, accounting for nearly 40% of the global share. This dominance is attributed to a sophisticated medical device ecosystem, high healthcare expenditure, and a regulatory environment that encourages the development of advanced biologics. The United States is the primary contributor, where the high volume of orthopedic and cardiovascular surgeries sustains a constant demand for high-end sealants. In Europe, Germany and the UK are the market leaders, with a strong emphasis on clinical research and the adoption of "green" medical technologies. The European market is also characterized by a stringent but clear regulatory pathway through the Medical Device Regulation (MDR), which ensures high product safety and efficacy standards.
The Asia-Pacific region is the most dynamic, projected to grow at a CAGR exceeding 10% during the forecast period. The primary drivers are the massive population bases in China and India, where increasing healthcare access and an expanding middle class are leading to higher rates of surgical intervention. Furthermore, Japan is a critical market in this region due to its exceptionally high geriatric population, which requires advanced wound care for age-related skin conditions and surgeries. Latin America and the Middle East are also showing promise, particularly in the trauma and emergency care segments, as these regions invest in better emergency response infrastructure and specialized surgical centers.
- North America: Largest market value, centered on the US and Canada; high adoption of innovative fibrin and albumin-based glues.
- Europe: Mature market with a focus on cost-effectiveness and high safety standards; Germany is the regional hub for biotech medical manufacturing.
- Asia-Pacific: Fastest growing region; driven by medical tourism in Thailand and India, and large-scale healthcare reforms in China.
- Latin America: Growth focused on Brazil and Mexico, particularly in the trauma and cosmetic surgery segments.
- Middle East & Africa: Steady growth in the GCC countries due to modernization of hospitals and rising prevalence of lifestyle diseases.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Bioadhesives Wound Care Market.- Baxter International Inc.
- Johnson & Johnson (Ethicon)
- Medtronic plc
- B. Braun Melsungen AG
- Artivion Inc.
- Takeda Pharmaceutical Company Limited
- Advanced Medical Solutions Group plc
- Sanofi
- Integra LifeSciences
- Becton, Dickinson and Company (C. R. Bard)
- Ocular Therapeutix Inc.
- Cohera Medical Inc.
- Vivostat A/S
- Chemence Medical
- Stryker (Sealantis)
- LifeBond
- Adhesys Medical
- TissueGen Inc.
- Polyganics
- Betaglue Technologies
Frequently Asked Questions
What exactly are bioadhesives in the context of wound care?
Bioadhesives in wound care are biologically derived or biomimetic substances used to adhere tissues together or seal wounds. Unlike synthetic glues, they are typically made from proteins like fibrin, albumin, or gelatin, or polysaccharides like chitosan. They are designed to be biocompatible, often biodegradable, and frequently assist in the natural healing process by promoting hemostasis and providing a scaffold for cell growth.
Why are bioadhesives preferred over traditional sutures in some surgeries?
Bioadhesives offer several advantages over sutures, including the ability to create an airtight and watertight seal, which is critical in pulmonary and vascular surgeries. They reduce the "cheese-wire" effect on fragile tissues, decrease the time spent in the operating room, lower the risk of needle-stick injuries, and minimize the entry points for bacteria, thereby reducing the risk of surgical site infections.
What is the primary factor driving the growth of the bioadhesives wound care market?
The primary growth driver is the global increase in surgical procedures, particularly minimally invasive surgeries (MIS). Additionally, the rising prevalence of chronic wounds caused by diabetes and an aging population, which require more advanced and gentler healing solutions than traditional mechanical closure methods, is significantly boosting market demand.
Are there any major risks associated with using bioadhesives?
The main risks include potential allergic or immunogenic reactions, especially if the bioadhesive is derived from animal (bovine or porcine) sources. There is also a risk of viral transmission with human-derived products, though modern sterilization and screening techniques have made this extremely rare. Additionally, some bioadhesives may have lower mechanical strength compared to synthetic glues or staples in high-tension areas.
Which region is expected to see the most significant growth in the coming years?
The Asia-Pacific region is expected to see the most significant growth. This is due to a combination of factors including rapid healthcare infrastructure development, a growing elderly population in countries like Japan and China, increasing medical tourism, and a shift toward modern surgical techniques across the region.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
