Beverage Cups Lids Market
Beverage Cups Lids Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710971 | Published On : September 24, 2026 |
Format : 


 | Author : Hameer Thakur
Beverage Cups Lids Market Size
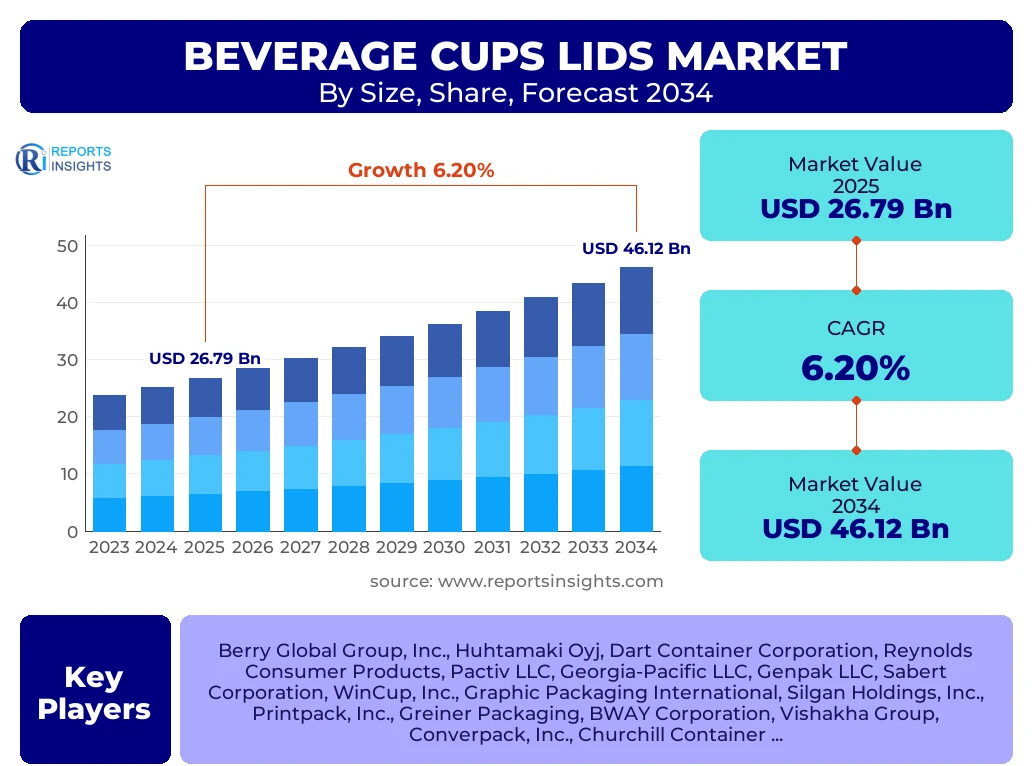
According to Reports Insights Consulting Pvt Ltd, The Beverage Cups Lids Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2026 and 2034. The market is estimated at USD 28.45 Billion in 2026 and is projected to reach USD 46.12 Billion by the end of the forecast period in 2034.
The beverage cups and lids market is experiencing a transformative phase driven by the global expansion of the quick-service restaurant (QSR) sector and the burgeoning coffee shop culture across emerging economies. As consumer lifestyles become increasingly mobile, the demand for portable, spill-proof, and temperature-retaining packaging solutions has surged. This market encompasses a wide array of materials, including traditional plastics, paperboard, and increasingly, bio-based alternatives designed to meet stringent environmental regulations. The integration of advanced manufacturing technologies has enabled producers to develop lids with enhanced ergonomic features and cups with superior insulation properties, thereby improving the overall consumer experience. Strategic shifts toward circular economy models are also prompting market leaders to invest heavily in recyclable and compostable material science.
Technological innovations in the production process, such as thermoforming and injection molding, have allowed for high-volume manufacturing while maintaining cost-efficiency and product consistency. The market is also benefiting from the rapid growth of the online food delivery ecosystem, which necessitates robust and secure packaging to ensure product integrity during transit. Furthermore, the rise of specialty beverages, including craft sodas, bubble teas, and premium coffee blends, has created a niche for customized and branded beverage containers. These factors, combined with increasing disposable incomes and urban populations, are expected to sustain the upward trajectory of the global market through 2034.
Key Beverage Cups Lids Market Trends & Insights
The global landscape for beverage cups and lids is currently defined by a dual focus on sustainability and functional innovation. Market participants are increasingly analyzing regional legislative trends, such as the European Union Single-Use Plastics Directive, which has accelerated the transition from conventional polystyrene to paper and plant-based polymers. Competitive benchmarking reveals that industry leaders are prioritizing vertical integration to secure raw material supplies and mitigate the impact of fluctuating commodity prices. Insights into consumer behavior suggest a high preference for convenience features, such as sip-hole designs that prevent splashing and lids that accommodate various straw sizes. Additionally, the adoption of smart packaging, featuring QR codes for brand engagement and traceability, is emerging as a significant trend in the premium beverage segment.
- Largest Region: North America remains the largest market due to high per capita beverage consumption and a mature food service infrastructure.
- Fastest Growing Region: Asia Pacific is the fastest-growing region, fueled by rapid urbanization in China, India, and Southeast Asia.
- Largest Material Segment: Paper and Paperboard segments currently hold a significant share as brands pivot away from single-use plastics.
- Leading End-User: The Foodservice segment, including cafes and QSRs, represents the primary driver of volume demand.
- Dominant Product Type: Standard lids with ergonomic sip-holes dominate the market share owing to their universal application in hot and cold beverages.
Key Takeaways Beverage Cups Lids Market Size & Forecast
Market forecasts indicate a robust expansion driven by the synergistic relationship between the beverage industry and the packaging sector. Stakeholders are increasingly concerned with the lifecycle analysis of packaging materials, leading to a surge in demand for FSC-certified paper and PLA-based plastics. The forecast period is expected to see a significant shift in market share from developed regions to developing nations as global franchise chains expand their footprints. Analysts highlight that the convergence of aesthetic design and functional reliability is the primary differentiator for brands seeking to capture market share in a fragmented competitive landscape. The market size expansion is also supported by the diversification of beverage offerings, which requires specialized lid designs for carbonated and non-carbonated drinks.
- Market Valuation: The total market value is expected to cross the 40 billion USD threshold by 2032, reflecting consistent investment in packaging infrastructure.
- Sustainability Pivot: Over 40 percent of new product launches are expected to feature eco-friendly or biodegradable claims by 2028.
- Regional Dominance: The United States and China are the primary revenue contributors, collectively accounting for a substantial portion of global demand.
- Material Innovation: High-density polyethylene (HDPE) and polypropylene (PP) are replacing traditional polystyrene (PS) in many jurisdictions due to better recyclability.
- Consumer Preferences: On-the-go consumption habits are the single most influential factor driving the demand for high-performance spill-resistant lids.
Beverage Cups Lids Market Drivers Analysis
The primary growth engines for the beverage cups and lids market include the escalating global demand for convenience-based consumption and the expansion of the organized retail and food service sectors. The rise of coffee culture, characterized by the proliferation of both international chains and independent specialty cafes, has created a consistent and growing need for high-quality disposable containers. Furthermore, the integration of third-party delivery apps has extended the reach of food service providers, mandating high-performance packaging that ensures temperature maintenance and prevents leakage during long-distance delivery cycles.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Quick Service Restaurants (QSRs) | +1.8% | Global (High in APAC and Latin America) | 2025 - 2034 |
| Rise of Specialty Coffee and Tea Culture | +1.5% | North America and Europe | 2025 - 2030 |
| Growth of Online Food and Beverage Delivery | +1.2% | Global (Urban Centers) | 2026 - 2034 |
| Increasing Consumer Disposable Income | +0.9% | Emerging Economies (India, Brazil, Vietnam) | 2025 - 2034 |
Beverage Cups Lids Market Restraints Analysis
The market faces significant headwinds from increasingly stringent environmental regulations targeting single-use plastics. Many governments are implementing bans or high taxes on non-recyclable materials, forcing manufacturers to overhaul their production lines at considerable cost. Additionally, the volatility in raw material prices, particularly for petroleum-based polymers and high-grade paper pulp, creates pricing pressures that can impact profit margins for both manufacturers and end-users.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Single-Use Plastic Bans | -1.4% | European Union, Canada, Australia | 2025 - 2034 |
| Raw Material Price Volatility | -0.8% | Global | Ongoing |
| Supply Chain Disruptions | -0.5% | Global | 2025 - 2027 |
Beverage Cups Lids Market Opportunities Analysis
The ongoing shift toward environmental stewardship presents a massive opportunity for innovation in compostable and bio-based materials. Companies that can develop cost-effective, durable, and truly biodegradable cups and lids stand to gain significant market share among eco-conscious brands and consumers. Furthermore, there is a growing market for customized and personalized packaging, allowing beverage brands to use cups as a primary marketing tool through high-quality digital printing and unique structural designs.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of 100% Compostable Materials | +2.1% | Western Europe and North America | 2026 - 2034 |
| Technological Integration (Smart Packaging) | +0.7% | Developed Markets | 2027 - 2034 |
| Emerging Market Expansion | +1.4% | Southeast Asia and Africa | 2025 - 2034 |
Beverage Cups Lids Market Challenges Impact Analysis
One of the primary challenges in the beverage cups and lids market is the lack of standardized recycling infrastructure across different regions, which complicates the end-of-life management of packaging products. Even when materials are technically recyclable, low collection rates and contamination often result in them being sent to landfills. Additionally, balancing the cost of sustainable materials with the price sensitivity of the food service industry remains a persistent hurdle for material scientists and manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inadequate Recycling Infrastructure | -0.9% | Developing Regions | 2025 - 2034 |
| High Cost of Alternative Materials | -0.7% | Global | Short to Medium Term |
| Consumer Misinformation on Disposal | -0.4% | Global | Ongoing |
Beverage Cups Lids Market - Updated Report Scope
This report provides a comprehensive analysis of the global beverage cups and lids market, covering various material types, product categories, and end-user segments across six major geographic regions. It utilizes a robust methodology combining primary and secondary research to deliver accurate market valuations, trend assessments, and competitive intelligence for strategic decision-making.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 26.79 Billion |
| Market Forecast in 2034 | USD 46.12 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 258 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Berry Global Group, Inc., Huhtamaki Oyj, Dart Container Corporation, Reynolds Consumer Products, Pactiv LLC, Georgia-Pacific LLC, Genpak LLC, Sabert Corporation, WinCup, Inc., Graphic Packaging International, Silgan Holdings, Inc., Printpack, Inc., Greiner Packaging, BWAY Corporation, Vishakha Group, Converpack, Inc., Churchill Container, Lollicup USA, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The beverage cups and lids market is segmented based on material, product type, application, and end-user, allowing for a granular understanding of the growth drivers within each category. The material segment is witnessing a significant pivot, with paper and bio-plastics gaining ground over traditional polymers due to regulatory pressure. Product-wise, the demand for specialized lids that offer convenience and safety is outpacing standard designs, particularly in the hot beverage segment. Application-based analysis shows that the tea and coffee segment remains the largest consumer, while the fruit juice and soft drink categories are driving innovations in cold-beverage packaging.
- By Material:
- Plastic (Polypropylene, Polyethylene Terephthalate, Polystyrene)
- Paper and Paperboard (Single-wall, Double-wall, Ripple-wall)
- Bio-plastics (Polylactic Acid, Polyhydroxyalkanoates)
- Others (Metal, Glass)
- By Product:
- Beverage Cups (Insulated, Non-insulated)
- Lids (Plug-fit, Snap-on, Over-cap, Strawless)
- By Application:
- Tea and Coffee
- Carbonated Soft Drinks
- Fruit Juices and Smoothies
- Alcoholic Beverages
- Dairy-based Drinks
- By End-User:
- Foodservice (Quick Service Restaurants, Cafes, Restaurants)
- Institutional (Offices, Hospitals, Educational Institutes)
- Residential/Household
Regional Highlights
- North America: The largest market globally, characterized by a high volume of coffee consumption and the presence of major global QSR chains. The region is seeing a rapid transition toward recyclable lids and sustainable fiber cups.
- Europe: A leader in regulatory standards, with strict single-use plastic bans driving the highest regional growth for bio-based and paper materials. Key countries include Germany, France, and the UK.
- Asia Pacific: The fastest-growing region due to massive urbanization, a rising middle class, and the expansion of western-style cafes in China and India. Local manufacturers are scaling production to meet both domestic and export demand.
- Latin America: Showing steady growth driven by the expansion of local food service franchises and an increasing preference for convenient packaging in urban centers like Sao Paulo and Mexico City.
- Middle East and Africa: Growth is primarily driven by the hospitality and tourism sectors, alongside an increasing number of international beverage brands entering the GCC countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Beverage Cups Lids Market.- Berry Global Group, Inc.
- Huhtamaki Oyj
- Dart Container Corporation
- Reynolds Consumer Products
- Pactiv LLC
- Georgia-Pacific LLC
- Genpak LLC
- Sabert Corporation
- WinCup, Inc.
- Graphic Packaging International
- Silgan Holdings, Inc.
- Printpack, Inc.
- Greiner Packaging
- BWAY Corporation
- Vishakha Group
- Converpack, Inc.
- Churchill Container
- Lollicup USA, Inc.
- Benders Paper Cups
- F Bender Limited
Frequently Asked Questions
What is the current market size and future growth projection for the Beverage Cups Lids market?
The Beverage Cups Lids Market is estimated at USD 28.45 Billion in 2026 and is projected to reach USD 46.12 Billion by 2034, growing at a CAGR of 6.2% during the forecast period.
Which material segment is expected to dominate the market by 2034?
While plastics like PP and PET remain widely used, the Paper and Paperboard segment, along with Bio-plastics (PLA), is expected to see the highest growth due to global sustainability regulations and consumer preference for eco-friendly packaging.
What are the primary drivers of growth in the Asia Pacific region?
Growth in the Asia Pacific region is primarily driven by rapid urbanization, increasing disposable incomes, and the massive expansion of the quick-service restaurant (QSR) sector in countries like China, India, and Indonesia.
How are environmental regulations impacting the beverage packaging industry?
Stringent regulations, such as the EU Single-Use Plastics Directive, are forcing a shift away from traditional polystyrene (PS) toward more recyclable or compostable alternatives, prompting significant investment in R&D and supply chain adjustments.
What innovations are shaping the lid design market?
Key innovations include strawless lids to reduce plastic waste, ergonomic sip-through designs for better flow control, and snap-on lids with superior sealing technology to prevent leaks during delivery.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted