Bakery Contract Manufacturing Market
Bakery Contract Manufacturing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711857 | Published On : November 19, 2026 |
Format : 


 | Author : Hameer Thakur
Bakery Contract Manufacturing Market Size
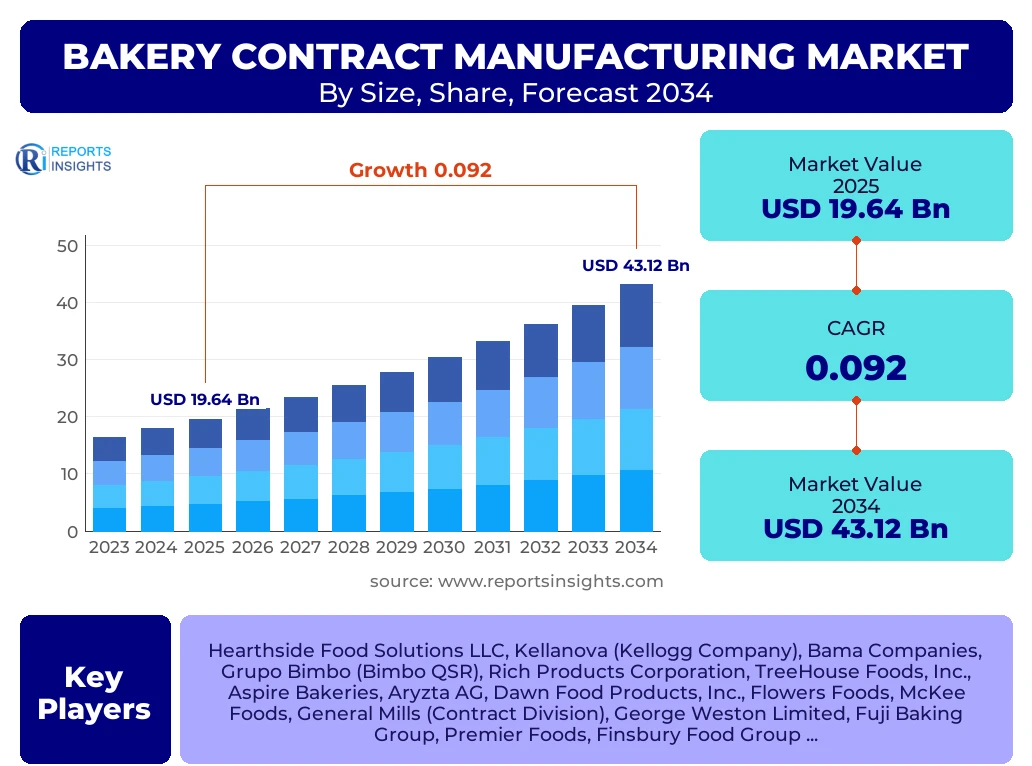
According to Reports Insights Consulting Pvt Ltd, The Bakery Contract Manufacturing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.2% between 2025 and 2034. The market is estimated at USD 21.45 Billion in 2026 and is projected to reach USD 43.12 Billion by the end of the forecast period in 2034.
Key Bakery Contract Manufacturing Market Trends & Insights
The global bakery contract manufacturing landscape is undergoing a radical transformation as food brands shift from asset-heavy production models to agile, outsourced solutions. Current market intelligence indicates a surging demand for specialty bakery products, including gluten-free, keto-friendly, and high-protein variants, which require specialized production lines that many traditional brands lack. Contract manufacturers are increasingly investing in high-speed automation and robotics to offset rising labor costs while maintaining strict quality control. Geographically, North America remains the dominant revenue generator due to the high penetration of private label brands, while the Asia-Pacific region is witnessing the most rapid expansion, fueled by urbanization and a growing appetite for Western-style baked goods. Competitive benchmarking reveals that leading players are differentiating themselves through "end-to-end" service offerings, encompassing everything from initial R&D and ingredient sourcing to final packaging and cold-chain logistics.
- Largest Region: North America, currently holding over 38% of the global market share.
- Fastest Growing Region: Asia-Pacific, expected to exhibit a CAGR of 11.4% during the forecast period.
- Largest Segment by Share: Bread and Rolls, accounting for approximately 42% of total market volume.
- Emerging Trend: The rise of Clean Label manufacturing, focusing on natural preservatives and non-GMO ingredients.
- Technology Integration: Increased adoption of AI-driven demand forecasting and IoT-enabled ovens for precise temperature control.
Key Takeaways Bakery Contract Manufacturing Market Size & Forecast
The trajectory of the bakery contract manufacturing market is intrinsically linked to the "premiumization" of the snack and bakery sectors. As consumer preferences pivot toward health-conscious and artisanal options, the industry is seeing a move away from mass-produced, standardized items toward small-batch, high-value production. Strategic partnerships between established CPG (Consumer Packaged Goods) firms and contract manufacturers are becoming the norm, allowing brands to launch limited-time offers (LTOs) and seasonal products without significant capital expenditure. Market forecasts suggest that the private label sector will continue to be a primary catalyst for growth, as retailers look to expand their own-brand portfolios with high-quality, differentiated baked goods that offer better margins than national brands.
- Leading Country: The United States remains the single largest market for outsourced bakery production globally.
- High-Growth Category: Frozen bakery products are seeing a massive uptick in contract manufacturing demand due to longer shelf lives and easier distribution.
- Margin Optimization: Contract manufacturing allows brands to reduce operational overhead by 15-25% on average.
- Regulatory Influence: Stringent food safety certifications like SQF and BRC are becoming mandatory prerequisites for top-tier contract manufacturers.
- Sustainability Focus: There is a significant push for sustainable packaging solutions and carbon-neutral manufacturing facilities.
Bakery Contract Manufacturing Market Drivers Analysis
The primary driver of the bakery contract manufacturing market is the increasing complexity of food production and the necessity for brands to maintain high levels of innovation. Brands are finding it more cost-effective to utilize the existing infrastructure of specialized co-manufacturers rather than building or upgrading their own facilities to accommodate new dietary trends. Furthermore, the global expansion of retail giants and their focus on private labels has created a consistent and growing volume of work for contract producers who can deliver consistent quality at scale.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Private Label Demand | +2.8% | North America & Europe | 2025 - 2034 |
| Demand for Specialty & Health-Conscious Baking | +2.1% | Global (Majorly Urban Centers) | 2025 - 2030 |
| Cost Efficiency through Outsourcing | +1.9% | North America & APAC | 2026 - 2034 |
| Rapid Urbanization and Westernization of Diets | +1.4% | India, China, SE Asia | 2025 - 2034 |
Bakery Contract Manufacturing Market Restraints Analysis
Despite strong growth, the market faces significant headwinds from volatile raw material prices and supply chain inconsistencies. Flour, sugar, and edible oil prices have fluctuated wildly due to geopolitical tensions and climate-related crop failures, squeezing the margins of contract manufacturers who often operate on fixed-price contracts. Additionally, the increasing stringency of global food safety regulations requires continuous investment in compliance, which can be a barrier for smaller manufacturing units.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Ingredient Costs | -1.2% | Global | 2025 - 2028 |
| Stringent Regulatory & Compliance Costs | -0.8% | European Union & North America | 2025 - 2034 |
| Risk of Intellectual Property (IP) Theft | -0.4% | Developing Markets | 2026 - 2034 |
Bakery Contract Manufacturing Market Opportunities Analysis
The shift toward "Plant-Based" and "Functional Foods" represents the single largest opportunity for contract manufacturers. Developing proprietary recipes for vegan pastries or protein-enriched breads allows manufacturers to position themselves as innovation partners rather than just production hubs. Additionally, the e-commerce boom and direct-to-consumer (DTC) bakery brands require specialized packaging and fulfillment services, opening new revenue streams for manufacturers who can integrate logistics into their service portfolio.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Vegan & Plant-Based Categories | +3.2% | Europe & North America | 2025 - 2034 |
| Adoption of Advanced Automation & AI | +1.5% | Japan, Germany, USA | 2027 - 2034 |
| E-commerce Specific Packaging Solutions | +1.1% | Global | 2025 - 2032 |
Bakery Contract Manufacturing Market Challenges Impact Analysis
Labor shortages in skilled baking and machine operation roles remain a persistent challenge, particularly in mature economies. Furthermore, the pressure to reduce plastic usage and adopt biodegradable packaging is forcing manufacturers to redesign production lines, which can be capital-intensive. Ensuring product consistency across multiple manufacturing locations for global brands also presents a significant logistical and quality control hurdle.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Technical Labor | -0.9% | USA, UK, Germany | 2025 - 2030 |
| Sustainability & Plastic Reduction Mandates | -0.6% | European Union | 2026 - 2034 |
| High Energy Costs for Industrial Baking | -0.7% | Europe | 2025 - 2029 |
Bakery Contract Manufacturing Market - Updated Report Scope
This report provides a comprehensive analysis of the global bakery contract manufacturing ecosystem, examining the strategic shift from in-house production to outsourced expertise. The scope encompasses detailed financial modeling, competitive landscape mapping, and a deep dive into the technological advancements driving efficiency in high-volume bakery production. We analyze the market through multiple lenses, including product type, service model, and end-user requirements, ensuring a holistic view of the industry's future trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 19.64 Billion |
| Market Forecast in 2034 | USD 43.12 Billion |
| Growth Rate | 9.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Hearthside Food Solutions LLC, Kellanova (Kellogg Company), Bama Companies, Grupo Bimbo (Bimbo QSR), Rich Products Corporation, TreeHouse Foods, Inc., Aspire Bakeries, Aryzta AG, Dawn Food Products, Inc., Flowers Foods, McKee Foods, General Mills (Contract Division), George Weston Limited, Fuji Baking Group, Premier Foods, Finsbury Food Group, Yamazaki Baking Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The bakery contract manufacturing market is segmented primarily by product category, which allows for specialized production efficiencies. The "Bread and Rolls" segment remains the largest due to its status as a staple food, but "Cakes and Pastries" are seeing higher growth rates driven by the indulgence trend and premium gifting culture. On the service side, "Co-Manufacturing" is the dominant model, where brands provide the recipe and the manufacturer provides the facility and labor. However, "Private Labeling" is gaining ground as retailers seek to differentiate their offerings with exclusive, high-quality bakery products developed in partnership with manufacturers.
- By Product Type:
- Bread & Rolls (Artisan, Sliced, Buns)
- Cakes & Pastries (Muffins, Croissants, Cupcakes)
- Cookies & Biscuits (Health-based, Gourmet)
- Doughs & Batters (Frozen, Refrigerated)
- Savory Snacks (Pretzels, Crackers)
- By Service Model:
- Full-Service Manufacturing (End-to-end)
- Packaging and Co-Packing Only
- Product Design and R&D Services
- By Ingredient Profile:
- Conventional
- Organic
- Gluten-Free & Allergen-Friendly
- High-Protein/Low-Carb
Regional Highlights
The regional distribution of the bakery contract manufacturing market reveals a clear divide between mature markets focused on innovation and emerging markets focused on scale. North America, particularly the United States, is the market leader, characterized by a highly sophisticated retail landscape and a massive demand for convenience-based bakery snacks. Europe follows closely, with Germany, France, and the UK serving as hubs for artisan-style contract baking and strict organic standards. The Asia-Pacific region, led by China and India, is the fastest-growing market, driven by the rapid expansion of quick-service restaurants (QSRs) and an increasing middle-class preference for packaged, Western-style breakfast items. Latin America and the Middle East are also showing steady growth, primarily in the frozen dough and long-shelf-life biscuit segments.
- North America: Market leader in Private Label penetration and innovative healthy-snacking manufacturing.
- Europe: Leading the world in Clean Label standards and artisanal-at-scale production techniques.
- Asia-Pacific: Highest growth rate due to the expansion of retail chains and changing dietary habits in urban populations.
- LAMEA: Significant opportunities in the supply of frozen bakery products to the hospitality and tourism sectors in the Middle East.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Bakery Contract Manufacturing Market. These players are selected based on their manufacturing capacity, global footprint, R&D capabilities, and strategic partnerships with major CPG brands.
- Hearthside Food Solutions LLC
- Kellanova (formerly Kellogg Company)
- Bama Companies
- Grupo Bimbo (Bimbo QSR)
- Rich Products Corporation
- TreeHouse Foods, Inc.
- Aspire Bakeries
- Aryzta AG
- Dawn Food Products, Inc.
- Flowers Foods
- McKee Foods
- General Mills (Contract Division)
- George Weston Limited
- Fuji Baking Group
- Premier Foods
- Finsbury Food Group
- Yamazaki Baking Co., Ltd.
- Europastry
- C.H. Guenther & Son
- BakeMark
Frequently Asked Questions
What is the current market size of the Bakery Contract Manufacturing industry?
The market is valued at approximately USD 19.64 Billion in 2025 and is expected to reach USD 43.12 Billion by 2034, growing at a CAGR of 9.2%.
What are the main benefits for brands using contract manufacturing for bakery products?
Key benefits include reduced capital expenditure, access to specialized production technology, faster time-to-market for new products, and the ability to scale production up or down based on seasonal demand.
Which product segment is the most dominant in the bakery contract manufacturing market?
The Bread and Rolls segment is currently the most dominant, holding the largest market share, while Cakes and Pastries are the fastest-growing categories in terms of premiumization.
How is the demand for "Clean Label" products affecting contract manufacturers?
Contract manufacturers are investing heavily in new formulations that eliminate artificial preservatives and dyes, as brands demand "cleaner" ingredient lists to satisfy health-conscious consumers.
Which region offers the most significant growth opportunities for bakery contract manufacturing?
The Asia-Pacific region is the fastest-growing, driven by increased urbanization, the expansion of modern retail, and a shift toward packaged food products in countries like China, India, and Vietnam.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
