Autonomounderwater Vehicle Market
Autonomounderwater Vehicle Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711587 | Published On : November 07, 2026 |
Format : 


 | Author : Ashraf Shehata
Autonomounderwater Vehicle Market Size
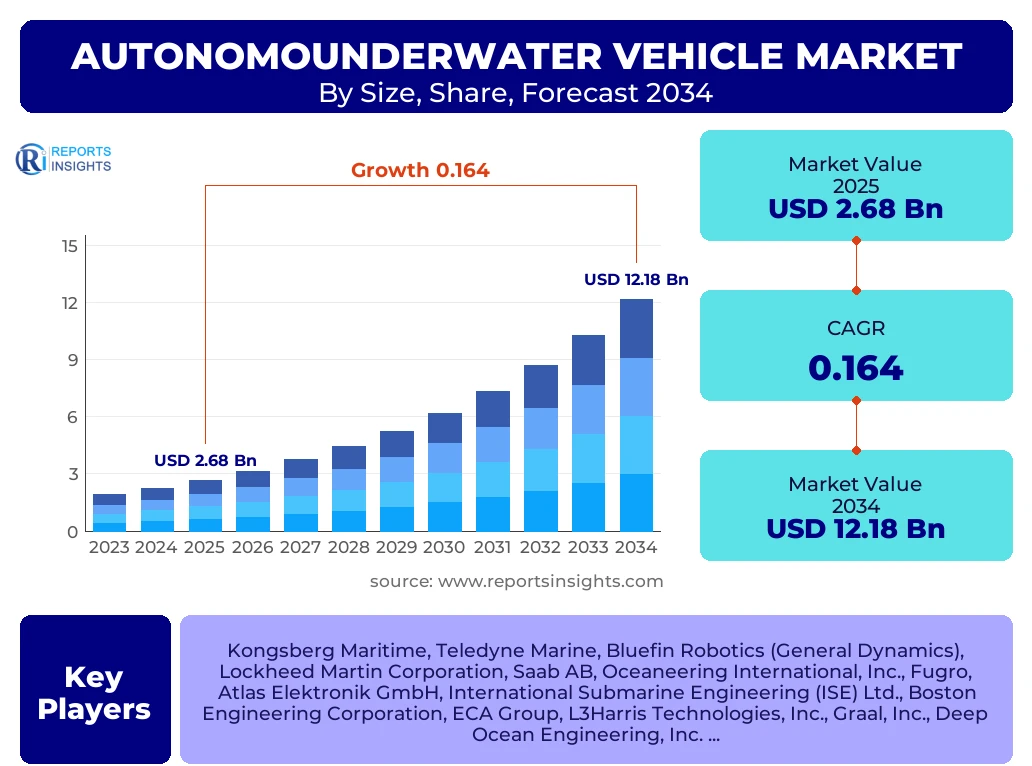
According to Reports Insights Consulting Pvt Ltd, The Autonomounderwater Vehicle Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.4% between 2025 and 2034. The market is estimated at USD 3.12 Billion in 2026 and is projected to reach USD 12.18 Billion by the end of the forecast period in 2034.
Key Autonomounderwater Vehicle Market Trends & Insights
The global market for Autonomous Underwater Vehicles (AUVs) is undergoing a significant transformation driven by the convergence of advanced sensor technology, artificial intelligence, and the increasing necessity for subsea data acquisition. Users and stakeholders are increasingly prioritizing systems that offer long-endurance capabilities and high-resolution imaging to support offshore energy operations and national security initiatives. Modern trends indicate a pivot toward modular architectures, allowing a single vehicle to be reconfigured for diverse missions ranging from hydrographic surveying to mine countermeasure operations. Furthermore, the integration of swarm robotics is becoming a focal point for competitive benchmarking, as multi-vehicle coordination significantly reduces the time required for large-scale seabed mapping.
- North America remains the largest regional market due to substantial naval defense spending and established offshore oil and gas infrastructure.
- The Asia Pacific region is identified as the fastest-growing market, propelled by maritime territorial disputes and rapid offshore wind energy developments in China and India.
- Deep Water AUVs represent the largest segment in terms of market share, driven by deep-sea mineral exploration and the maintenance of transcontinental subsea cables.
- Hybrid AUV-ROV systems are gaining traction as they combine the autonomy of AUVs with the manual intervention capabilities of Remotely Operated Vehicles.
- AI-driven onboard processing is reducing the latency between data collection and actionable intelligence, a critical factor for defense and search-and-rescue applications.
Key Takeaways Autonomounderwater Vehicle Market Size & Forecast
Market analysis indicates that the demand for subsea autonomy is no longer limited to high-budget scientific research; it has become a critical operational requirement for the commercial and defense sectors. Investors and market participants are focusing on the total cost of ownership, where AUVs provide a clear advantage over traditional manned vessels by reducing crew requirements and operational risks. The forecast period is expected to see a surge in demand for small-scale, man-portable AUVs that can be deployed rapidly from various platforms, including Unmanned Surface Vessels (USVs), thereby creating a collaborative cross-domain autonomous ecosystem.
- The United States leads the global market in terms of technological innovation and deployment frequency within the defense sector.
- Energy companies are transitioning from periodic inspections to continuous monitoring strategies, significantly boosting the demand for resident AUV systems.
- Advancements in battery chemistry, particularly lithium-sulfur and solid-state variants, are expected to double the operational range of medium-class AUVs by 2030.
- Norway and the United Kingdom are emerging as pivotal hubs for commercial AUV applications in the offshore wind and North Sea oil fields.
- Strategic partnerships between hardware manufacturers and AI software developers are accelerating the commercialization of fully autonomous navigation in complex environments.
Autonomounderwater Vehicle Market Drivers Analysis
The primary catalyst for growth in the AUV market is the global expansion of offshore renewable energy, particularly wind farms, which require precise site characterization and ongoing structural health monitoring. Additionally, the modernization of naval fleets worldwide is driving the adoption of AUVs for clandestine surveillance, anti-submarine warfare, and mine neutralization, as these platforms offer high stealth and persistence without risking human lives. The increasing viability of deep-sea mining for rare earth elements further stimulates demand for vehicles capable of operating at extreme depths with high autonomy.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Offshore Wind Energy Projects | +4.2% | Europe and Asia Pacific | 2025 - 2034 |
| Military Modernization & Defense Spending | +3.8% | United States, China, India | 2025 - 2030 |
| Advancements in Subsea Communication & AI | +3.1% | Global | 2026 - 2034 |
| Deep-Sea Mineral Exploration Activities | +2.5% | International Waters / Brazil | 2028 - 2034 |
Autonomounderwater Vehicle Market Restraints Analysis
Despite the optimistic growth projections, the market faces significant hurdles related to the high initial capital expenditure and the technical limitations of underwater communication. The physical properties of water attenuate radio waves, making real-time command and control difficult over long distances without sophisticated acoustic or optical links. Furthermore, the high cost of specialized sensors, such as Synthetic Aperture Sonar (SAS) and inertial navigation systems (INS), remains a barrier for small and medium-sized enterprises seeking to adopt AUV technology.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Procurement & Maintenance Costs | -2.1% | Developing Economies | 2025 - 2034 |
| Acoustic Signal Interference & Bandwidth Limits | -1.8% | Global | 2025 - 2034 |
Autonomounderwater Vehicle Market Opportunities Analysis
The emergence of "AUV-as-a-Service" (AaaS) models presents a substantial opportunity for growth, allowing end-users to leverage subsea data without the burden of equipment ownership. This model is particularly attractive for environmental monitoring and oceanographic research institutes. Additionally, the development of subsea docking stations—where AUVs can recharge and upload data autonomously—is paving the way for resident AUV systems that can remain submerged for months, offering unprecedented temporal resolution for environmental and infrastructure data.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Subsea Resident Systems & Docking Stations | +3.5% | Norway, USA, Gulf of Mexico | 2027 - 2034 |
| AUV-as-a-Service Business Models | +2.9% | Global Commercial Sector | 2026 - 2034 |
Autonomounderwater Vehicle Market Challenges Impact Analysis
Operational challenges remain centered on the energy density of power sources, which directly limits mission duration and the complexity of onboard processing. The harsh underwater environment, characterized by extreme pressure and corrosive saltwater, necessitates the use of expensive, specialized materials that complicate the manufacturing process. Additionally, the lack of standardized communication protocols between different AUV manufacturers hinders the development of interoperable multi-vehicle swarms, creating silos in the market.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Battery Technology & Energy Management | -1.5% | Global | 2025 - 2030 |
| Regulatory & Legal Frameworks for Autonomy | -1.2% | International Maritime Borders | 2025 - 2034 |
Autonomounderwater Vehicle Market - Updated Report Scope
The scope of this market report covers a detailed analysis of the AUV landscape, focusing on technological tiers from shallow-water man-portable units to heavy-duty deep-water systems capable of operating at depths exceeding 6,000 meters. The research encompasses the entire value chain, from component suppliers of navigation and propulsion systems to end-users in the military, commercial energy, and scientific research sectors. By analyzing historical data from 2020 to 2024, the report provides a robust forecast through 2034, factoring in geopolitical shifts, environmental regulations, and breakthroughs in autonomous software.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.68 Billion |
| Market Forecast in 2034 | USD 12.18 Billion |
| Growth Rate | 16.4% CAGR |
| Number of Pages | 256 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Kongsberg Maritime, Teledyne Marine, Bluefin Robotics (General Dynamics), Lockheed Martin Corporation, Saab AB, Oceaneering International, Inc., Fugro, Atlas Elektronik GmbH, International Submarine Engineering (ISE) Ltd., Boston Engineering Corporation, ECA Group, L3Harris Technologies, Inc., Graal, Inc., Deep Ocean Engineering, Inc., Riptide Autonomous Solutions, Boeing, Kawasaki Heavy Industries, Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the AUV market reflects the diverse operational requirements across different industries. The Type segment is primarily categorized by depth capability, as the structural and sensor requirements vary drastically between a 100-meter shallow survey and a 6,000-meter abyssal mission. Application-wise, the Defense sector remains the primary revenue contributor, though the Oil & Gas sector is rapidly adopting AUVs for pipeline inspection to replace expensive ROV support vessels. Technology-based segmentation highlights the shift from simple acoustic telemetry to high-bandwidth optical and laser-based communication for short-range, high-speed data transfer.
- By Vehicle Type: Shallow AUVs are utilized for coastal surveys and port security; Medium AUVs are the workhorses of the oil and gas industry; Deep AUVs are specialized for mineral exploration and deep-sea research.
- By Application: Military remains dominant with Mine Countermeasures (MCM) and Intelligence, Surveillance, and Reconnaissance (ISR) missions; Commercial applications are growing in subsea infrastructure inspection and environmental impact assessments.
- By Technology: High-precision Inertial Navigation Systems (INS) and Doppler Velocity Logs (DVL) are essential for autonomy; Synthetic Aperture Sonar (SAS) is becoming the standard for high-resolution seabed mapping.
- By Propulsion: Electric propulsion remains standard, with significant R&D into fuel cells and long-range glider technology that uses buoyancy changes for forward motion.
Regional Highlights
- North America: This region holds the largest market share, driven by the United States Navy's massive investment in Unmanned Underwater Vehicles (UUV) programs and the advanced offshore infrastructure in the Gulf of Mexico.
- Europe: Europe is the leading region for commercial AUV applications, particularly in the North Sea. Countries like Norway and the UK are pioneers in using AUVs for offshore wind farm maintenance and subsea oil field automation.
- Asia Pacific: Expected to be the fastest-growing region due to rising maritime security concerns in the South China Sea and aggressive investments in offshore energy by China, Japan, and Australia.
- Middle East & Africa: Growth is centered around the oil-rich regions of the Persian Gulf and the increasing need for underwater security for desalination plants and critical maritime corridors.
- Latin America: Market growth is primarily linked to deep-water oil exploration off the coast of Brazil, where state-owned enterprises are investing in autonomous monitoring solutions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Autonomounderwater Vehicle Market.- Kongsberg Maritime
- Teledyne Marine
- General Dynamics (Bluefin Robotics)
- Lockheed Martin Corporation
- Saab AB
- Oceaneering International, Inc.
- Fugro
- Atlas Elektronik GmbH
- International Submarine Engineering Ltd.
- Boston Engineering Corporation
- ECA Group
- L3Harris Technologies, Inc.
- Graal, Inc.
- Deep Ocean Engineering, Inc.
- Riptide Autonomous Solutions
- Boeing
- Kawasaki Heavy Industries, Ltd.
- Nido Robotics
- Anduril Industries
- OceanScan - Marine Systems & Technology
Frequently Asked Questions
What are the main advantages of using AUVs over ROVs?
AUVs operate without a physical tether to a surface ship, allowing for greater freedom of movement, reduced operational costs by eliminating the need for large support vessels, and the ability to operate in environments where cables would be a hindrance, such as under ice or inside complex structures.
How do AUVs navigate underwater without GPS?
AUVs utilize a combination of Inertial Navigation Systems (INS), Doppler Velocity Logs (DVL), and acoustic positioning systems (like LBL or USBL). Sophisticated algorithms fuse data from these sensors to estimate the vehicle's position relative to its launch point or known seafloor features.
Which industry sector is the largest consumer of AUV technology?
The Military and Defense sector is currently the largest consumer, primarily using AUVs for mine countermeasure operations, anti-submarine warfare, and clandestine surveillance. However, the commercial energy sector is rapidly closing the gap through applications in offshore wind and oil and gas.
What is the typical mission duration for a modern AUV?
Mission duration varies by size and power source. Small, battery-powered AUVs typically operate for 8 to 24 hours, while larger deep-water vehicles can last several days. Underwater gliders, which use buoyancy-driven propulsion, can stay deployed for several months.
What are the primary technical challenges facing the AUV market today?
The main challenges include the limited energy density of underwater power sources, the difficulty of high-bandwidth underwater communication, and the high cost of the precise sensors required for fully autonomous navigation and high-quality data collection.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
