Automotive Seat Market
Automotive Seat Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711624 | Published On : November 10, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Seat Market Size
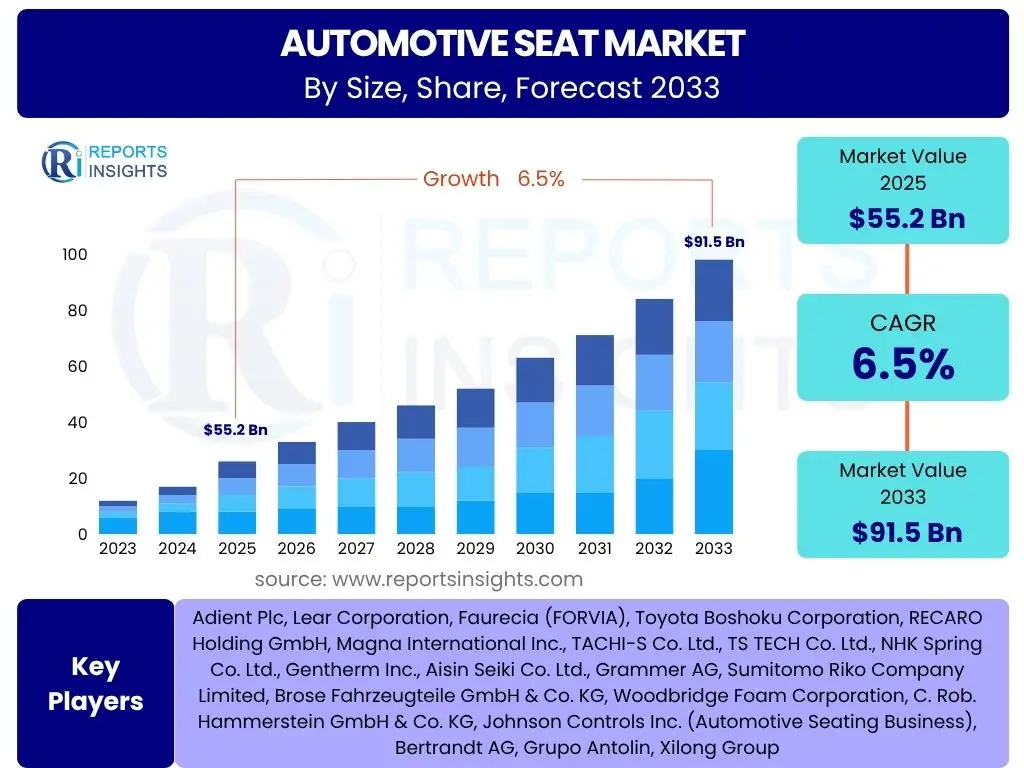
According to Reports Insights Consulting Pvt Ltd, The Automotive Seat Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% between 2025 and 2034. The market is estimated at USD 57.42 Billion in 2026 and is projected to reach USD 83.56 Billion by the end of the forecast period in 2034.
Key Automotive Seat Market Trends & Insights
The global automotive seating industry is undergoing a structural transformation driven by the transition toward autonomous, electric, and shared mobility. As vehicles evolve into "third living spaces," the focus of seat design has shifted from basic safety and positioning to advanced ergonomics, modularity, and wellness integration. Significant investments are being channeled into intelligent seating systems that feature biometric sensors to monitor driver fatigue and health metrics. Furthermore, the rise of Electric Vehicles (EVs) has catalyzed the demand for ultra-lightweight seating structures to offset battery weight and extend driving range. Regional analysis indicates that the Asia-Pacific region remains the primary engine of growth, supported by massive production volumes in China and India, while North America and Europe lead in the adoption of premium, multi-functional seating technologies.
- Largest Region: Asia-Pacific, holding a dominant market share of over 42% due to high vehicle production and increasing demand for mid-range and luxury cars.
- Fastest Growing Region: Asia-Pacific is also expected to maintain the highest CAGR, fueled by rapid urbanization and the expansion of domestic manufacturing hubs in Southeast Asia.
- Largest Segment by Value: The Passenger Car segment continues to hold the largest market share, driven by high global sales volumes and the increasing inclusion of premium features in mass-market models.
- Leading Material Trend: Synthetic leather and sustainable bio-based fabrics are experiencing the fastest growth as OEMs strive to meet Environmental, Social, and Governance (ESG) targets.
- Key Technology Shift: Integration of climate-controlled seating (heating and ventilation) is moving from luxury segments to standard offerings in mid-size SUVs.
Key Takeaways Automotive Seat Market Size & Forecast
The trajectory of the Automotive Seat market is intrinsically linked to the broader automotive production recovery and the shifting preferences of modern consumers who prioritize interior comfort over exterior aesthetics. Current market data suggests a steady recovery from supply chain disruptions, with a renewed focus on localized manufacturing to mitigate logistical risks. Stakeholders are increasingly adopting vertical integration strategies, where seat manufacturers develop their own foam and trim components to optimize cost and quality. The forecast period anticipates a significant surge in the "Smart Seating" category, where software-defined seating adjustments and AI-driven comfort profiles become standard in high-end electric vehicles. This evolution is not merely about comfort but is a critical component of the vehicle's safety ecosystem, incorporating advanced airbag systems and pre-collision positioning technologies.
- Market Valuation: The total market value is set to surpass the USD 80 billion mark by 2034, reflecting the increasing complexity and cost of individual seat units.
- Dominant Country: China represents the single largest market for Automotive Seat, both in terms of consumption and manufacturing capacity.
- SUV Dominance: The rising popularity of SUVs globally is a major tailwind, as these vehicles typically require more complex, versatile, and higher-margin seating configurations.
- Material Innovation: Decarbonization efforts are leading to the replacement of traditional petroleum-based foams with soy-based or recycled alternatives.
- Autonomous Influence: The development of Level 4 and Level 5 autonomous vehicles is driving demand for swivel seats and reconfigurable cabin layouts, which command higher price points.
Automotive Seat Market Drivers Analysis
The primary growth engine for the automotive seating market is the global surge in demand for premium interior experiences, coupled with the rapid expansion of the electric vehicle sector. As EVs reduce engine noise and vibration, the consumer's focus shifts toward the tactile and ergonomic quality of the cabin, making seats a focal point of brand differentiation. Additionally, stringent government regulations regarding occupant safety and the push for lightweight materials to enhance fuel efficiency are compelling OEMs to adopt advanced high-strength steel and magnesium alloys in seat frames. The proliferation of ride-sharing services is also driving a niche but growing demand for high-durability, easy-to-clean seating solutions designed for high-frequency use.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electrification and Range Optimization | +1.2% | Global (Strongest in Europe & China) | 2025–2034 |
| Consumer Demand for Luxury & Comfort Features | +0.9% | North America & Middle East | 2025–2030 |
| Safety Regulations & NCAP Rating Requirements | +0.7% | Europe & North America | 2025–2034 |
| Growth in SUV and Crossover Sales | +1.1% | India, USA, and China | 2025–2032 |
Automotive Seat Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds from volatile raw material prices and the high cost of advanced seating technologies. The price of specialized components like memory foam, electronic actuators, and high-grade leather is sensitive to global supply chain fluctuations, often squeezing the profit margins of Tier-1 suppliers. Furthermore, the increasing complexity of integrating electronic components into seats raises concerns regarding long-term reliability and repairability, which can be a deterrent for cost-conscious consumers in emerging markets. Regulatory hurdles related to the recyclability of composite materials also pose a challenge for manufacturers aiming for circular economy models.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material Costs (Steel, Polymers) | -0.5% | Global | 2025–2028 |
| High R&D Investment for Smart Seating | -0.3% | Europe & Japan | 2025–2030 |
| Complexity of Post-Sales Maintenance | -0.2% | Emerging Markets (ASEAN, Africa) | 2026–2034 |
Automotive Seat Market Opportunities Analysis
The advent of software-defined vehicles presents a massive opportunity for seating manufacturers to offer "Comfort-as-a-Service." This includes subscription-based features such as advanced massage profiles, OTA (Over-the-Air) updates for seat adjustment algorithms, and personalized thermal management. Additionally, the growing "green" consumer segment is creating a lucrative market for vegan leather and recycled ocean plastic trims. There is also a significant untapped opportunity in the commercial vehicle segment, where ergonomic seating is increasingly recognized as a key factor in reducing driver fatigue and improving fleet safety and productivity.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Sustainable & Bio-based Materials | +0.8% | Germany, Sweden, and California (USA) | 2026–2034 |
| Integration of Biometric & Health Monitoring | +0.6% | Japan & South Korea | 2027–2034 |
| Modular Seating for Autonomous Shuttles | +0.5% | Global Urban Hubs | 2028–2034 |
| Expansion into High-Growth Emerging Markets | +0.9% | India, Vietnam, and Brazil | 2025–2034 |
Automotive Seat Market Challenges Impact Analysis
Manufacturers are currently grappling with the dual challenge of reducing the carbon footprint of their production processes while maintaining the rigorous safety standards required for automotive grade components. The transition to lightweight materials often involves complex manufacturing techniques like carbon fiber molding or specialized alloy casting, which are difficult to scale efficiently. Moreover, the rapid pace of technological change means that seating designs must be flexible enough to accommodate evolving cabin architectures without requiring total re-tooling of production lines. Cyber security is also becoming a concern as seats become more connected and integrated with the vehicle's central computer system.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Balancing Lightweighting with Structural Integrity | -0.4% | Global | 2025–2030 |
| Supply Chain Fragility for Electronic Components | -0.5% | Global (Dependent on Taiwan/China) | 2025–2027 |
| Stringent Sustainability & Circularity Mandates | -0.3% | European Union | 2026–2034 |
Automotive Seat Market - Updated Report Scope
This comprehensive market research report provides a granular analysis of the global Automotive Seat industry, encompassing technical innovations, competitive dynamics, and regulatory landscapes across major geographical regions. The scope includes an in-depth evaluation of various seat types, from entry-level fabric seats to high-end climate-controlled and massage-integrated units. It specifically examines the impact of the shift toward electric and autonomous vehicles on seat architecture and material science. By triangulating data from primary interviews, financial reports, and proprietary databases, the report offers actionable insights for OEMs, Tier-1 suppliers, and investors looking to capitalize on the next wave of automotive interior evolution.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 55.20 Billion |
| Market Forecast in 2034 | USD 83.56 Billion |
| Growth Rate | 4.8% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Adient plc, Lear Corporation, Faurecia (Forvia), Toyota Boshoku Corporation, Magna International Inc., Tachi-S Co., Ltd., NHK Spring Co., Ltd., TS Tech Co., Ltd., Gentherm Inc., Bharat Seats Ltd., Hyundai Transys, Aisin Seiki Co., Ltd., IFB Automotive Pvt. Ltd., Sitech (Volkswagen Group), Brose Fahrzeugteile, Grote Company, Recaro Automotive, and Delta Kogyo Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Automotive Seat market is segmented based on technology, material, vehicle type, and distribution channel, reflecting the diverse requirements of different vehicle categories and consumer demographics. The technology segment is witnessing a shift where high-end features such as 12-way power adjustment and pneumatic massage systems are trickling down to mid-tier vehicles. Material science is another critical area of segmentation, with a growing divide between traditional luxury (genuine leather) and modern sustainable luxury (recycled materials). Vehicle type segmentation remains dominated by the passenger car category, though the heavy commercial vehicle segment is showing increased demand for air-suspension seats to enhance driver safety and comfort during long-haul operations.
- By Seat Type:
- Bucket Seats (Dominant in Passenger Cars)
- Bench Seats (Common in Rear Rows and LCVs)
- Split Bench Seats (Preferred for Versatility in SUVs)
- Folding/Stowable Seats (Key for Minivans and Crossovers)
- By Technology:
- Standard/Manual Seats (Mass Market)
- Powered Seats (Growing in Mid-range Segments)
- Heated & Ventilated Seats (High Demand in Cold/Hot Climates)
- Massage & Wellness Seats (Ultra-Luxury and Autonomous Tech)
- By Material:
- Genuine Leather (Premium & Luxury Segments)
- Synthetic Leather (High Growth due to Durability and Cost)
- Fabric/Textile (Budget and Entry-level Models)
- Sustainable/Recycled Materials (Eco-conscious Brands)
- By Vehicle Type:
- Passenger Cars (Sedans, Hatchbacks, SUVs)
- Light Commercial Vehicles (Vans, Pickups)
- Heavy Commercial Vehicles (Trucks, Buses)
Regional Highlights
- Asia-Pacific: The undisputed leader in terms of market volume, accounting for more than 40% of global production. China is the powerhouse of this region, supported by a vast ecosystem of Tier-2 and Tier-3 suppliers. India is emerging as a critical hub for low-cost, high-volume seating manufacturing.
- North America: A mature market characterized by a high preference for large SUVs and pickup trucks, which require premium, oversized, and multi-functional seating. The region is a pioneer in the adoption of memory-enabled and smart seating technologies.
- Europe: The epicenter of material innovation and sustainability. European OEMs are leading the transition to "leather-free" interiors and are subject to the strictest safety and recyclability regulations (Euro NCAP).
- Latin America & MEA: These regions are seeing steady growth driven by the expansion of local assembly plants by global OEMs. The Middle East specifically shows high demand for advanced climate-controlled seating due to extreme weather conditions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Seat Market.- Adient plc
- Lear Corporation
- Faurecia (Forvia Group)
- Toyota Boshoku Corporation
- Magna International Inc.
- Tachi-S Co., Ltd.
- NHK Spring Co., Ltd.
- TS Tech Co., Ltd.
- Gentherm Inc. (Specialists in Thermal Seating)
- Bharat Seats Ltd.
- Hyundai Transys
- Aisin Seiki Co., Ltd.
- IFB Automotive Pvt. Ltd.
- Sitech (Volkswagen Group Subsidiary)
- Brose Fahrzeugteile
- Recaro Automotive (Premium & Performance Seats)
- Delta Kogyo Co., Ltd.
- Bridgestone Corporation (Foam Components)
- Martur Fompak International
- Grammer AG
Frequently Asked Questions
What is the current market size of the global Automotive Seat market?
The global Automotive Seat market is estimated to be valued at approximately USD 55.20 Billion in 2025 and is projected to grow steadily, reaching over USD 83.56 Billion by 2034.
Which region is expected to lead the Automotive Seat market growth?
The Asia-Pacific region is expected to lead both in terms of market share and growth rate, driven by massive vehicle production in China, India, and Southeast Asia.
What are the most significant trends impacting seat design today?
Key trends include the integration of "smart" technologies like biometric sensors, the shift toward sustainable and vegan materials, and the development of modular, rotatable seats for autonomous vehicles.
How is the rise of Electric Vehicles (EVs) affecting the seating market?
EVs are driving the demand for lightweight seat structures to help maximize battery range. Additionally, the quieter cabins of EVs are pushing OEMs to focus more on seat comfort and noise-dampening materials.
What role does sustainability play in the future of automotive seating?
Sustainability is becoming a core requirement, with manufacturers moving away from traditional leather toward recycled polymers, bio-based foams, and materials that are easier to disassemble and recycle at the end of the vehicle's life.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
