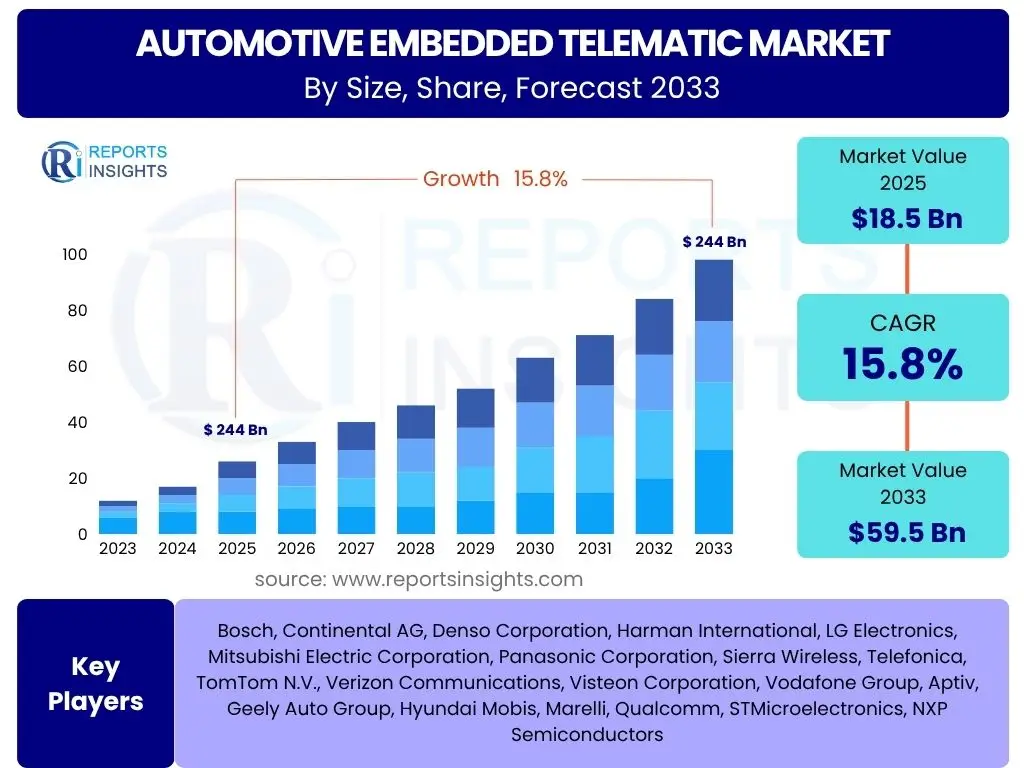
Automotive Embedded Telematic Market
Automotive Embedded Telematic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711367 | Published On : October 29, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Embedded Telematic Market Size
According to Reports Insights Consulting Pvt Ltd, The Automotive Embedded Telematic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.8% between 2025 and 2034. The market is estimated at USD 66.48 Billion in 2026 and is projected to reach USD 185.35 Billion by the end of the forecast period in 2034.
Key Automotive Embedded Telematic Market Trends & Insights
The Automotive Embedded Telematic market is undergoing a profound transformation driven by the convergence of high-speed 5G connectivity, advanced edge computing, and the proliferation of Software-Defined Vehicles (SDVs). Modern automotive architectures are shifting from decentralized electronic control units to centralized high-performance computing platforms that rely heavily on embedded telematics for real-time data exchange. Users and stakeholders are increasingly focused on how these systems facilitate Over-the-Air (OTA) updates, which allow manufacturers to enhance vehicle performance and deploy safety patches without physical recalls. Furthermore, the integration of Artificial Intelligence (AI) at the edge is enabling more sophisticated predictive maintenance and enhanced driver assistance systems, positioning embedded telematics as the foundational layer for future autonomous mobility ecosystems.
- Largest Region: North America currently holds the largest market share due to early adoption of connected car technologies and stringent safety mandates.
- Fastest Growing Region: Asia Pacific is expected to be the fastest-growing region, fueled by massive automotive production in China and India and increasing digital infrastructure investments.
- Largest Segment by Solution: The safety and security segment remains the largest due to global government regulations requiring emergency call (eCall) systems.
- Emerging Trend: The shift from 4G LTE to 5G NR (New Radio) is significantly reducing latency, enabling Vehicle-to-Everything (V2X) communication.
- Market Maturity: Developing markets are seeing a rapid transition from aftermarket solutions to factory-fitted embedded systems as standard equipment in mid-range vehicles.
Key Takeaways Automotive Embedded Telematic Market Size & Forecast
The global outlook for the Automotive Embedded Telematic market is robust, characterized by a transition from basic GPS tracking to complex data-driven service models. Analysts observe that the market is moving toward a service-oriented architecture where data monetization becomes a primary revenue stream for Original Equipment Manufacturers (OEMs). The integration of telematics with insurance (Usage-Based Insurance) and fleet management software is creating a multi-dimensional value proposition that extends far beyond simple vehicle navigation. As 5G coverage expands globally, the reliability of embedded systems will reach the threshold necessary for Level 3 and Level 4 autonomous driving, further cementing the market's long-term growth trajectory.
- Leading Country: The United States leads in value due to high consumer spending on premium connected features and advanced telematics service providers.
- Growth Catalyst: Government mandates regarding vehicle tracking and emergency response systems in Europe and Brazil are critical market stabilizers.
- Segment Dominance: Passenger cars account for the majority of the market share, though commercial vehicles are seeing higher intensity of telematics usage for logistics optimization.
- Strategic Shift: OEMs are increasingly partnering with technology giants to develop custom operating systems that integrate embedded telematics seamlessly into the user interface.
Automotive Embedded Telematic Market Drivers Analysis
The primary driver for the Automotive Embedded Telematic market is the global escalation of safety regulations and government mandates aimed at reducing road fatalities. In many jurisdictions, the inclusion of automated emergency call systems and satellite-based tracking is no longer optional but a legal requirement for vehicle type approval. These mandates force OEMs to integrate telematics control units (TCUs) at the factory level, ensuring a baseline of connectivity across all vehicle tiers. This regulatory environment creates a stable, long-term demand floor for hardware components and software services.
Secondary drivers include the surging demand for enhanced user experience and the rise of the Software-Defined Vehicle. Modern consumers expect their vehicles to function like smartphones, offering seamless integration with digital ecosystems, real-time traffic updates, and cloud-based infotainment. Additionally, the operational efficiencies provided to fleet managers—such as real-time fuel monitoring, route optimization, and predictive maintenance—are driving significant adoption in the commercial vehicle sector. The ability to reduce downtime and optimize total cost of ownership (TCO) makes embedded telematics an essential investment for logistics and transportation companies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Government Safety Mandates (eCall/AIS-140) | +4.2% | European Union, India, Brazil | 2025-2030 |
| Expansion of 5G Infrastructure | +3.8% | Global (China, USA, South Korea) | 2026-2034 |
| Demand for Over-the-Air (OTA) Update Capabilities | +3.1% | North America, Europe | 2025-2034 |
| Growth in Fleet Management & Logistics Optimization | +2.7% | Global | 2025-2034 |
Automotive Embedded Telematic Market Restraints Analysis
One of the most significant restraints facing the market is the heightened concern over cybersecurity and data privacy. As vehicles become more connected, they also become more vulnerable to remote hacking, which could compromise passenger safety and personal data. High-profile demonstrations of vehicle vulnerabilities have led to increased scrutiny from regulators and a degree of consumer hesitation. Implementing robust, multi-layered security protocols adds significant complexity and cost to the development cycle, which can delay the rollout of new telematics features.
Another restraining factor is the high initial cost of high-end telematics systems and the ongoing subscription fees associated with premium services. While costs are declining, the integration of advanced sensors and high-speed modems remains a barrier for the entry-level vehicle segment in price-sensitive markets. Furthermore, the lack of standardized communication protocols across different OEMs and regions can create interoperability issues, complicating the development of a unified V2X ecosystem and limiting the effectiveness of certain telematics-driven safety features.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Threats and Data Privacy Concerns | -2.5% | Global (High impact in North America/EU) | 2025-2034 |
| High System Integration and Subscription Costs | -1.8% | Developing Economies (LAMEA, SE Asia) | 2025-2029 |
| Lack of Universal Communication Standards | -1.2% | Global | 2025-2030 |
Automotive Embedded Telematic Market Opportunities Analysis
The integration of embedded telematics with Usage-Based Insurance (UBI) represents a massive growth opportunity. By capturing granular data on driving behavior—such as braking patterns, speed, and cornering—insurers can offer personalized premiums, rewarding safe drivers and accurately pricing risk. This creates a new revenue stream for OEMs who can act as data brokers, providing high-quality, verified vehicle data to insurance companies. As the "pay-how-you-drive" model gains popularity, embedded telematics will become the indispensable hardware layer for the modern insurance industry.
Furthermore, the advent of autonomous driving and the development of Smart Cities provide long-term tailwinds. Embedded telematics systems are the primary gateway for V2X (Vehicle-to-Everything) communication, allowing cars to talk to traffic lights, pedestrians, and other vehicles. This connectivity is essential for the safe operation of self-driving cars. Additionally, data monetization through in-vehicle commerce and location-based services (LBS) offers OEMs a way to transform the vehicle into a digital marketplace, providing tailored advertisements and services based on the vehicle's real-time location and driver preferences.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Usage-Based Insurance (UBI) Models | +3.5% | Western Europe, USA, China | 2026-2034 |
| V2X Infrastructure and Smart City Integration | +4.0% | China, Japan, Singapore | 2028-2034 |
| In-Vehicle E-commerce and Data Monetization | +2.9% | North America, Europe | 2027-2034 |
Automotive Embedded Telematic Market Challenges Impact Analysis
A persistent challenge is the varying pace of infrastructure development across different geographic regions. While urban areas in developed nations may support 5G and V2I (Vehicle-to-Infrastructure) capabilities, rural areas and emerging markets often struggle with inconsistent cellular coverage. This "connectivity gap" limits the reliability of telematics services that require constant cloud access, such as real-time navigation and emergency response. For global OEMs, designing a telematics solution that functions optimally across these disparate environments requires significant hardware flexibility and regional customization.
Additionally, the automotive industry faces a continuous challenge in managing the lifecycle of telematics hardware versus software. Vehicle lifespans typically range from 10 to 15 years, whereas telematics hardware and communication standards (like 2G/3G sunsets) evolve much faster. This leads to technological obsolescence where older vehicles lose connectivity features because the underlying network is no longer supported. Solving this through modular hardware or long-term software support remains a complex logistical and financial challenge for manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Network Sunsetting (2G/3G phase-outs) | -1.5% | Global (Legacy Fleets) | 2025-2028 |
| Fragmented Regional Connectivity Infrastructure | -2.0% | MEA, LAMEA, Rural APAC | 2025-2034 |
| Hardware Obsolescence vs. Vehicle Longevity | -1.3% | Global | 2025-2034 |
Automotive Embedded Telematic Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the embedded telematics ecosystem, focusing on factory-fitted solutions within passenger and commercial vehicles. It covers the entire value chain from component suppliers (semiconductors, modems, sensors) to Telematics Service Providers (TSPs) and end-use applications. The analysis provides deep insights into regional regulatory landscapes, technological shifts from 4G to 5G, and the impact of the Software-Defined Vehicle trend on market dynamics. Forecasts are based on a synthesis of automotive production data, connectivity penetration rates, and macroeconomic indicators across major global markets.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 58.42 Billion |
| Market Forecast in 2034 | USD 185.35 Billion |
| Growth Rate | 13.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Harman International (Samsung), Magneti Marelli C.K.P., Visteon Corporation, Airbiquity Inc., Octo Telematics, Geotab Inc., Verizon Connect, TomTom International BV, Qualcomm Technologies, Mix Telematics, Sierra Wireless, Panasonic Corporation, Valeo, Aptiv PLC, Trimble Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented primarily by solution, which dictates the functional utility of the telematics system. The safety and security segment leads the market, driven by emergency response mandates and anti-theft tracking features. Infotainment and navigation follow closely, representing the most visible consumer-facing aspect of telematics. Remote diagnostics is an emerging high-growth segment as OEMs look to reduce warranty costs and improve vehicle reliability through proactive monitoring. Fleet management continues to dominate the commercial vehicle sector, providing essential tools for logistics efficiency and regulatory compliance regarding driver hours.
- By Solution:
- Safety and Security (eCall, Roadside Assistance, Stolen Vehicle Tracking)
- Infotainment and Navigation (Real-time traffic, Cloud-based apps)
- Remote Diagnostics (Engine health monitoring, Prognostics)
- Fleet Management (Route optimization, Fuel monitoring, ELD compliance)
- By Component:
- Hardware (Telematics Control Units (TCU), Antennae, Microcontrollers)
- Software (Cloud platforms, Embedded OS, Cybersecurity layers)
- Services (Subscription services, Professional services)
- By Vehicle Type:
- Passenger Cars (Sedans, SUVs, Luxury segments)
- Light Commercial Vehicles (Vans, Pickup trucks)
- Heavy Commercial Vehicles (Long-haul trucks, Buses)
Regional Highlights
- North America: The largest market share holder, characterized by a high concentration of premium vehicles and advanced TSPs like Verizon Connect and Geotab. The US market is highly mature with a strong focus on data monetization and UBI.
- Europe: Driven by strict regulatory frameworks such as the eCall mandate. Countries like Germany and the UK are at the forefront of V2X testing and smart infrastructure development.
- Asia Pacific: The fastest-growing region. China is the primary engine of growth, supported by aggressive 5G rollouts and a massive domestic automotive industry. Japan and South Korea are leaders in high-end telematics hardware and sensor technology.
- Latin America: Growth is primarily driven by vehicle security and anti-theft mandates in countries like Brazil. The market is transitioning from basic tracking to more comprehensive telematics solutions.
- Middle East & Africa: Emerging opportunities in the GCC countries for smart city initiatives and logistics optimization, while Africa shows growth in fleet management for the mining and transport sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Embedded Telematic Market.- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Harman International (Samsung)
- Magneti Marelli C.K.P.
- Visteon Corporation
- Airbiquity Inc.
- Octo Telematics
- Geotab Inc.
- Verizon Connect
- TomTom International BV
- Qualcomm Technologies
- Mix Telematics
- Sierra Wireless
- Panasonic Corporation
- Valeo
- Aptiv PLC
- Trimble Inc.
- Intel Corporation
- AT&T Inc.
Frequently Asked Questions
What is driving the growth of the Automotive Embedded Telematic Market?
Growth is primarily driven by government safety mandates (like eCall in Europe and AIS-140 in India), the rapid expansion of 5G connectivity, and increasing consumer demand for connected car features like real-time navigation and OTA updates.
Which region is expected to lead the market in terms of growth rate?
The Asia Pacific region is expected to experience the highest CAGR due to massive vehicle production, rapid 5G infrastructure deployment, and government support for connected and autonomous vehicle technologies, particularly in China.
How does 5G impact the Automotive Embedded Telematic market?
5G significantly reduces latency and increases bandwidth, enabling real-time V2X (Vehicle-to-Everything) communication, more reliable autonomous driving functions, and faster Over-the-Air software updates, which are essential for Software-Defined Vehicles.
What are the main cybersecurity concerns in this market?
Main concerns include the risk of remote vehicle hacking, unauthorized access to sensitive location data, and potential manipulation of safety-critical systems, prompting the industry to adopt rigorous cybersecurity standards like ISO/SAE 21434.
What is the difference between embedded and aftermarket telematics?
Embedded telematics are integrated into the vehicle by the OEM during manufacturing, offering better system integration and reliability. Aftermarket telematics are plug-and-play devices installed later, often used for older vehicle fleets or simpler tracking needs.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
