Automotive Data Logger Market
Automotive Data Logger Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711306 | Published On : October 25, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Data Logger Market Size
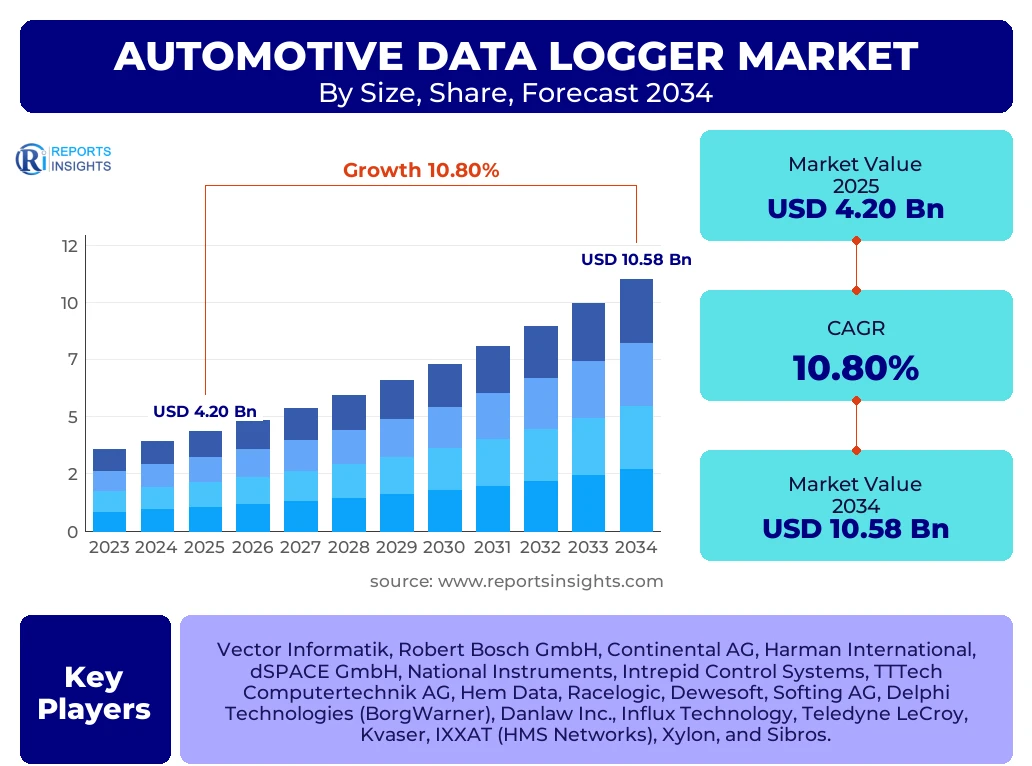
According to Reports Insights Consulting Pvt Ltd, The Automotive Data Logger Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 10.8% between 2025 and 2034. The market is estimated at USD 4.65 Billion in 2026 and is projected to reach USD 10.58 Billion by the end of the forecast period in 2034.
Key Automotive Data Logger Market Trends & Insights
The global automotive data logger market is undergoing a significant transformation driven by the rapid evolution of vehicle architectures toward software-defined vehicles and the increasing complexity of electronic control units. Market insights reveal a growing demand for high-performance logging solutions capable of handling massive data throughput from advanced sensors, including LiDAR, Radar, and high-resolution cameras. Regional analysis indicates that while North America remains a significant hub for research and development, the Asia-Pacific region is emerging as the most dynamic market due to large-scale automotive production and the aggressive adoption of electric vehicles in China. Competitive benchmarking shows that key players are increasingly focusing on integrated cloud-based logging solutions and real-time remote monitoring capabilities to support the development of Level 4 and Level 5 autonomous driving systems.
- Largest Region: North America currently holds the largest market share due to the early adoption of advanced driver assistance systems and the presence of major technology giants focused on autonomous mobility.
- Fastest Growing Region: Asia-Pacific is identified as the fastest-growing region, fueled by rising vehicle production, government incentives for electric vehicles, and expanding infrastructure for connected cars in China, India, and South Korea.
- Leading Segment by Application: The Advanced Driver Assistance Systems (ADAS) and Autonomous Driving segment represents the largest share, as these systems require high-capacity logging for validation and testing.
- Rising Technology Trend: The transition from traditional CAN and LIN protocols to Automotive Ethernet is driving the development of next-generation data loggers with multi-gigabit bandwidth capabilities.
- Cloud Integration: There is a notable trend toward hybrid logging architectures where critical data is logged locally while telemetry and diagnostic metadata are uploaded to the cloud for real-time fleet analysis.
Key Takeaways Automotive Data Logger Market Size & Forecast
The automotive data logger market is set for robust growth as the industry shifts toward electrified and automated platforms. Analysis of user inquiries suggests a high level of interest in the scalability of logging solutions for massive data volumes and the regulatory requirements for data recording in autonomous systems. The forecast period highlights a steady upward trajectory, underpinned by the mandatory inclusion of event data recorders in several jurisdictions and the increasing reliance on real-time diagnostics for fleet management. Market stakeholders are prioritizing modularity and cross-protocol compatibility to ensure that data loggers can remain functional across diverse vehicle models and evolving communication standards.
- Primary Growth Catalyst: The surge in demand for autonomous vehicle testing and validation is the single most significant factor driving the market forecast toward the USD 10.58 billion mark by 2034.
- Dominant Country: The United States leads in value contribution, supported by a robust ecosystem of Tier-1 suppliers and autonomous vehicle startups requiring sophisticated testing equipment.
- Technological Shift: The move toward 48V vehicle architectures and the integration of Zonal Architecture are necessitating more sophisticated data logging tools that can handle decentralized data streams.
- Market Stability: Despite economic fluctuations, the research and development budgets of major OEMs for safety and automation remain resilient, providing a stable foundation for the data logger market.
- Regulatory Influence: Global safety mandates, such as the UN R157 for Automated Lane Keeping Systems, are forcing manufacturers to adopt specialized data logging hardware for legal compliance and accident reconstruction.
Automotive Data Logger Market Drivers Analysis
The market is primarily driven by the escalating complexity of vehicle electronics and the necessity for rigorous testing of safety-critical systems. As vehicles integrate more sensors and software code, the probability of system errors increases, making high-fidelity data logging essential for post-capture analysis and debugging. Furthermore, the global push toward electrification requires specialized logging for battery management systems and power electronics, while the expansion of connected car services necessitates tools that can monitor V2X communications. These factors collectively push the demand for versatile, high-bandwidth logging solutions across the automotive value chain.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Penetration of ADAS and Autonomous Driving | +4.2% | Global (Strongest in US & Germany) | 2025-2034 |
| Expansion of Electric Vehicle (EV) Ecosystems | +3.1% | China, Europe, India | 2025-2030 |
| Regulatory Mandates for Event Data Recorders (EDR) | +2.5% | North America, European Union | 2025-2028 |
| Transition to High-Speed Automotive Ethernet | +1.0% | Japan, South Korea, US | 2026-2034 |
Automotive Data Logger Market Restraints Analysis
Despite strong growth drivers, the market faces significant hurdles related to the high cost of advanced hardware and the challenges of managing the sheer volume of data generated during testing. High-performance loggers with multi-terabyte storage and high-speed interfaces involve substantial capital expenditure, which can be a barrier for smaller component manufacturers and startups. Additionally, the lack of standardized data formats across different OEMs can lead to interoperability issues, complicating the data analysis workflow and increasing the total cost of ownership for logging systems.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Procurement and Maintenance Costs | -1.8% | Emerging Markets (ASEAN, Latin America) | 2025-2034 |
| Data Privacy and Cybersecurity Regulations | -1.2% | European Union (GDPR Compliance) | 2025-2030 |
| Interoperability Challenges and Lack of Standards | -0.9% | Global | 2026-2029 |
Automotive Data Logger Market Opportunities Analysis
The shift toward remote diagnostics and over-the-air (OTA) updates presents a significant opportunity for market players to develop cloud-integrated data logging solutions. By enabling engineers to monitor vehicle performance in real-world conditions remotely, these tools can drastically reduce the time and cost associated with field testing. Additionally, the emergence of Artificial Intelligence and Machine Learning for automated data labeling and anomaly detection creates a new niche for software-enhanced logging platforms that can provide actionable insights rather than just raw data.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Driven Data Analytics and Automated Labeling | +2.8% | USA, China, Israel | 2027-2034 |
| Integration with V2X and Smart City Infrastructure | +1.5% | China, South Korea, Japan | 2028-2034 |
| Expansion in Commercial Fleet Management Services | +1.2% | Global (Focus on Logistics Hubs) | 2025-2034 |
Automotive Data Logger Market Challenges Impact Analysis
The primary challenge for the automotive data logger market is keeping pace with the exponential growth in vehicle data rates while maintaining hardware reliability in harsh automotive environments. As vehicles move toward Level 3 and Level 4 autonomy, the data throughput requirements are exceeding the capabilities of traditional storage media and bus interfaces. Ensuring thermal stability and shock resistance for loggers that must operate for long durations in prototype vehicles remains a persistent technical challenge for manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Scaling Storage Capacity for High-Resolution Sensors | -1.5% | Global OEM R&D Centers | 2025-2030 |
| Hardware Durability in Extreme Environmental Conditions | -0.8% | Global (Cold/Hot Weather Testing) | 2025-2034 |
| Complexity of Multi-Protocol Synchronization | -1.1% | Germany, USA, Japan | 2026-2031 |
Automotive Data Logger Market - Updated Report Scope
This comprehensive market report provides a deep-dive analysis of the global automotive data logger industry, covering hardware architectures, software integration, and the evolving competitive landscape. The scope includes an assessment of various communication protocols, application areas from R&D to fleet management, and a detailed regional breakdown that identifies growth pockets across five major continents. The report also examines the impact of emerging technologies like 5G and Edge Computing on the future of data acquisition in the automotive sector.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.20 Billion |
| Market Forecast in 2034 | USD 10.58 Billion |
| Growth Rate | 10.8% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Vector Informatik, Robert Bosch GmbH, Continental AG, Harman International, dSPACE GmbH, National Instruments, Intrepid Control Systems, TTTech Computertechnik AG, Hem Data, Racelogic, Dewesoft, Softing AG, Delphi Technologies (BorgWarner), Danlaw Inc., Influx Technology, Teledyne LeCroy, Kvaser, IXXAT (HMS Networks), Xylon, and Sibros. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on the specific technical requirements of modern vehicle development and operation. The ADAS and Autonomous driving segment is the primary engine of growth, requiring massive data storage and high-speed logging for validation. From a protocol perspective, while CAN FD remains the workhorse for modern vehicle buses, the rapid adoption of Automotive Ethernet is creating a high-value niche for sophisticated loggers capable of handling gigabit speeds. End-user analysis shows that while OEMs remain the largest purchasers, Tier 1 suppliers are increasing their investments in data logging to validate the complex subsystems they provide to vehicle manufacturers.
- By Application:
- ADAS & Autonomous Driving: Validation of sensing and decision-making algorithms.
- Fleet Management: Monitoring driver behavior and vehicle health for logistics.
- Vehicle Diagnostics: Post-market troubleshooting and warranty analysis.
- Powertrain & Battery Testing: Essential for EV battery management system (BMS) optimization.
- By Channels:
- CAN & CAN FD: The most widely used standard for powertrain and chassis.
- LIN: Used for low-speed body electronics.
- FlexRay: High-speed, deterministic bus for safety-critical systems like steer-by-wire.
- Automotive Ethernet: Growing segment for high-bandwidth data requirements.
- By Connection Type:
- Wired Logging: Preferred for high-stability R&D testing.
- Wireless Logging: Increasing adoption for real-world fleet testing and remote monitoring.
- By End-Use:
- OEMs: Direct vehicle development and production testing.
- Tier 1 Suppliers: Component-level validation and integration testing.
- Service Centers & Fleet Operators: Operational monitoring and maintenance.
Regional Highlights
- North America: The region is the global leader in market value, driven by the presence of autonomous driving pioneers in Silicon Valley and major OEMs in Detroit. The US market is characterized by high investment in Level 4 autonomy and advanced V2X infrastructure projects.
- Europe: Germany is the epicenter of the European market, with companies like Bosch, Continental, and Vector Informatik leading the way. The region's strict safety regulations and focus on the "Vision Zero" initiative for road safety drive the high adoption of data loggers for ADAS validation.
- Asia-Pacific: This is the fastest-growing region, dominated by China’s massive EV market and Japan’s expertise in automotive electronics. India is also emerging as a significant market for fleet management loggers due to the modernization of its logistics sector.
- Latin America: The market is steadily growing, primarily driven by the expansion of automotive manufacturing clusters in Mexico and Brazil, which serve as export hubs for North American and European markets.
- Middle East & Africa: Growth is largely focused on smart city initiatives in the GCC countries, where autonomous shuttle testing and high-end vehicle telematics are gaining traction.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Data Logger Market. these companies are ranked based on their technological innovation, product portfolio breadth, and global market presence.
- Vector Informatik GmbH
- Robert Bosch GmbH
- Continental AG
- Harman International (Samsung Electronics)
- dSPACE GmbH
- National Instruments (Emerson)
- Intrepid Control Systems, Inc.
- TTTech Computertechnik AG
- Hem Data Corporation
- Racelogic Ltd
- Dewesoft d.o.o.
- Softing Automotive Electronics GmbH
- BorgWarner Inc. (Delphi Technologies)
- Danlaw Inc.
- Influx Technology
- Teledyne LeCroy
- Kvaser AB
- HMS Networks (IXXAT)
- Xylon d.o.o.
- Sibros Technologies, Inc.
Frequently Asked Questions
What is the current market size of the Automotive Data Logger market?
The Automotive Data Logger market is estimated at USD 4.20 Billion in 2025 and is projected to reach approximately USD 10.58 Billion by 2034, growing at a CAGR of 10.8%.
Which factors are driving the growth of the Automotive Data Logger market?
Key drivers include the rising complexity of vehicle electronics, the proliferation of ADAS and autonomous driving systems, the expansion of the EV market, and regulatory mandates for event data recording.
Who are the leading players in the Automotive Data Logger industry?
Leading companies include Vector Informatik, Bosch, Continental, dSPACE, and National Instruments, who dominate the market through constant innovation in high-speed data acquisition hardware.
Which region is expected to show the highest growth rate during the forecast period?
The Asia-Pacific region is expected to exhibit the highest CAGR due to rapid urbanization, significant investments in EV manufacturing, and the growing presence of tech-savvy automotive consumers in China and India.
What role does Automotive Ethernet play in the data logger market?
Automotive Ethernet is a critical growth segment because it provides the necessary bandwidth for high-resolution sensor data, requiring a new generation of loggers capable of capturing and time-stamping gigabit data streams.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
