Automotive Adhesives Sealants Market
Automotive Adhesives Sealants Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711510 | Published On : November 04, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Adhesives Sealants Market Size
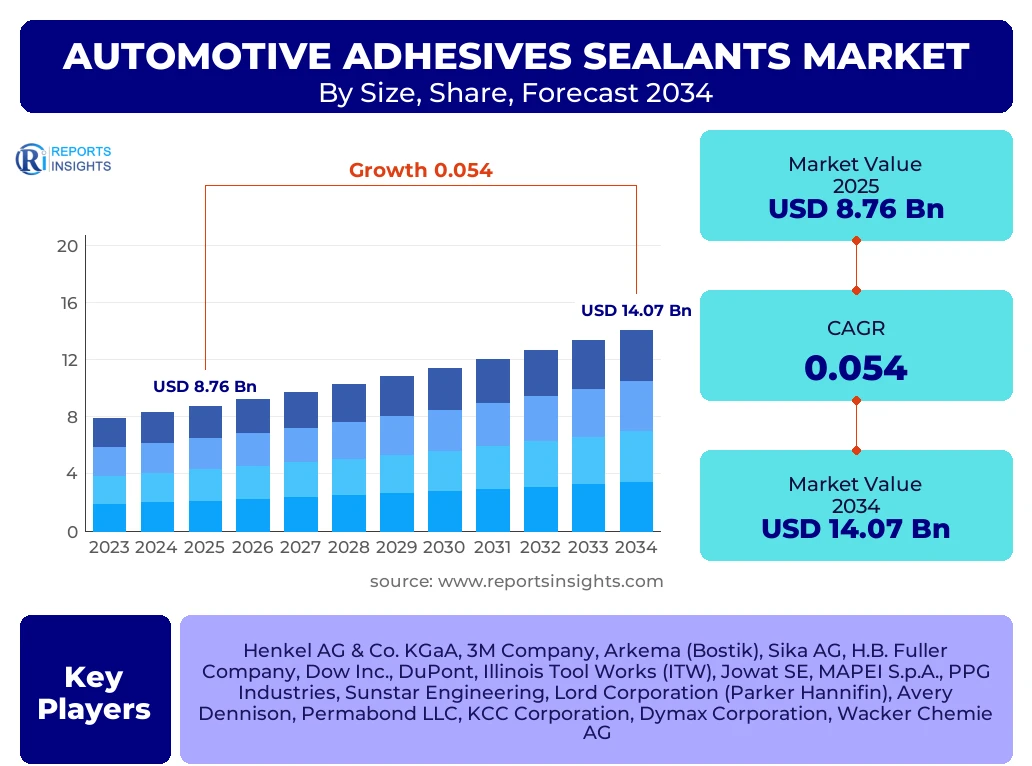
According to Reports Insights Consulting Pvt Ltd, The Automotive Adhesives Sealants Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 9.24 Billion in 2026 and is projected to reach USD 14.07 Billion by the end of the forecast period in 2034.
The global automotive industry is undergoing a paradigm shift, transitioning from traditional internal combustion engine (ICE) vehicles to electric vehicles (EVs) and autonomous platforms. This transition is a primary catalyst for the automotive adhesives and sealants market. As manufacturers strive to increase fuel efficiency and extend the range of electric batteries, the reliance on lightweight materials such as carbon fiber reinforced plastics (CFRP), aluminum, and advanced high-strength steels has intensified. These materials often cannot be joined effectively through traditional welding or mechanical fastening, necessitating high-performance structural adhesives that distribute stress evenly and prevent galvanic corrosion.
The integration of advanced electronic components and sensors in modern vehicles further boosts the demand for specialized sealants. These materials provide essential protection against environmental ingress, vibration, and thermal fluctuations, ensuring the longevity of sensitive ADAS (Advanced Driver Assistance Systems) hardware. Furthermore, the push for enhanced cabin acoustics and passenger comfort has led to the widespread adoption of acoustic sealants and dampening materials, reinforcing the market growth trajectory through 2034.
Key Automotive Adhesives Sealants Market Trends & Insights
The automotive adhesives and sealants market is characterized by a significant move toward sustainable formulations and high-performance structural bonding. Current market intelligence indicates that stakeholders are prioritizing the development of bio-based resins and low-VOC (Volatile Organic Compound) products to comply with stringent environmental regulations such as REACH in Europe. Additionally, the rapid expansion of the EV infrastructure is driving a surge in demand for thermal management adhesives used in battery pack assembly, which require unique properties such as high thermal conductivity coupled with electrical insulation.
- Largest Region: Asia-Pacific remains the dominant market shareholder, driven by massive vehicle production volumes in China, India, and Japan, alongside a rapidly maturing EV ecosystem.
- Fastest Growing Region: North America is poised for the highest growth rate during the forecast period due to the aggressive domestic manufacturing of electric SUVs and trucks requiring advanced bonding solutions.
- Largest Segment by Resin: Polyurethane adhesives continue to hold the largest market share due to their exceptional versatility, flexibility, and strong adhesion to various substrates.
- Leading Application: The Body-in-White (BIW) segment leads in terms of volume consumption as structural adhesives replace hundreds of spot welds in modern vehicle frames.
- Emerging Trend: The adoption of Pressure Sensitive Adhesives (PSAs) for interior trim and electronic component mounting is rising due to ease of application and weight reduction.
Key Takeaways Automotive Adhesives Sealants Market Size & Forecast
The forecast period from 2025 to 2034 highlights a steady upward trajectory, underpinned by the structural evolution of vehicle architecture. As OEMs (Original Equipment Manufacturers) move away from heavy mechanical fasteners, the role of adhesives has evolved from secondary joining methods to critical structural components. This shift is particularly evident in the premium and luxury vehicle segments, where composite materials are used extensively to reduce curb weight without compromising safety or structural integrity.
- Leading Country: China is the single largest consumer and producer of automotive adhesives, accounting for over 30 percent of the global volume.
- EV Impact: Electric vehicles utilize approximately 2 to 3 times more adhesive and sealant material by volume compared to traditional ICE vehicles, primarily for battery assembly and thermal management.
- Regulatory Influence: Global mandates for CO2 emission reduction are forcing OEMs to adopt lightweighting strategies, which is the primary long-term driver for structural adhesive adoption.
- Material Innovation: The development of "smart" adhesives with self-healing properties or those that allow for easier disassembly (debonding on demand) is gaining traction for circular economy initiatives.
- Market Maturity: While mature in Europe and North America, the market is seeing a shift toward high-value specialty chemicals rather than bulk commodity products.
Automotive Adhesives Sealants Market Drivers Analysis
The primary growth engine for this market is the global obsession with vehicle lightweighting to meet corporate average fuel economy (CAFE) standards and maximize EV range. By replacing heavy bolts, nuts, and welds with high-strength adhesives, manufacturers can shave significant weight from the chassis while simultaneously improving the vehicle's stiffness and crash performance.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift toward Lightweight Materials (Alm/Composites) | +1.8% | Global (Focus on EU & NA) | 2025-2034 |
| Rising Production of Electric and Hybrid Vehicles | +2.1% | China, Germany, USA | 2025-2034 |
| Advancements in Crash Safety Regulations | +0.9% | Global | 2026-2030 |
| Growth in Automotive Electronics and ADAS Integration | +0.6% | Japan, South Korea, Taiwan | 2025-2034 |
Automotive Adhesives Sealants Market Restraints Analysis
Despite robust demand, the market faces headwinds from the volatility of raw material prices, particularly those derived from petrochemicals. Furthermore, the high cost of advanced adhesive dispensing equipment and the specialized training required for application in automated assembly lines pose significant barriers for smaller manufacturers in developing economies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Petrochemical Feedstock Prices | -0.8% | Global | 2025-2028 |
| Strict Environmental Regulations on VOC Emissions | -0.5% | Europe (REACH), North America | 2025-2034 |
| High Initial Investment in Automated Dispensing Systems | -0.4% | India, Southeast Asia, Brazil | 2026-2032 |
Automotive Adhesives Sealants Market Opportunities Analysis
The most promising opportunities lie in the development of sustainable and circular economy-friendly products. As the industry faces pressure to improve recyclability, adhesives that can be "de-bonded" using heat or UV light are becoming highly sought after. Additionally, the aftermarket for vehicle repair and maintenance offers a consistent revenue stream as vehicles become more complex and require specialized repair adhesives.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bio-based and Eco-friendly Adhesive Formulations | +1.2% | Western Europe, Scandinavia | 2027-2034 |
| Thermal Management Solutions for Battery Packs | +1.5% | China, USA, South Korea | 2025-2034 |
| Expansion of Aftermarket in Emerging Economies | +0.7% | India, ASEAN, Mexico | 2028-2034 |
Automotive Adhesives Sealants Market Challenges Impact Analysis
Technical challenges remain a hurdle, particularly the need for adhesives that can cure quickly at room temperature without compromising bond strength. In a high-speed automotive assembly environment, "tack-free" and "full-cure" times are critical metrics. Balancing fast processing speeds with the ability to bond dissimilar materials with different thermal expansion coefficients is a persistent engineering challenge.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Managing Differential Thermal Expansion in Dissimilar Materials | -0.6% | Global (Advanced Manufacturing) | 2025-2034 |
| Achieving Rapid Cure Times in Automated Production Lines | -0.5% | Japan, Germany, USA | 2025-2030 |
| Counterfeit and Substandard Products in Aftermarket | -0.3% | Asia-Pacific, Latin America | 2025-2034 |
Automotive Adhesives Sealants Market - Updated Report Scope
This comprehensive market analysis encompasses the entire value chain of the automotive adhesives and sealants industry, from raw material suppliers to end-use vehicle manufacturers. The scope includes a detailed breakdown of chemical resin types, technological application methods, and specific automotive subsystems where these materials are deployed. It covers passenger cars, light commercial vehicles (LCVs), and heavy commercial vehicles (HCVs), with a specialized focus on the burgeoning electric vehicle segment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 8.76 Billion |
| Market Forecast in 2034 | USD 14.07 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Henkel AG & Co. KGaA, 3M Company, Arkema (Bostik), Sika AG, H.B. Fuller Company, Dow Inc., DuPont, Illinois Tool Works (ITW), Jowat SE, MAPEI S.p.A., PPG Industries, Sunstar Engineering, Lord Corporation (Parker Hannifin), Avery Dennison, Permabond LLC, KCC Corporation, Dymax Corporation, Wacker Chemie AG |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on chemical composition and application technology to reflect the diverse needs of automotive engineering. Polyurethane remains the workhorse of the industry due to its balance of strength and elongation, while epoxies are preferred for high-stress structural joints. The shift toward solvent-free technologies like hot melts and water-based systems reflects the industry's commitment to reducing environmental impact and improving worker safety on the assembly line.
- By Resin Type:
- Polyurethane: Leading segment used for windshield bonding and structural reinforcement.
- Epoxy: High-strength resins used primarily in BIW and structural components.
- Acrylic: Fast-curing adhesives used for interior trim and small component bonding.
- Silicone: High-temperature resistant materials used in gaskets and engine components.
- Silyl Modified Polymer (SMP): Gaining popularity for its UV resistance and primer-less adhesion.
- By Technology:
- Hot Melt: Preferred for interior assembly due to rapid set times.
- Water-based: Growing in the trim and upholstery segment due to low VOCs.
- Solvent-based: Declining in share but still used in specialized exterior applications.
- Pressure Sensitive: Used for decals, emblems, and NVH (Noise, Vibration, Harshness) materials.
- By Application:
- Body-in-White (BIW): The largest application area involving structural bonding of the frame.
- Powertrain: Sealing of engines, transmissions, and cooling systems.
- Paint Shop: Use of seam sealants to prevent moisture ingress and corrosion.
- Electronics: Potting and sealing of ECUs, sensors, and battery modules.
Regional Highlights
- Asia-Pacific: The undisputed leader in market share, Asia-Pacific is fueled by the massive production hubs of China and India. China’s aggressive subsidies for "New Energy Vehicles" (NEVs) have created a specialized market for high-tech adhesives used in battery manufacturing.
- North America: This region is characterized by a strong presence of major OEMs and a high demand for SUVs and heavy-duty trucks. The regional market is currently the fastest-growing due to a localized push for EV battery "gigafactories" and the resurgence of domestic manufacturing.
- Europe: Europe is the epicenter of regulatory-driven innovation. With the world's strictest VOC and recycling mandates, European manufacturers lead the development of bio-based adhesives and sustainable bonding technologies. Germany remains the primary contributor within the region.
- Latin America: Brazil and Mexico are the key pillars of the automotive industry in this region. Growth is driven by the presence of export-oriented manufacturing plants for North American and European brands.
- Middle East & Africa: A developing market focusing on automotive assembly and aftermarket services. South Africa remains the most significant industrial player in this geography.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Adhesives Sealants Market.- Henkel AG & Co. KGaA
- 3M Company
- Arkema (Bostik)
- Sika AG
- H.B. Fuller Company
- Dow Inc.
- DuPont
- Illinois Tool Works (ITW)
- Jowat SE
- MAPEI S.p.A.
- PPG Industries
- Sunstar Engineering
- Lord Corporation (Parker Hannifin)
- Avery Dennison
- Permabond LLC
- KCC Corporation
- Dymax Corporation
- Wacker Chemie AG
- Yokohama Industries
- ThreeBond Holdings Co., Ltd.
Frequently Asked Questions
What is driving the growth of the Automotive Adhesives Sealants Market in electric vehicles?
The growth is primarily driven by the need for thermal management and battery pack sealing. EVs require specialized adhesives to manage heat dissipation while providing electrical insulation and structural integrity for heavy battery modules. Additionally, lightweighting is more critical in EVs to offset battery weight and extend range.
How do adhesives contribute to vehicle safety?
Structural adhesives improve crashworthiness by providing continuous bonding along seams, which distributes impact forces more evenly than spot welds. They also enhance the overall torsional stiffness of the vehicle, leading to better handling and structural durability over the vehicle's lifespan.
Which resin type is expected to dominate the market by 2034?
Polyurethane is expected to maintain the highest volume share due to its versatility and cost-effectiveness. However, Epoxy resins are projected to see the highest value-based growth due to their critical role in structural multi-material bonding and EV battery assemblies.
What are the environmental concerns regarding automotive sealants?
The primary concern is the emission of Volatile Organic Compounds (VOCs) during the curing process. This has led to a major industry shift toward water-based, hot melt, and 100% solid formulations to comply with global environmental standards like REACH and EPA regulations.
How is the "Right to Repair" movement affecting this market?
The movement is driving demand in the aftermarket for specialized, high-quality repair adhesives that allow independent shops to maintain the structural integrity of vehicles. It also encourages manufacturers to provide clearer guidelines on adhesive-based repairs versus traditional mechanical fixes.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
