Artificial Intelligence Oncology Market
Artificial Intelligence Oncology Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711139 | Published On : October 11, 2026 |
Format : 


 | Author : Erika Grotto
Artificial Intelligence Oncology Market Size
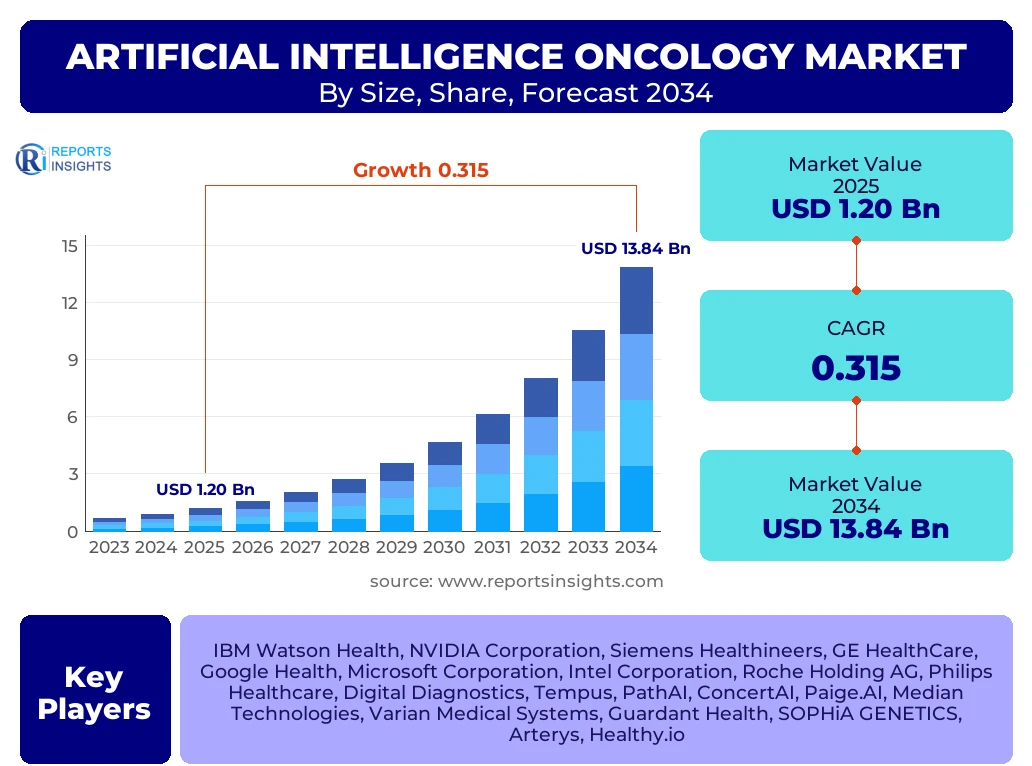
According to Reports Insights Consulting Pvt Ltd, The Artificial Intelligence Oncology Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 31.5% between 2025 and 2034. The market is estimated at USD 1.58 Billion in 2026 and is projected to reach USD 13.84 Billion by the end of the forecast period in 2034.
Key Artificial Intelligence Oncology Market Trends & Insights
The integration of artificial intelligence in oncology is undergoing a paradigm shift, transitioning from experimental research tools to standardized clinical decision support systems. One of the most significant trends is the convergence of multi-omics data with radiomics. By synthesizing genomic sequencing data with high-resolution medical imaging, AI algorithms are now capable of predicting patient responses to specific immunotherapy treatments with unprecedented accuracy. This holistic approach allows oncologists to move beyond reactive care toward highly personalized, predictive treatment regimens. Furthermore, the rise of federated learning is enabling institutions to train robust AI models on diverse, decentralized datasets without compromising patient privacy, addressing one of the primary hurdles in medical data sharing.
Market dynamics are also being shaped by the increasing adoption of cloud-based AI platforms that offer scalability to smaller diagnostic centers. The shift toward value-based healthcare is incentivizing providers to implement AI tools that reduce diagnostic errors and optimize resource allocation. As regulatory bodies like the FDA and EMA continue to refine pathways for Software as a Medical Device (SaMD), the speed of commercialization for oncology-specific AI applications has accelerated. Competitive benchmarking reveals that leading tech giants are increasingly collaborating with biopharmaceutical firms to shorten drug discovery timelines for orphan cancers, creating a high-barrier-to-entry ecosystem focused on specialized diagnostic precision.
- North America currently stands as the largest regional market, driven by high R&D investment and a robust digital healthcare infrastructure.
- The Asia-Pacific region is recognized as the fastest-growing market, attributed to rapid digital transformation in healthcare across China, India, and Japan.
- The Diagnostics and Imaging segment holds the largest market share, as AI-powered radiology tools are the most mature applications in the clinical setting.
- Breast cancer and Lung cancer represent the largest application segments due to the high global prevalence and the critical need for early-stage detection.
Key Takeaways Artificial Intelligence Oncology Market Size & Forecast
The global trajectory of the AI oncology market is defined by a massive influx of venture capital and strategic acquisitions by established medical technology firms. Stakeholders are increasingly focusing on the long-term cost-savings associated with early cancer detection and the reduction of unnecessary biopsies. Forecast models indicate that the service-based component of the market will see substantial growth as healthcare providers require ongoing technical support, algorithm retraining, and integration services. The market is expected to witness a consolidation phase where niche AI startups are absorbed by diversified healthcare conglomerates to create end-to-end oncological care platforms.
- The global market value is set to surpass the 10-billion-dollar milestone by 2032, reflecting a decade of hyper-growth.
- The United States remains the leading country in terms of value, supported by favorable reimbursement policies for AI-assisted diagnostic procedures.
- Precision medicine initiatives are the primary catalyst for market expansion, moving the industry toward patient-specific therapeutic targeting.
- Cloud-based deployment models are preferred by over 65% of new healthcare adopters due to lower upfront infrastructure costs.
Artificial Intelligence Oncology Market Drivers Analysis
The primary drivers for the AI oncology market include the escalating global cancer burden and the acute shortage of specialized oncologists and pathologists. AI acts as a force multiplier, allowing medical professionals to process vast amounts of data—such as pathology slides and MRI scans—in a fraction of the time required for manual review. Additionally, the increasing complexity of genomic data necessitates automated analytical tools that can identify rare mutations and correlate them with clinical outcomes, a task that has become humanly impossible at scale.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Precision Medicine Adoption | +8.5% | Global (Strongest in US & Germany) | 2025 - 2034 |
| Rising Cancer Prevalence & Early Detection Needs | +7.2% | APAC and Latin America | 2025 - 2030 |
| Advancements in Deep Learning for Medical Imaging | +6.8% | Global | 2025 - 2034 |
| Strategic Partnerships in Drug Discovery | +5.4% | UK, Switzerland, USA | 2026 - 2034 |
Artificial Intelligence Oncology Market Restraints Analysis
Despite the rapid growth, the market faces significant restraints related to data silos and the lack of interoperability between different Electronic Health Record (EHR) systems. Furthermore, the "black box" nature of some deep learning algorithms creates skepticism among clinicians regarding the explainability and transparency of AI-driven recommendations. High implementation costs and the need for significant capital expenditure for high-performance computing hardware also deter adoption in low-to-middle-income countries.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory and Compliance Hurdles | -4.2% | European Union (GDPR/AI Act) | 2025 - 2028 |
| Data Privacy and Security Concerns | -3.5% | Global | 2025 - 2034 |
| Lack of Standardized High-Quality Datasets | -2.8% | Global | 2025 - 2030 |
Artificial Intelligence Oncology Market Opportunities Analysis
The emergence of AI-driven drug repurposing presents a massive opportunity for pharmaceutical companies to find new indications for existing oncology drugs, significantly reducing R&D costs and time-to-market. Additionally, there is a growing opportunity in the development of AI tools for rural and underserved areas where access to expert oncologists is limited. Real-world evidence (RWE) generation through AI-monitored clinical trials is another burgeoning field that promises to enhance the efficiency of post-market surveillance and therapeutic optimization.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion in Emerging Economies (China, India, Brazil) | +9.1% | APAC, LATAM | 2027 - 2034 |
| AI-Integrated Liquid Biopsy Technologies | +7.5% | USA, Japan, Israel | 2026 - 2034 |
| Personalized Patient Monitoring and Care Apps | +5.2% | Global | 2025 - 2034 |
Artificial Intelligence Oncology Market Challenges Impact Analysis
One of the most critical challenges is the risk of algorithmic bias, where AI models trained on homogenous populations may not perform accurately for diverse ethnic groups. Integration with legacy hospital workflows and the resistance to change among medical staff also pose significant hurdles. Furthermore, the legal and ethical implications of AI errors in diagnosis create a complex liability landscape that remains largely unresolved in many jurisdictions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Algorithmic Bias and Generalizability Issues | -3.1% | Global | 2025 - 2034 |
| High Talent Gap for AI in Healthcare | -2.4% | Global | 2025 - 2030 |
Artificial Intelligence Oncology Market - Updated Report Scope
This report provides a comprehensive analysis of the global Artificial Intelligence Oncology landscape, covering technological advancements, regulatory frameworks, and competitive strategies. The scope encompasses software solutions, hardware infrastructure, and professional services across multiple cancer types and clinical applications. The analysis is built upon a foundation of statistical modeling and industry expert consultations to provide an accurate roadmap of the market's evolution over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.20 Billion |
| Market Forecast in 2034 | USD 13.84 Billion |
| Growth Rate | 31.5% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | IBM Watson Health, NVIDIA Corporation, Siemens Healthineers, GE HealthCare, Google Health, Microsoft Corporation, Intel Corporation, Roche Holding AG, Philips Healthcare, Digital Diagnostics, Tempus, PathAI, ConcertAI, Paige.AI, Median Technologies, Varian Medical Systems, Guardant Health, SOPHiA GENETICS, Arterys, Healthy.io |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the AI oncology market reflects the diverse clinical and research applications of the technology. Software solutions dominate the component segment, as continuous updates and algorithm improvements are central to the value proposition. However, the hardware segment is witnessing significant investment in specialized GPUs and TPUs designed for deep learning. The application segment is currently led by diagnostics and imaging, but drug discovery is projected to be the fastest-growing sub-segment as pharmaceutical giants leverage AI to identify novel biomarkers and therapeutic targets.
- By Component:
- Software (Platform, Integrated, Standalone)
- Hardware (Processors, Memory, Network)
- Services (Installation, Maintenance, Training & Consulting)
- By Application:
- Medical Imaging and Diagnostics
- Treatment Planning and Personalized Medicine
- Drug Discovery and Development
- Clinical Trial Research
- Patient Monitoring and Management
- By Cancer Type:
- Breast Cancer
- Lung Cancer
- Prostate Cancer
- Colorectal Cancer
- Skin Cancer/Melanoma
- Leukemia and Lymphoma
- Other Solid Tumors
- By End-User:
- Hospitals and Clinics
- Diagnostic Laboratories
- Pharmaceutical and Biotechnology Companies
- Academic and Research Institutions
Regional Highlights
- North America: The largest market share holder, characterized by a high concentration of AI tech leaders and a favorable regulatory environment with numerous FDA approvals for AI diagnostic tools.
- Europe: A significant market driven by strong government support for digital health initiatives and a centralized approach to healthcare data through the European Health Data Space.
- Asia-Pacific: The fastest-growing region, with China leading in AI research publications and Japan making strides in integrating AI into its aging population’s oncology care framework.
- Latin America: Showing steady growth due to the expansion of healthcare infrastructure and increasing public-private partnerships for cancer screening programs.
- Middle East and Africa: A developing segment where AI is being utilized to bridge the gap in specialist availability and improve diagnostic accuracy in urban centers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Artificial Intelligence Oncology Market.- IBM Watson Health
- NVIDIA Corporation
- Siemens Healthineers
- GE HealthCare
- Google Health (Alphabet Inc.)
- Microsoft Corporation
- Intel Corporation
- Roche Holding AG
- Philips Healthcare
- Digital Diagnostics (IDx Technologies Inc.)
- Tempus
- PathAI
- ConcertAI
- Paige.AI
- Median Technologies
- Varian Medical Systems
- Guardant Health
- SOPHiA GENETICS
- Arterys
- Healthy.io
Frequently Asked Questions
What is the current market size and future growth projection for AI in oncology?
The market is estimated to be valued at approximately USD 1.20 Billion in 2025 and is projected to grow at a CAGR of 31.5%, reaching USD 13.84 Billion by 2034. This growth is fueled by the demand for precision medicine and early cancer detection tools.
Which cancer types are seeing the highest integration of AI technologies?
Breast cancer and lung cancer are the primary areas of AI integration. These types benefit significantly from AI-enhanced medical imaging for early screening and genomic profiling for targeted therapy selection.
How does AI contribute to cancer drug discovery?
AI accelerates drug discovery by identifying potential drug candidates, predicting their efficacy and toxicity, and uncovering new biomarkers for clinical trials. This reduces the time and cost associated with traditional pharmaceutical R&D.
What are the main barriers to adopting AI in oncology clinics?
The main barriers include concerns over data privacy, the high cost of initial implementation, a lack of standardized data across different health systems, and the clinical requirement for "explainable" AI models that physicians can trust.
Which region is expected to dominate the Artificial Intelligence Oncology market?
North America is expected to maintain the largest market share due to its advanced healthcare infrastructure and high R&D spending, while Asia-Pacific is projected to be the fastest-growing region through 2034.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
