Antisense Rnai Therapeutics Market
Antisense Rnai Therapeutics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710885 | Published On : September 14, 2026 |
Format : 


 | Author : Erika Grotto
Antisense Rnai Therapeutics Market Size
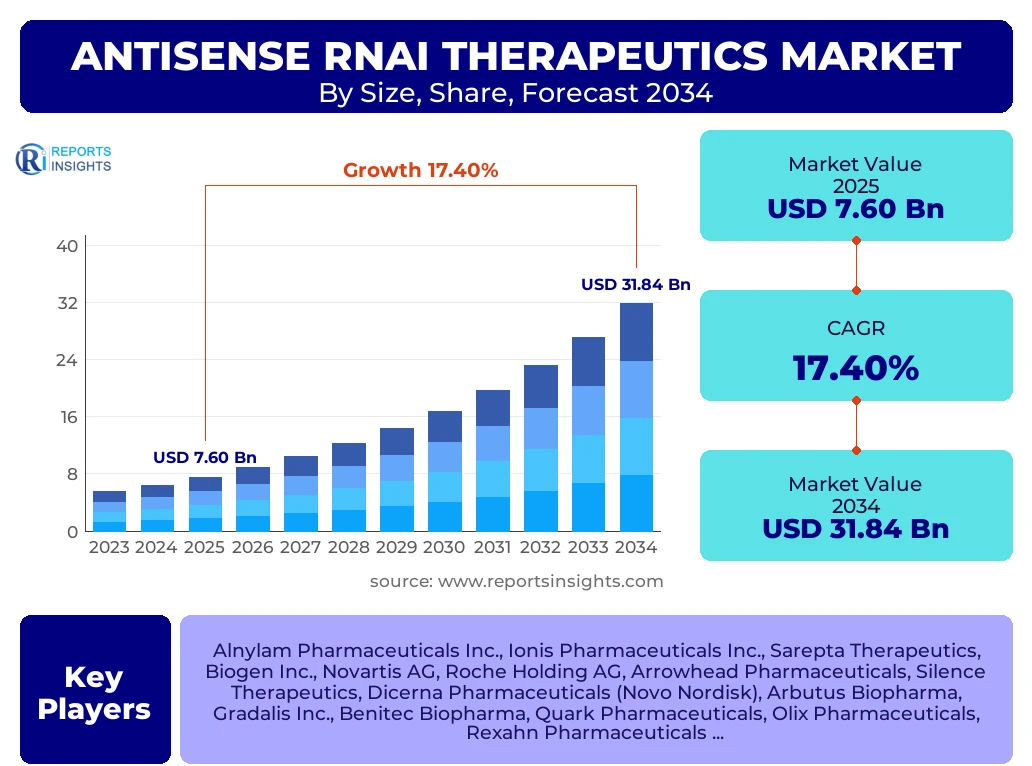
According to Reports Insights Consulting Pvt Ltd, The Antisense Rnai Therapeutics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 17.4% between 2026 and 2034. The market is estimated at USD 8.92 Billion in 2026 and is projected to reach USD 31.84 Billion by the end of the forecast period in 2034.
The market for antisense and RNA interference (RNAi) therapeutics is entering a phase of exponential expansion, driven by the successful commercialization of several high-profile oligonucleotide drugs and an increasingly robust clinical pipeline. Historically focused on rare and orphan diseases, the sector is now pivoting toward high-prevalence chronic conditions such as cardiovascular disease, hypertension, and metabolic disorders. This shift is significantly expanding the total addressable market, attracting substantial investment from both specialized biotechnology firms and diversified pharmaceutical conglomerates. The convergence of advanced genomic sequencing, sophisticated delivery platforms such as GalNAc conjugation and lipid nanoparticles (LNPs), and a maturing regulatory environment is fostering a fertile ground for market growth.
Furthermore, the long-term durability of these therapies—often requiring less frequent dosing compared to traditional small molecules or monoclonal antibodies—presents a compelling value proposition for healthcare payers and patients alike. As manufacturing processes become more standardized and cost-effective, the accessibility of these advanced therapies is expected to improve, further bolstering market valuation. The integration of artificial intelligence in sequence design is also shortening the drug discovery phase, allowing for more rapid entry of novel candidates into clinical trials.
Key Antisense Rnai Therapeutics Market Trends & Insights
The Antisense RNAi Therapeutics market is characterized by a rapid transition toward extra-hepatic targeting and the utilization of next-generation delivery technologies. Stakeholders are increasingly focused on overcoming the biological barriers of the blood-brain barrier (BBB) and the pulmonary system to treat neurological and respiratory diseases. Competitive benchmarking reveals that companies with proprietary chemical modification technologies, which enhance the stability and potency of oligonucleotides, are gaining a significant market advantage. Additionally, regional insights suggest that while North America remains the primary revenue hub, the Asia-Pacific region is witnessing the fastest growth due to rising healthcare expenditures and a burgeoning biotechnology infrastructure.
- Largest Region: North America, holding a dominant market share of approximately 42% due to concentrated R&D activities and high adoption of premium-priced orphan drugs.
- Fastest Growing Region: Asia-Pacific, projected to grow at the highest CAGR during the forecast period, driven by expanding clinical trial landscapes in China and India.
- Largest Technology Segment: Antisense Oligonucleotides (ASOs), currently leading in terms of approved products and revenue generation.
- Leading Application: Genetic Disorders, specifically those targeting Spinal Muscular Atrophy (SMA) and Duchenne Muscular Dystrophy (DMD).
- Emerging Trend: Increasing focus on GalNAc-conjugated siRNA for liver-targeted therapies, offering superior potency and safety profiles.
Key Takeaways Antisense Rnai Therapeutics Market Size & Forecast
The global market for Antisense and RNAi therapeutics is poised for transformative growth, with the forecast period of 2026–2034 reflecting a shift from niche applications to mainstream medical use. Key takeaways include the market's resilience despite high initial development costs and the significant role of strategic collaborations in de-risking the clinical pipeline. Investors and stakeholders are closely monitoring the transition of RNAi candidates from Phase II to Phase III, particularly those addressing cardiovascular health and non-alcoholic steatohepatitis (NASH), as these represent the next major revenue drivers.
- Strong Pipeline Momentum: Over 200 candidates are currently in various stages of clinical development, with a significant concentration in oncology and rare genetic conditions.
- Dominance of US Market: The United States remains the leading country in value, supported by favorable orphan drug designations and robust intellectual property protections.
- Strategic Alliances: Large-scale licensing deals between biotech innovators (e.g., Alnylam, Ionis) and Big Pharma (e.g., Roche, Novartis) are standardizing commercialization pathways.
- Technological Evolution: The shift from first-generation delivery systems to sophisticated ligand-conjugated delivery is reducing off-target effects and increasing patient compliance.
- Regulatory Support: Accelerated approval pathways by the FDA and EMA are shortening the time-to-market for therapies addressing unmet medical needs.
Antisense Rnai Therapeutics Market Drivers Analysis
The growth of the Antisense and RNAi therapeutics market is primarily fueled by the increasing prevalence of chronic diseases and the limitations of traditional therapeutic modalities in targeting "undruggable" proteins. By acting at the genetic level, these therapies offer precise intervention that was previously unattainable.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Targeted Delivery Systems (GalNAc/LNP) | +4.2% | Global | 2025–2034 |
| Rising Prevalence of Rare Genetic and Chronic Diseases | +3.8% | North America and Europe | 2025–2030 |
| Expansion into Common Diseases (Cardiovascular/NASH) | +5.1% | United States, China | 2028–2034 |
| Supportive Regulatory Frameworks and Orphan Drug Designations | +2.3% | European Union, Japan | 2025–2034 |
Antisense Rnai Therapeutics Market Restraints Analysis
Despite the high growth potential, the market faces significant hurdles related to the high cost of therapy and the biological challenges of systemic delivery. Achieving therapeutic concentrations in tissues like the brain or solid tumors remains a complex engineering task.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Prohibitive Cost of Specialized Manufacturing and Therapy | -2.8% | Emerging Markets | 2025–2034 |
| Rigid Biological Barriers to Non-Hepatic Delivery | -1.5% | Global | 2025–2029 |
| Stringent Regulatory Scrutiny for Off-target Effects | -0.9% | United States, EU | 2025–2034 |
Antisense Rnai Therapeutics Market Opportunities Analysis
The market is ripe with opportunities, particularly in the realm of personalized medicine and the treatment of neurodegenerative diseases. Developing platforms that can effectively cross the blood-brain barrier is considered the "holy grail" of the industry.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Neurodegenerative Disease Intervention (Alzheimer’s/Parkinson’s) | +6.5% | Global | 2029–2034 |
| Development of Oral RNAi Delivery Formulations | +3.4% | Developed Markets | 2030–2034 |
| Expansion into Oncology for Precision Gene Silencing | +4.1% | United States, Germany, Japan | 2026–2034 |
Antisense Rnai Therapeutics Market Challenges Impact Analysis
Market participants must navigate complex challenges ranging from intellectual property litigation to the logistical requirements of cold-chain distribution for certain RNA-based products.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intellectual Property Landscape and Patent Infringement Risks | -1.2% | Global | 2025–2034 |
| Competition from Gene Therapy and CRISPR Technologies | -2.1% | United States, Europe | 2027–2034 |
| Long-term Safety Data Requirements for Chronic Indications | -0.7% | Global | 2025–2034 |
Antisense Rnai Therapeutics Market - Updated Report Scope
This comprehensive report provides a detailed analysis of the global Antisense and RNAi therapeutics landscape, covering technological advancements, regulatory milestones, and competitive dynamics. It includes a deep dive into delivery platform innovation and the commercial performance of approved drugs, offering strategic insights for market entry and expansion.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 7.60 Billion |
| Market Forecast in 2034 | USD 31.84 Billion |
| Growth Rate | 17.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Alnylam Pharmaceuticals Inc., Ionis Pharmaceuticals Inc., Sarepta Therapeutics, Biogen Inc., Novartis AG, Roche Holding AG, Arrowhead Pharmaceuticals, Silence Therapeutics, Dicerna Pharmaceuticals (Novo Nordisk), Arbutus Biopharma, Gradalis Inc., Benitec Biopharma, Quark Pharmaceuticals, Olix Pharmaceuticals, Rexahn Pharmaceuticals, Regulus Therapeutics, WAVE Life Sciences, Santaris Pharma (Roche) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on technology, indication, and route of administration, each showing distinct growth trajectories. The technology segment is currently led by Antisense Oligonucleotides, while RNAi is witnessing rapid adoption for liver-associated diseases. Application-wise, genetic disorders hold the largest share, but cardiovascular indications are expected to witness the highest growth rate during the forecast period.
- By Technology:
- Antisense RNA Therapeutics (ASOs)
- RNA Interference (RNAi) Therapeutics
- Small Interfering RNA (siRNA)
- MicroRNA (miRNA)
- By Indication:
- Genetic Disorders (SMA, DMD, hATTR)
- Oncology
- Cardiovascular and Metabolic Diseases
- Neurological and CNS Disorders
- Ocular and Respiratory Diseases
- By Route of Administration:
- Intravenous
- Subcutaneous (Increasingly preferred for chronic care)
- Intrathecal (Crucial for CNS targeting)
- Others
Regional Highlights
- North America: The largest market, driven by high R&D investment, a favorable reimbursement landscape, and the presence of industry pioneers like Ionis and Alnylam. The US FDA’s proactive approach to oligonucleotide approvals is a key growth factor.
- Europe: A significant market characterized by strong public-private partnerships in biotechnology and high demand for orphan drug treatments in countries like Germany, France, and the UK.
- Asia-Pacific: The fastest-growing region, with China and Japan leading the way. Growing clinical trial density, rising investment in genomic medicine, and an aging population contribute to this growth.
- Latin America & MEA: Emerging markets with increasing healthcare infrastructure development, though currently limited by the high cost of oligonucleotide therapies.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Antisense Rnai Therapeutics Market.- Alnylam Pharmaceuticals Inc.
- Ionis Pharmaceuticals Inc.
- Sarepta Therapeutics
- Biogen Inc.
- Novartis AG
- Roche Holding AG
- Arrowhead Pharmaceuticals
- Silence Therapeutics
- Dicerna Pharmaceuticals (Novo Nordisk)
- Arbutus Biopharma
- Gradalis Inc.
- Benitec Biopharma
- Quark Pharmaceuticals
- Olix Pharmaceuticals
- WAVE Life Sciences
- Regulus Therapeutics
Frequently Asked Questions
What is the current market size of the Antisense RNAi Therapeutics sector?
The market is estimated at approximately USD 7.60 Billion in 2025 and is expected to reach over USD 31 Billion by 2034, growing at a CAGR of 17.4%.
What are the primary differences between Antisense and RNAi technologies?
Antisense technology uses single-stranded oligonucleotides to bind and inhibit target mRNA, while RNAi utilizes double-stranded RNA (siRNA) to trigger a natural cellular mechanism for gene silencing, generally offering higher potency.
Which indication is expected to drive future growth?
While rare genetic diseases currently lead the market, cardiovascular and metabolic diseases are expected to drive the next wave of growth due to the high volume of patients and recent approvals of therapies for cholesterol management.
What are the biggest challenges in the Antisense RNAi market?
The most significant challenges include the high cost of therapy, achieving effective delivery to tissues outside the liver (like the brain or lungs), and navigating complex intellectual property landscapes.
How is the competitive landscape changing?
The landscape is shifting from independent biotech innovation to large-scale partnerships where Big Pharma companies provide the commercial scale and distribution networks for biotech-developed oligonucleotide platforms.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted