Anesthesia Needles Syringes Market
Anesthesia Needles Syringes Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711001 | Published On : September 27, 2026 |
Format : 


 | Author : Erika Grotto
Anesthesia Needles Syringes Market Size
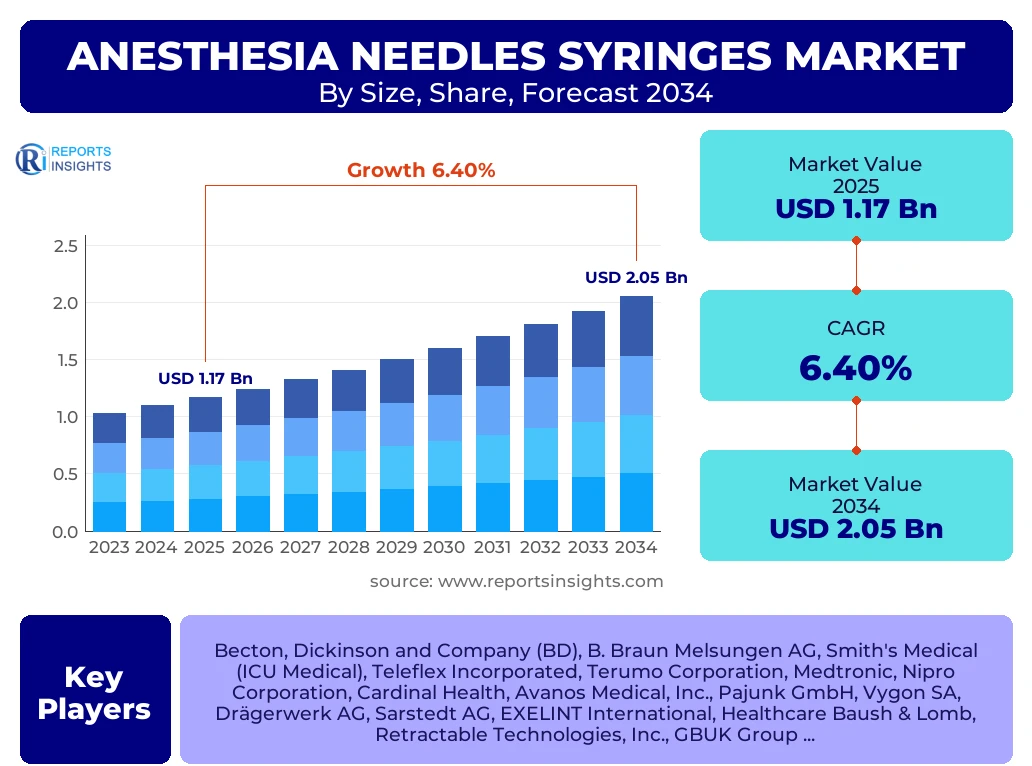
According to Reports Insights Consulting Pvt Ltd, The Anesthesia Needles Syringes Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2026 and 2034. The market is estimated at USD 1.25 Billion in 2026 and is projected to reach USD 2.05 Billion by the end of the forecast period in 2034.
The anesthesia needles and syringes market represents a critical segment of the global medical device industry, underpinned by the increasing volume of surgical procedures performed worldwide. As healthcare systems evolve, there is a distinct transition toward regional anesthesia techniques over general anesthesia for specific orthopedic, obstetric, and cardiovascular interventions. This shift is primarily attributed to the reduced recovery times, lower incidence of systemic complications, and enhanced post-operative pain management associated with localized anesthetic delivery. The market encompasses a diverse range of specialized instruments, including spinal needles, epidural needles, plexus needles, and various specialized syringes such as Loss of Resistance (LOR) syringes and standard luer-lock configurations.
The expansion of this market is further catalyzed by the rising geriatric population, which is more prone to chronic conditions requiring surgical intervention. Statistical data indicates that the global elderly demographic is expanding at an unprecedented rate, directly correlating with an increased demand for anesthesia delivery systems. Furthermore, the integration of safety-engineered devices designed to prevent needle-stick injuries and cross-contamination is reshaping the competitive landscape. Regulatory bodies are increasingly mandating the use of safety-oriented medical devices, forcing manufacturers to innovate in needle tip designs and syringe safety mechanisms, thereby driving both volume and value in the forecast period.
Key Anesthesia Needles Syringes Market Trends & Insights
The global anesthesia needles and syringes market is undergoing a period of rapid technological transformation, characterized by the adoption of ultrasound-guided needle placement and the development of non-coring needle geometries. Regional insights suggest that while developed economies are focusing on high-precision and safety-engineered products, emerging economies are experiencing a volume-driven surge due to expanding healthcare infrastructure and increased access to surgical care. Analytical benchmarking reveals that manufacturers are increasingly prioritizing ergonomic designs to improve clinician comfort and procedural accuracy, which is becoming a key differentiator in a crowded marketplace.
- North America remains the largest regional market, driven by high healthcare expenditure and early adoption of advanced needle technologies.
- The Asia-Pacific region is identified as the fastest-growing market, with China and India leading the demand due to massive hospital expansions and medical tourism.
- Spinal needles represent the largest product segment in terms of revenue share, primarily due to their essential role in common lower-body surgeries.
- The trend toward disposable, single-use anesthesia kits is accelerating to minimize infection risks and streamline hospital inventory management.
- Advancements in material science, such as the use of high-grade surgical steel and advanced polymer coatings, are improving needle penetration and patient comfort.
Key Takeaways Anesthesia Needles Syringes Market Size & Forecast
The long-term outlook for the anesthesia needles and syringes market is highly positive, with consistent growth trajectories observed across both established and emerging surgical categories. Key takeaways highlight the critical role of innovation in sustaining market share, particularly as healthcare providers demand more cost-effective yet high-performing medical consumables. The forecast period 2025-2034 is expected to see a significant consolidation of players who can provide integrated anesthesia kits that combine needles, syringes, and catheters into a single, sterile procedural unit.
- The United States is the leading country globally, accounting for a significant portion of market value due to its sophisticated anesthesiology infrastructure.
- Increased prevalence of orthopedic surgeries, particularly knee and hip replacements, is a major volume driver for spinal and epidural needles.
- Technological integration, such as echo-reflective needle tips for better ultrasound visibility, is becoming a standard requirement in high-end medical facilities.
- Sustainability is emerging as a critical factor, with hospitals seeking medical device partners that offer recyclable packaging and eco-friendly manufacturing processes.
- The transition from glass to high-performance plastic syringes for anesthesia delivery is nearly complete, driven by cost-efficiency and break-resistance.
Anesthesia Needles Syringes Market Drivers Analysis
The primary drivers of the anesthesia needles and syringes market include the escalating global surgical volume and the strategic shift toward ambulatory surgical centers (ASCs). These factors are compounded by an increasing focus on patient safety and the clinical advantages of regional anesthesia in reducing the hospital stay duration.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Volume of Geriatric Orthopedic Surgeries | +1.8% | Global (High in Europe & Japan) | 2025-2034 |
| Shift Toward Ultrasound-Guided Nerve Blocks | +1.5% | North America and Western Europe | 2026-2030 |
| Expansion of Healthcare Access in Emerging Markets | +1.2% | India, China, Southeast Asia | 2025-2034 |
| Mandatory Safety-Engineered Device Regulations | +0.9% | USA and European Union | 2025-2028 |
Anesthesia Needles Syringes Market Restraints Analysis
The market faces significant restraints, including the high cost associated with advanced safety-engineered needles and the stringent regulatory hurdles for new product approvals. Additionally, complications such as post-dural puncture headaches (PDPH) remain a clinical concern that can limit the adoption of certain needle types.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complications Related to Regional Anesthesia (e.g., PDPH) | -0.7% | Global | 2025-2034 |
| Pricing Pressures and Competitive Tendering | -0.5% | Developing Economies (LATAM, APAC) | 2025-2030 |
| Strict Regulatory Compliance and Documentation Requirements | -0.4% | USA (FDA) and Europe (MDR) | Ongoing |
Anesthesia Needles Syringes Market Opportunities Analysis
Significant opportunities reside in the development of "smart" needles that provide real-time feedback during insertion and the untapped potential of rural healthcare markets in developing nations. Furthermore, the customized procedure tray market offers a pathway for manufacturers to bundle syringes and needles for specific surgical types.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Echogenic Needle Tips for Visibility | +1.4% | Global (High-End Hospitals) | 2026-2034 |
| Growth in Outpatient Surgery and ASCs | +1.1% | United States | 2025-2032 |
| Integration of Bio-compatible Materials | +0.6% | Europe and Japan | 2027-2034 |
Anesthesia Needles Syringes Market Challenges Impact Analysis
The market must navigate challenges such as the volatility of raw material prices (medical-grade steel and plastics) and the increasing threat of low-cost generic competitors. Managing supply chain resilience in the wake of global geopolitical tensions also remains a priority for enterprise-level stakeholders.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Medical Grade Stainless Steel Pricing | -0.4% | Global Manufacturers | Short to Medium Term |
| Counterfeit and Low-Quality Medical Supplies | -0.3% | Southeast Asia and Africa | Ongoing |
| Shift Toward Needle-Free Injection Technologies | -0.2% | Niche Applications (Global) | Long Term |
Anesthesia Needles Syringes Market - Updated Report Scope
This comprehensive market report provides a deep-dive analysis of the anesthesia delivery landscape, covering the complete spectrum of needles and syringes used in perioperative care. The scope includes technological evaluation, regulatory assessments, and a granular competitive analysis of the major entities shaping the industry's future.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.17 Billion |
| Market Forecast in 2034 | USD 2.05 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Becton, Dickinson and Company (BD), B. Braun Melsungen AG, Smith's Medical (ICU Medical), Teleflex Incorporated, Terumo Corporation, Medtronic, Nipro Corporation, Cardinal Health, Avanos Medical, Inc., Pajunk GmbH, Vygon SA, Drägerwerk AG, Sarstedt AG, EXELINT International, Healthcare Baush & Lomb, Retractable Technologies, Inc., GBUK Group, Epimed International, Romsons, HMD (Hindustan Syringes & Medical Devices) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The anesthesia needles and syringes market is segmented primarily by product type, focusing on the specific clinical application of the device. This segmentation reflects the nuanced requirements of different anesthetic techniques, such as the high precision needed for subarachnoid blocks versus the tactile feedback required for epidural space identification.
- By Product Type: This includes Spinal Needles (Quincke, Pencil Point), Epidural Needles (Tuohy, Hustead), Nerve Block Needles, and Plexus Needles. Syringe categories include Loss of Resistance (LOR) Syringes specifically for epidurals and standard anesthesia syringes.
- By Material: While stainless steel is the standard for needles, syringes are categorized into plastic (polypropylene) and glass, with plastic holding the majority share due to safety and disposal advantages.
- By End-User: Hospitals remain the dominant end-user, but the Ambulatory Surgical Center (ASC) segment is witnessing the highest growth rate due to the global trend of decentralizing surgical care.
- By Technology: Segments include Conventional Needles and Safety-Engineered/Echogenic Needles, with the latter capturing market share in premium healthcare segments.
Regional Highlights
- North America: Holds the largest revenue share, supported by a highly developed healthcare system, a large volume of surgical procedures, and strict OSHA regulations regarding needle-stick safety.
- Europe: A mature market characterized by high adoption of regional anesthesia and a strong presence of major manufacturers like B. Braun and Pajunk. The implementation of the EU Medical Device Regulation (MDR) is a key factor influencing product availability.
- Asia-Pacific: The fastest-growing region, driven by massive investments in healthcare infrastructure in China and India, alongside an increasing awareness of advanced anesthetic techniques among clinicians.
- Latin America: Showing steady growth due to the modernization of hospital facilities in Brazil and Mexico, though economic volatility remains a factor.
- Middle East & Africa: An emerging market focusing on basic surgical infrastructure expansion and public health initiatives to reduce maternal mortality through safe anesthesia practices.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Anesthesia Needles Syringes Market.
- Becton, Dickinson and Company (BD)
- B. Braun Melsungen AG
- Smith's Medical (ICU Medical)
- Teleflex Incorporated
- Terumo Corporation
- Medtronic
- Nipro Corporation
- Cardinal Health
- Avanos Medical, Inc.
- Pajunk GmbH
- Vygon SA
- Drägerwerk AG
- Sarstedt AG
- EXELINT International
- Retractable Technologies, Inc.
- GBUK Group
- Epimed International
- Romsons
- Hindustan Syringes & Medical Devices (HMD)
- Bostan Scientific
Frequently Asked Questions
What is the current global market size of anesthesia needles and syringes?
The market is estimated at approximately USD 1.17 Billion in 2025 and is projected to exceed USD 2.05 Billion by 2034, growing at a steady CAGR of 6.4%.
Which product segment dominates the anesthesia needle market?
Spinal needles currently dominate the market share due to the high frequency of spinal anesthesia in orthopedic and obstetric surgeries worldwide.
What are the primary drivers for the Asia-Pacific market growth?
The primary drivers include the expansion of private hospital chains, increasing government healthcare spending, and a rising volume of elective surgeries in China and India.
How is ultrasound technology affecting the needle market?
Ultrasound technology has led to the development of echogenic needles with specialized tips that are more visible under imaging, improving success rates for nerve blocks and reducing complications.
What role do safety-engineered syringes play in the market?
Safety-engineered syringes are becoming the industry standard to protect healthcare workers from needle-stick injuries and blood-borne pathogens, often mandated by regional health regulations.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted