Aluminum Flat Products Market
Aluminum Flat Products Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711945 | Published On : November 22, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Aluminum Flat Products Market Size
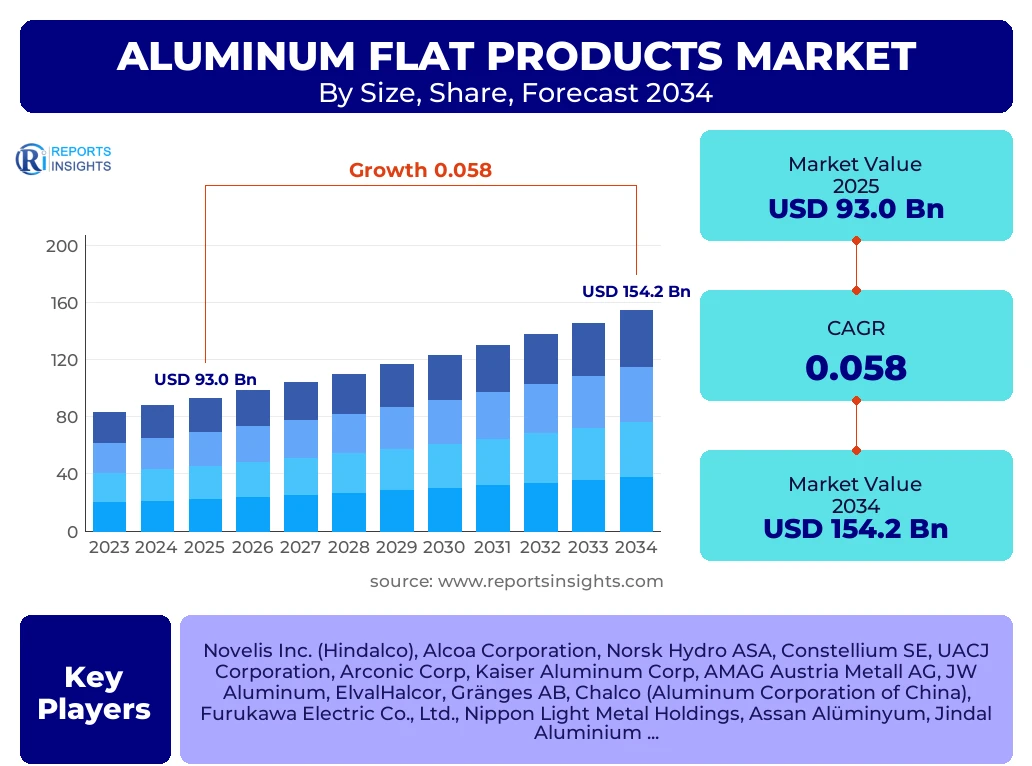
According to Reports Insights Consulting Pvt Ltd, The Aluminum Flat Products Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 98.4 Billion in 2026 and is projected to reach USD 154.2 Billion by the end of the forecast period in 2034.
Key Aluminum Flat Products Market Trends & Insights
The global aluminum flat products landscape is currently undergoing a transformative phase driven by the dual imperatives of decarbonization and industrial light-weighting. Advanced manufacturing techniques, such as continuous casting and sophisticated cold-rolling processes, are enabling the production of thinner, higher-strength sheets that meet the rigorous standards of the aerospace and automotive sectors. Furthermore, the integration of circular economy principles is significantly influencing procurement strategies, with secondary aluminum (recycled) increasingly favored over primary aluminum due to its 95% lower energy consumption during production. Market intelligence indicates a sharp rise in demand for 5xxx and 6xxx series alloys specifically tailored for electric vehicle (EV) battery enclosures and structural components, as manufacturers seek to offset the weight of heavy battery packs.
- Asia-Pacific is the largest and fastest-growing regional market, accounting for over 45% of global volume due to rapid industrialization in China and India.
- The Transportation segment is the fastest-growing end-use category, primarily fueled by the transition to electric mobility.
- The Packaging segment remains the largest in terms of volume share, driven by the shift away from single-use plastics toward infinitely recyclable aluminum cans and foils.
- Increasing adoption of the 7xxx series high-strength alloys in aerospace is driving significant value-based growth in developed economies.
Key Takeaways Aluminum Flat Products Market Size & Forecast
The long-term trajectory of the Aluminum Flat Products Market is fundamentally linked to global sustainability goals and the modernization of infrastructure. As governments implement stricter emissions regulations, the demand for aluminum sheets and plates in the automotive sector is expected to witness a sustained upward trend. Moreover, the packaging industry's pivot toward circularity provides a resilient baseline for market growth. Technological advancements in surface treatment and coating are further expanding the application scope in the building and construction sector, particularly for high-end architectural facades and roofing solutions that offer both aesthetic appeal and thermal efficiency.
- China remains the dominant producer and consumer, though Southeast Asian nations like Vietnam and Indonesia are emerging as significant secondary hubs.
- The market for aluminum foil is seeing a resurgence in the pharmaceutical sector due to its superior barrier properties against moisture and light.
- Sustainable manufacturing certifications, such as the Aluminum Stewardship Initiative (ASI), are becoming a prerequisite for suppliers catering to premium global brands.
- Supply chain diversification is a critical priority for Western manufacturers seeking to mitigate risks associated with trade tensions and logistical disruptions.
Aluminum Flat Products Market Drivers Analysis
The primary catalysts for growth in the aluminum flat products market are centered on the industrial shift toward energy efficiency and material circularity. These drivers are not merely cyclical but represent a structural change in how materials are selected for large-scale engineering and consumer applications.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lightweighting in Electric Vehicle (EV) Production | +1.5% | Germany, USA, China | 2025 - 2034 |
| Plastic Substitution in Packaging Industry | +1.1% | European Union, North America | 2025 - 2030 |
| Expansion of Renewable Energy Infrastructure (Solar Frames) | +0.8% | India, Australia, Brazil | 2026 - 2034 |
| Recovery and Growth of the Global Aerospace Sector | +0.7% | France, USA, Canada | 2025 - 2032 |
Aluminum Flat Products Market Restraints Analysis
Despite robust demand, the market faces headwinds from volatile raw material costs and high energy intensity in the smelting process. Regulatory pressures regarding carbon emissions also impose significant compliance costs on older production facilities.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in LME Aluminum Prices | -0.6% | Global | Continuous |
| High Energy Costs and Carbon Taxes (CBAM) | -0.5% | European Union, UK | 2026 - 2034 |
| Competition from Advanced Composites in Aerospace | -0.3% | North America, Europe | 2025 - 2030 |
Aluminum Flat Products Market Opportunities Analysis
The transition to a low-carbon economy presents significant white-space opportunities, particularly in the development of "Green Aluminum" products and specialized alloys for high-tech applications like 5G infrastructure and hydrogen storage.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Low-Carbon/Green Aluminum Sheets | +1.2% | Nordic Countries, Canada | 2025 - 2034 |
| Modernization of Urban Infrastructure in Emerging Markets | +0.9% | India, Indonesia, Nigeria | 2027 - 2034 |
| Growth in 5G Telecommunication Hardware Enclosures | +0.5% | South Korea, Japan, USA | 2025 - 2029 |
Aluminum Flat Products Market Challenges Impact Analysis
Operational challenges include the necessity for massive capital investment in modernization and the geopolitical complexities of bauxite and alumina supply chains, which can lead to localized shortages.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Trade Barriers and Tariffs | -0.4% | USA, China, Russia | 2025 - 2030 |
| Logistical Bottlenecks in International Shipping | -0.3% | Global Trade Routes | 2025 - 2027 |
Aluminum Flat Products Market - Updated Report Scope
This report provides a granular analysis of the global aluminum flat products market, encompassing production volumes, value forecasts, and technological shifts across various alloy series and end-use sectors. The scope covers the entire value chain from rolling ingot to finished sheet, plate, and foil products, offering insights into competitive positioning and regional growth dynamics.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 93.0 Billion |
| Market Forecast in 2034 | USD 154.2 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Novelis Inc. (Hindalco), Alcoa Corporation, Norsk Hydro ASA, Constellium SE, UACJ Corporation, Arconic Corp, Kaiser Aluminum Corp, AMAG Austria Metall AG, JW Aluminum, ElvalHalcor, Gränges AB, Chalco (Aluminum Corporation of China), Furukawa Electric Co., Ltd., Nippon Light Metal Holdings, Assan Alüminyum, Jindal Aluminium, Gulf Aluminium Rolling Mill (GARMCO), Impol Aluminum Corp, Hindalco Industries Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on product configuration, metallurgical composition, and specific industrial applications. Sheets and foils represent the highest volume segments due to their ubiquity in consumer packaging and automotive body panels. Plates, characterized by greater thickness, are critical for structural integrity in the aerospace and marine sectors. The alloy-based segmentation highlights a transition toward the 5xxx and 6xxx series, which offer the optimal balance of formability and strength required for modern engineering solutions.
- By Product Type:
- Aluminum Sheets: Predominantly used in automotive outer panels and beverage cans.
- Aluminum Plates: Essential for heavy-duty structural applications in aerospace and defense.
- Aluminum Foils: Widely utilized in flexible packaging and heat exchangers.
- Fin Stock: Specialized products for HVAC and refrigeration systems.
- By Alloy Type:
- 1xxx Series (Pure Aluminum): High corrosion resistance, used in chemical and electrical sectors.
- 3xxx Series (Manganese-based): Work-horse alloy for beverage cans and general-purpose sheets.
- 5xxx Series (Magnesium-based): High-strength and weldable, favored for marine and automotive applications.
- 6xxx Series (Silicon/Magnesium): Versatile alloy used in structural automotive parts and building facades.
- 7xxx Series (Zinc-based): Ultra-high strength, primary choice for aerospace structures.
- By End-Use Industry:
- Transportation: Includes Automotive (Auto Body Sheet), Aerospace, and Rail.
- Packaging: Covers Beverage Cans, Food Containers, and Pharmaceutical Foil.
- Building and Construction: Roofing, Siding, and Curtain Walls.
- Electrical and Electronics: Heat sinks, busbars, and electronic enclosures.
Regional Highlights
- Asia-Pacific: The dominant region by both volume and value. China is the global hub for aluminum rolling, while India is witnessing the fastest growth due to government initiatives like "Make in India" and massive investments in railway and infrastructure modernization.
- North America: A high-value market characterized by a focus on aerospace-grade plates and specialized automotive sheets. The presence of major aerospace OEMs drives the demand for advanced 7xxx series alloys.
- Europe: The leader in sustainability and circular economy initiatives. The European market is seeing a rapid shift toward low-carbon aluminum, supported by stringent environmental regulations and a robust recycling infrastructure.
- Middle East and Africa: Growth is primarily driven by the construction sector and the presence of major primary aluminum smelters in the GCC region, which are increasingly diversifying into downstream flat products.
- Latin America: Brazil is the key contributor, with a well-established beverage can market and growing industrial applications in the automotive sector.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Aluminum Flat Products Market.- Novelis Inc. (A subsidiary of Hindalco Industries)
- Alcoa Corporation
- Norsk Hydro ASA
- Constellium SE
- UACJ Corporation
- Arconic Corp
- Kaiser Aluminum Corp
- AMAG Austria Metall AG
- JW Aluminum
- ElvalHalcor
- Gränges AB
- Chalco (Aluminum Corporation of China)
- Furukawa Electric Co., Ltd.
- Nippon Light Metal Holdings
- Assan Alüminyum
- Jindal Aluminium
- Gulf Aluminium Rolling Mill (GARMCO)
- Impol Aluminum Corp
- Alnan Aluminium Co., Ltd.
- Wispeco Aluminium
Frequently Asked Questions
What is driving the growth of the Aluminum Flat Products Market in the automotive sector?
The primary driver is the global shift toward electric vehicles (EVs). Aluminum flat products are essential for lightweighting, which extends battery range. Specifically, aluminum sheets are used for battery enclosures, body panels, and structural components to reduce overall vehicle weight without compromising safety.
How does the recycling of aluminum affect the market dynamics?
Recycling is a major trend as secondary aluminum production requires only 5% of the energy needed for primary aluminum. This significantly lowers the carbon footprint of flat products, making them highly attractive to industries under strict environmental regulations, such as packaging and automotive.
Which alloy series is most commonly used for aerospace applications?
The 7xxx series (Zinc-based) and 2xxx series (Copper-based) are the most common in aerospace. The 7xxx series is favored for its ultra-high strength and fatigue resistance, making it ideal for wing structures and fuselage components in commercial and military aircraft.
What are the main challenges facing aluminum flat product manufacturers today?
Key challenges include the volatility of raw material prices on the London Metal Exchange (LME), high energy costs associated with production, and the impact of geopolitical trade tariffs. Additionally, manufacturers must invest heavily in decarbonization technologies to remain competitive.
Why is the Asia-Pacific region the largest market for these products?
Asia-Pacific leads due to its massive manufacturing base, particularly in China. High demand from the construction, packaging, and electronics sectors, combined with rapid urbanization and the expansion of the automotive industry in China and India, makes it the global engine for market growth.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
