Aluminum Extrusion Market
Aluminum Extrusion Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710905 | Published On : September 16, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Aluminum Extrusion Market Size
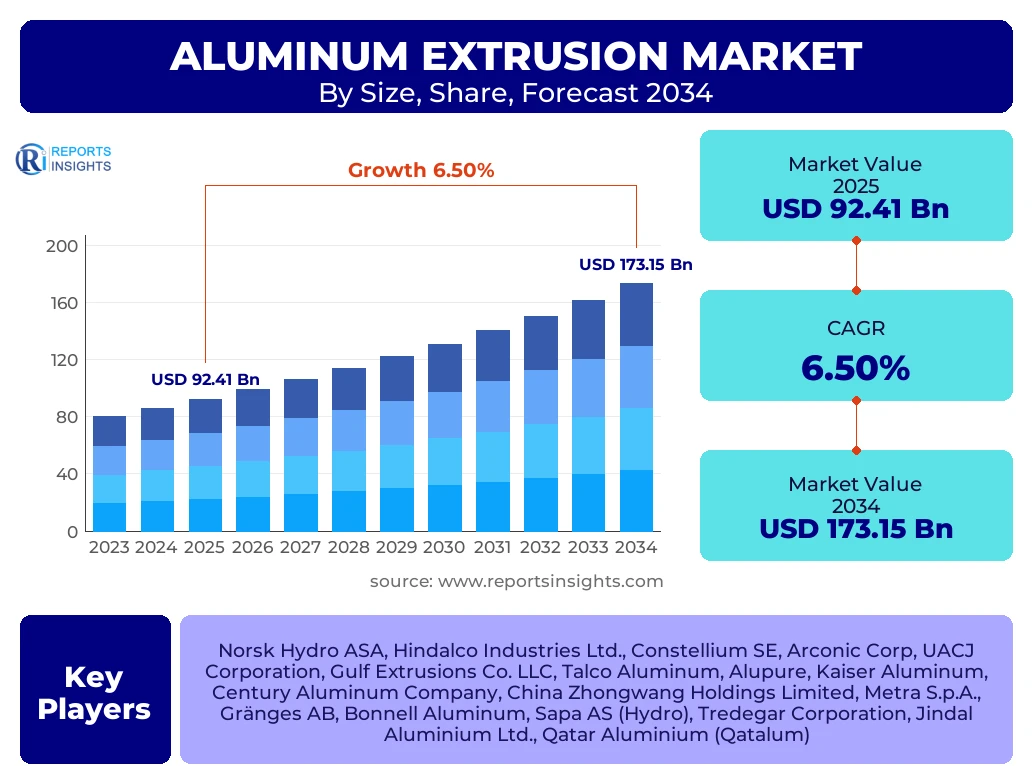
According to Reports Insights Consulting Pvt Ltd, The Aluminum Extrusion Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.5% between 2026 and 2034. The market is estimated at USD 98.42 Billion in 2026 and is projected to reach USD 173.15 Billion by the end of the forecast period in 2034.
Key Aluminum Extrusion Market Trends & Insights
The global aluminum extrusion industry is undergoing a transformative phase driven by the dual imperatives of decarbonization and industrial modernization. Users and stakeholders are increasingly inquiring about the role of secondary (recycled) aluminum in reducing the carbon footprint of extrusions, particularly in the European and North American markets. Trends indicate a significant shift toward 6000-series alloys due to their superior strength-to-weight ratios and versatility in structural applications. Competitive benchmarking reveals that leading players are investing heavily in automated press lines and high-speed extrusion technologies to meet the surging demand from the Electric Vehicle (EV) and renewable energy sectors. Furthermore, the integration of Industry 4.0 practices is enabling real-time monitoring of die performance and metal flow, leading to enhanced precision and reduced scrap rates.
- Largest Region: Asia Pacific remains the dominant regional market, accounting for over 50% of global volume, fueled by massive infrastructure projects in China and India.
- Fastest Growing Region: North America is poised for rapid growth due to the aggressive expansion of domestic EV manufacturing and federal incentives for green energy infrastructure.
- Leading End-User Segment: The Building and Construction segment holds the largest market share, driven by the demand for energy-efficient window frames, curtain walls, and roofing systems.
- Emerging High-Growth Segment: The Automotive and Transportation sector is the fastest-growing end-user segment, catalyzed by the transition to electric mobility and the need for lightweight battery enclosures.
Key Takeaways Aluminum Extrusion Market Size & Forecast
Analysis of market inquiries suggests a high level of interest in the long-term viability of aluminum as a replacement for steel in heavy-duty applications. The forecast indicates a steady upward trajectory as global net-zero targets necessitate the use of recyclable materials. Stakeholders are particularly focused on supply chain resilience and the impact of fluctuating energy prices on primary smelting versus extrusion costs. The transition toward circular economy models is expected to redefine market dynamics, where the availability of high-quality aluminum scrap becomes a strategic competitive advantage for extruders globally.
- Market Valuation: The industry is set to surpass the USD 150 billion mark by the early 2030s, reflecting a robust industrial appetite for non-corrosive, lightweight materials.
- Sustainability Focus: Low-carbon aluminum extrusions, produced using renewable energy sources like hydropower, are commanding a premium price in the European market.
- Regional Dominance: China continues to be the primary hub for both production and consumption, though Southeast Asian nations are emerging as significant secondary manufacturing nodes.
- Innovation in Alloys: Development of high-strength 7000-series alloys for aerospace and high-end automotive applications is expanding the addressable market for extrusion technology.
Aluminum Extrusion Market Drivers Analysis
The growth of the aluminum extrusion market is primarily propelled by the global shift toward sustainable transportation and energy-efficient building solutions. As governments implement stricter emission standards, the automotive industry is forced to adopt lightweighting strategies, where aluminum extrusions play a critical role in chassis and body-in-white components. Additionally, the rapid expansion of solar photovoltaic installations globally requires vast quantities of extruded aluminum for racking and mounting systems, providing a steady demand floor for the industry.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|
Aluminum Extrusion Market Restraints Analysis
Despite strong growth drivers, the market faces significant hurdles related to the volatility of London Metal Exchange (LME) aluminum prices and the high energy intensity of the primary production process. These factors can lead to unpredictable margin compression for extruders who lack robust hedging strategies. Furthermore, geopolitical tensions and the imposition of anti-dumping duties on aluminum products from certain regions create trade barriers that complicate global supply chain logistics and increase costs for end-users.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|
Aluminum Extrusion Market Opportunities Analysis
The emergence of the "Green Aluminum" segment represents the most significant opportunity for market participants to differentiate their offerings. Utilizing renewable energy for smelting and increasing the recycled content in extrusion billets allows companies to cater to the ESG-conscious automotive and electronics sectors. Furthermore, the 5G rollout requires specialized heat sinks and enclosures that can be efficiently produced through extrusion, opening a niche but high-value revenue stream in the telecommunications sector.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|
Aluminum Extrusion Market Challenges Impact Analysis
Technical challenges involve the difficulty of extruding complex geometries with high-strength alloys while maintaining strict dimensional tolerances. As end-users demand thinner walls and more intricate designs to save weight, extruders must innovate in die design and cooling technologies. Additionally, the industry must navigate the challenge of decarbonizing the thermal energy used in extrusion aging ovens and billet heaters, which currently relies heavily on natural gas in many regions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|
Aluminum Extrusion Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global aluminum extrusion landscape, covering market dynamics, competitive positioning, and technological advancements. The scope includes a granular breakdown of product types, surface treatments, and end-user industries across six major geographic regions. Special emphasis is placed on the impact of environmental regulations and the shifting trade dynamics that influence regional production capacities and pricing structures.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 92.41 Billion |
| Market Forecast in 2034 | USD 173.15 Billion |
| Growth Rate | 6.5% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Norsk Hydro ASA, Hindalco Industries Ltd., Constellium SE, Arconic Corp, UACJ Corporation, Gulf Extrusions Co. LLC, Talco Aluminum, Alupure, Kaiser Aluminum, Century Aluminum Company, China Zhongwang Holdings Limited, Metra S.p.A., Gränges AB, Bonnell Aluminum, Sapa AS (Hydro), Tredegar Corporation, Jindal Aluminium Ltd., Qatar Aluminium (Qatalum) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to reflect the diverse applications and technical requirements of different industrial sectors. The 6000-series alloy segment remains the largest due to its optimal balance of extrudability, strength, and corrosion resistance, making it the standard for architectural and structural applications. From a surface treatment perspective, the powder-coated segment is experiencing significant growth in the architectural sector due to the demand for diverse aesthetic finishes and superior weather resistance compared to mill-finished products.
- By Product Type:
- Mill Finished: The most cost-effective option, widely used in internal structural components where aesthetics are secondary.
- Anodized: Preferred for high-end architectural applications and marine environments due to its enhanced protective oxide layer.
- Powder Coated: Gaining share in residential and commercial construction for its durability and color variety.
- By Alloy Series:
- 1000 & 3000 Series: Used primarily for heat exchangers and chemical equipment.
- 6000 Series: The dominant alloy for windows, doors, and automotive structural components.
- 7000 Series: High-strength alloys used in aerospace and performance automotive parts.
- By End-User:
- Building & Construction: Frames, curtain walls, and roofing.
- Automotive: Crash management systems, battery boxes, and structural beams.
- Renewable Energy: Solar panel frames and mounting structures.
- Consumer Durables: Furniture, electronics housings, and sporting goods.
Regional Highlights
The regional analysis reveals a bifurcated market where growth in developed economies is driven by technological sophistication, while growth in developing economies is driven by volume. Asia Pacific continues to lead the global market in terms of production capacity, with China alone producing more than half of the world's aluminum extrusions. The Indian market is identified as a high-growth pocket, particularly in the infrastructure and rail sectors, where aluminum is replacing steel for modernized train coaches.
- Asia Pacific: The largest market, driven by industrialization in China, India, and Vietnam. It serves as the primary global manufacturing hub for electronic and consumer goods extrusions.
- North America: The region is seeing a resurgence in domestic manufacturing, specifically focusing on high-value extrusions for the burgeoning EV market and aerospace defense.
- Europe: The leader in "Green Aluminum" adoption. Stringent environmental regulations and carbon border adjustment mechanisms (CBAM) are forcing a shift toward low-carbon extrusion processes.
- Middle East: Leveraging abundant energy resources to produce primary aluminum, this region is increasingly moving downstream into extrusion to diversify its economic base.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Aluminum Extrusion Market.- Norsk Hydro ASA
- Hindalco Industries Ltd.
- Constellium SE
- Arconic Corporation
- UACJ Corporation
- Gulf Extrusions Co. LLC
- Kaiser Aluminum
- China Zhongwang Holdings Limited
- Century Aluminum Company
- Metra S.p.A.
- Bonnell Aluminum
- Jindal Aluminium Ltd.
- Alupure
- Qatar Aluminium (Qatalum)
- Gränges AB
- Tredegar Corporation
- Talco Aluminum
- Profile Precision Extrusions
Frequently Asked Questions
What is driving the growth of the Aluminum Extrusion Market?
The growth is primarily driven by the increasing demand for lightweight materials in the automotive industry (particularly EVs), the expansion of the solar energy sector, and the rise in green building construction globally.
Which alloy series is most commonly used in extrusion?
The 6000-series alloy is the most common due to its excellent extrudability, strength, and corrosion resistance, making it suitable for both architectural and automotive applications.
How is "Green Aluminum" impacting the market?
Green aluminum, produced using renewable energy, is becoming a key differentiator for extruders. It allows manufacturers to meet strict ESG targets and reduce the Scope 3 emissions for their end-users in sectors like electronics and automotive.
Which region holds the largest market share?
Asia Pacific holds the largest market share, accounting for over 50% of the global market, driven by heavy industrial demand and infrastructure growth in China and India.
What are the main challenges for aluminum extruders?
Key challenges include the volatility of raw material prices (LME aluminum), high energy costs for production, and the technical difficulty of extruding complex, high-strength alloys for precision industries.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted