Airbag Market
Airbag Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711947 | Published On : November 22, 2026 |
Format : 


 | Author : Ashraf Shehata
Airbag Market Size
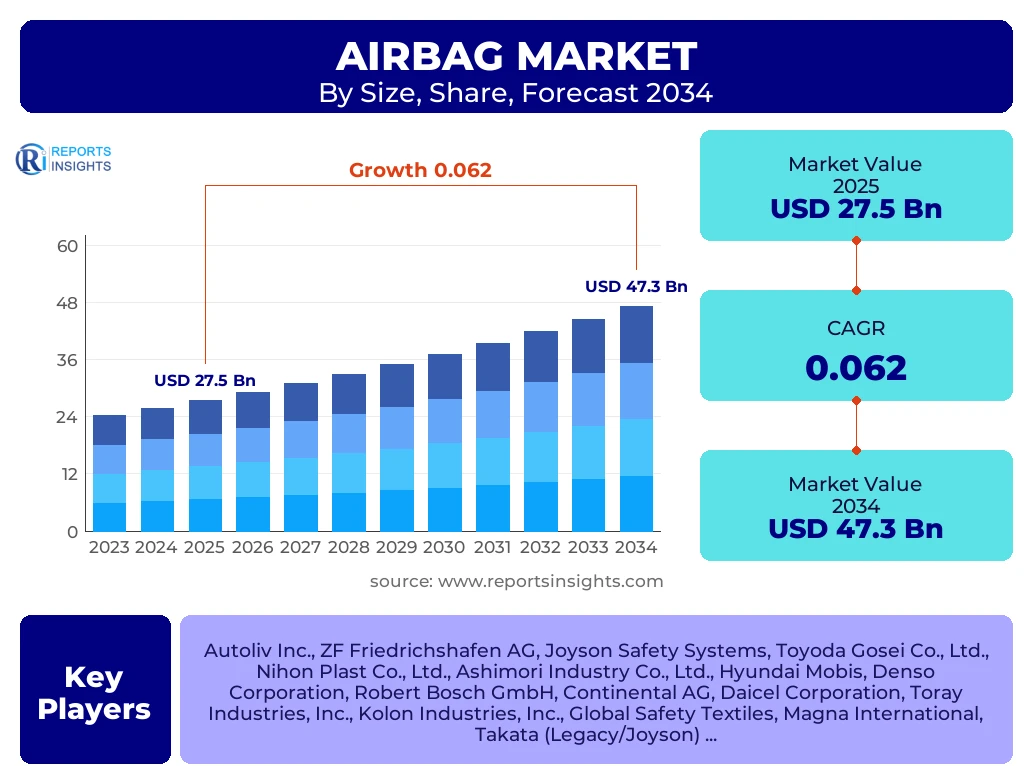
According to Reports Insights Consulting Pvt Ltd, The Airbag Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 29.2 Billion in 2026 and is projected to reach USD 47.3 Billion by the end of the forecast period in 2034.
Key Airbag Market Trends & Insights
The global automotive landscape is undergoing a radical transformation, driven by the convergence of electric mobility, autonomous driving technologies, and increasingly stringent safety mandates. In the current market environment, the airbag sector is no longer viewed as a static hardware industry but rather a dynamic component of the integrated vehicle safety ecosystem. Modern airbag systems are increasingly incorporating advanced sensor arrays and machine learning algorithms to facilitate "smart" deployment, which adjusts the force and timing of inflation based on occupant weight, position, and the specific dynamics of a collision. This shift is particularly evident in the rise of side-impact and curtain airbags, which are seeing higher adoption rates in emerging economies as global safety standards like the New Car Assessment Program (NCAP) become more harmonized across borders.
Furthermore, the evolution of vehicle interiors in the era of autonomous driving is necessitating a complete redesign of airbag placement. With the potential for rotating seats and unconventional cabin layouts, manufacturers are prototyping "cocoon" style airbags and seat-mounted restraint systems that offer protection regardless of the passenger’s orientation. This trend is accompanied by a material science revolution, where developers are seeking lightweight, sustainable fabrics that do not compromise on the rapid deployment requirements or thermal stability of the inflator units. These innovations are positioning the airbag market as a cornerstone of the broader "Vision Zero" initiatives led by governments worldwide to eliminate road fatalities.
- Largest Region: Asia-Pacific currently holds the largest market share, driven by massive vehicle production volumes in China and India.
- Fastest Growing Region: Asia-Pacific is also expected to be the fastest-growing region due to rising middle-class disposable income and evolving safety regulations.
- Largest Segment by Type: Frontal airbags remain the largest segment in terms of market share, though side and curtain airbags are gaining rapid ground.
- Leading Vehicle Type: Passenger cars continue to dominate the airbag market, accounting for over 70 percent of the total revenue.
Key Takeaways Airbag Market Size & Forecast
The trajectory of the airbag market reflects a robust growth pattern rooted in the essential nature of occupant safety. As automotive manufacturers integrate more sophisticated electronics, the cost-per-vehicle for safety systems is increasing, contributing to higher overall market value. The transition from basic mechanical triggers to complex electronic control units (ECUs) that manage multiple airbag modules simultaneously has created a significant barrier to entry, favoring established tier-1 suppliers with deep R&D capabilities. Analysts anticipate that the forecast period will see a stabilization in raw material costs, though the complexity of the deployment software will become the primary value driver for the industry.
- The global market value is set to nearly double over the next decade, fueled by the universal adoption of six-airbag configurations in budget-friendly vehicle models.
- China remains the single largest consumer and producer of airbag modules, with domestic manufacturers rapidly closing the technology gap with Western competitors.
- Increasing consumer awareness regarding vehicle safety ratings is forcing OEMs to include premium airbag features, such as knee and pedestrian airbags, as standard equipment.
- The aftermarket for airbags is witnessing moderate growth, primarily driven by the replacement of modules in aging vehicle fleets and the servicing of systems after deployment.
- Sustainability is becoming a key differentiator, with companies investing in recyclable nylon fabrics and low-CO2 emission inflator propellants.
Airbag Market Drivers Analysis
The primary catalysts for growth in the airbag sector include a global crackdown on road safety by regulatory bodies and the rapid expansion of the automotive sector in developing nations. As governments in regions like Southeast Asia and Latin America move to align their safety protocols with European and North American standards, the mandatory installation of multiple airbags per vehicle has become a non-negotiable requirement for market entry. Additionally, the proliferation of luxury and semi-luxury vehicles, which typically feature 8 to 10 airbag modules, is significantly pushing the average unit count per vehicle higher.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict NCAP Safety Mandates | +1.8% | Global (EU, India, USA) | 2025-2034 |
| Rising Vehicle Production in Emerging Markets | +1.5% | China, India, Brazil | 2025-2030 |
| Advancements in Smart Sensor Technology | +1.2% | North America, Europe | 2026-2034 |
| Consumer Demand for High Safety Ratings | +0.9% | Global | 2025-2034 |
Airbag Market Restraints Analysis
Despite the positive outlook, the market faces significant headwinds from the high costs associated with advanced safety systems, which can limit adoption in the ultra-low-cost vehicle segment. Technical complexities, including the risk of malfunctions leading to massive global recalls, remain a constant threat to brand reputation and financial stability. Furthermore, the volatility in the pricing of specialized materials like high-tenacity nylon and chemical propellants can squeeze the profit margins of component manufacturers in a highly competitive bidding environment with OEMs.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Airbag Systems | -0.7% | Africa, Latin America | 2025-2030 |
| Complex Manufacturing and Quality Standards | -0.5% | Global | Ongoing |
| Supply Chain Vulnerabilities for Semiconductors | -0.4% | Asia, North America | 2025-2027 |
Airbag Market Opportunities Analysis
The industry is currently standing on the brink of several high-growth opportunities, particularly in the niche segments of two-wheeler safety and external pedestrian protection. With the rise of electric scooters and motorcycles globally, there is a burgeoning market for wearable and bike-mounted airbag systems. Moreover, the development of external airbags that deploy upon detecting an imminent collision with a pedestrian or cyclist represents a significant technological frontier. OEMs are also looking into modular airbag designs that can be easily integrated into various vehicle platforms, reducing engineering costs and time-to-market.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Two-Wheeler Airbag Systems | +1.4% | India, SE Asia, Italy | 2027-2034 |
| External/Pedestrian Airbag Innovation | +1.1% | Europe, Japan | 2028-2034 |
| Autonomous Vehicle Cabin Redesign | +0.8% | USA, Germany, China | 2030-2034 |
Airbag Market Challenges Impact Analysis
Technical challenges related to the integration of airbags in non-standard seating configurations in autonomous vehicles present a major hurdle for designers. There is also the persistent challenge of ensuring the long-term reliability of the chemical propellants used in inflators, which must remain functional for the entire lifespan of the vehicle, often exceeding 15 years, across extreme temperature ranges. Additionally, the increasing environmental regulations regarding the disposal and recycling of deployed airbag units and their chemical components pose a logistical and compliance challenge for the automotive aftermarket.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Recycling and Environmental Compliance | -0.3% | Europe, North America | 2026-2034 |
| System Integration in Level 4/5 AVs | -0.4% | Technologically Advanced Nations | 2029-2034 |
| Counterfeit Airbag Components in Aftermarket | -0.2% | Global | Ongoing |
Airbag Market - Updated Report Scope
The scope of this report encompasses a thorough analysis of the global airbag value chain, ranging from raw material suppliers of industrial yarns to the major tier-1 system integrators and automotive OEMs. It covers various deployment zones within the vehicle, including front, side, curtain, knee, and external segments. The research methodology combines primary interviews with industry veterans and secondary data analysis from trade associations, regulatory filings, and corporate financial reports to provide a 360-degree view of the market dynamics. Special focus is given to the impact of the EV transition on safety system architecture and the role of software in modern passive safety components.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 27.5 Billion |
| Market Forecast in 2034 | USD 47.3 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Autoliv Inc., ZF Friedrichshafen AG, Joyson Safety Systems, Toyoda Gosei Co., Ltd., Nihon Plast Co., Ltd., Ashimori Industry Co., Ltd., Hyundai Mobis, Denso Corporation, Robert Bosch GmbH, Continental AG, Daicel Corporation, Toray Industries, Inc., Kolon Industries, Inc., Global Safety Textiles, Magna International, Takata (Legacy/Joyson), Key Safety Systems (Joyson), Hella GmbH & Co. KGaA. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is categorized by various technological and application-based segments that define the competitive landscape. Type-based segmentation remains the primary way to understand market volume, where front-impact airbags still hold the lion's share due to universal mandates. However, the curtain and side-impact segments are witnessing the highest growth rates as they transition from premium features to standard safety requirements in many jurisdictions. Vehicle-type segmentation highlights the massive influence of the passenger car sector, though the heavy commercial vehicle segment is showing increased adoption of curtain airbags to prevent driver ejection during roll-over accidents.
- By Type: Front Airbag, Side Airbag, Knee Airbag, Curtain Airbag, Pedestrian Airbag.
- By Vehicle Type: Passenger Cars, LCV, HCV, Electric Vehicles (EV).
- By Component: Airbag Module, Inflator, Crash Sensors, Airbag ECU.
- By Fabric Material: Nylon 6.6, Polyester, Hybrid Fabrics.
- By Sales Channel: Original Equipment Manufacturer (OEM), Aftermarket.
Regional Highlights
The regional distribution of the airbag market is heavily skewed toward manufacturing hubs and regions with high safety compliance. The Asia-Pacific region is the clear leader, not only because of its high vehicle output but also due to the rapid implementation of safety laws in countries like India, which recently moved towards a mandatory six-airbag rule for all passenger cars. Europe remains the technological pioneer, with the highest concentration of premium vehicles equipped with advanced curtain and pedestrian airbags. North America shows a mature market profile with a focus on high-reliability systems and replacement markets, while Latin America and the Middle East represent emerging opportunities as local vehicle assembly grows and safety standards are modernized.
- Asia-Pacific: Largest and fastest-growing market, led by China's EV boom and India's new safety regulations.
- Europe: Leading in terms of technology adoption and pedestrian safety standards.
- North America: Significant market for high-impact protection and large-SUV airbag modules.
- Latin America: Rising CAGR as regional manufacturers adopt global safety platforms.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Airbag Market.- Autoliv Inc.
- ZF Friedrichshafen AG
- Joyson Safety Systems
- Toyoda Gosei Co., Ltd.
- Nihon Plast Co., Ltd.
- Ashimori Industry Co., Ltd.
- Hyundai Mobis
- Denso Corporation
- Robert Bosch GmbH
- Continental AG
- Daicel Corporation
- Toray Industries, Inc.
- Kolon Industries, Inc.
- Global Safety Textiles
- Magna International
- Hella GmbH & Co. KGaA
- TRW Automotive (Part of ZF)
- Neaton Auto Products Manufacturing
Frequently Asked Questions
What is the current market size and projected growth of the Airbag Market?
The market is estimated at USD 29.2 Billion in 2026 and is projected to grow at a CAGR of 6.2% to reach USD 47.3 Billion by 2034.
Which region is expected to dominate the market during the forecast period?
The Asia-Pacific region is expected to dominate the market, driven by high automotive production in China and increasing safety regulations in India.
What are the primary factors driving the growth of the airbag industry?
Growth is primarily driven by strict government safety mandates (NCAP), rising consumer demand for high safety ratings, and the expansion of the automotive sector in emerging economies.
What is the fastest-growing airbag segment by type?
The side-impact and curtain airbag segments are the fastest-growing due to their increasing inclusion in standard safety packages for mid-range vehicles.
How is the transition to autonomous vehicles affecting the airbag market?
Autonomous vehicles are driving the development of new airbag placements and "smart" deployment systems that accommodate non-traditional seating arrangements and occupant postures.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
