Air Cargo Market
Air Cargo Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711652 | Published On : November 11, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Air Cargo Market Size
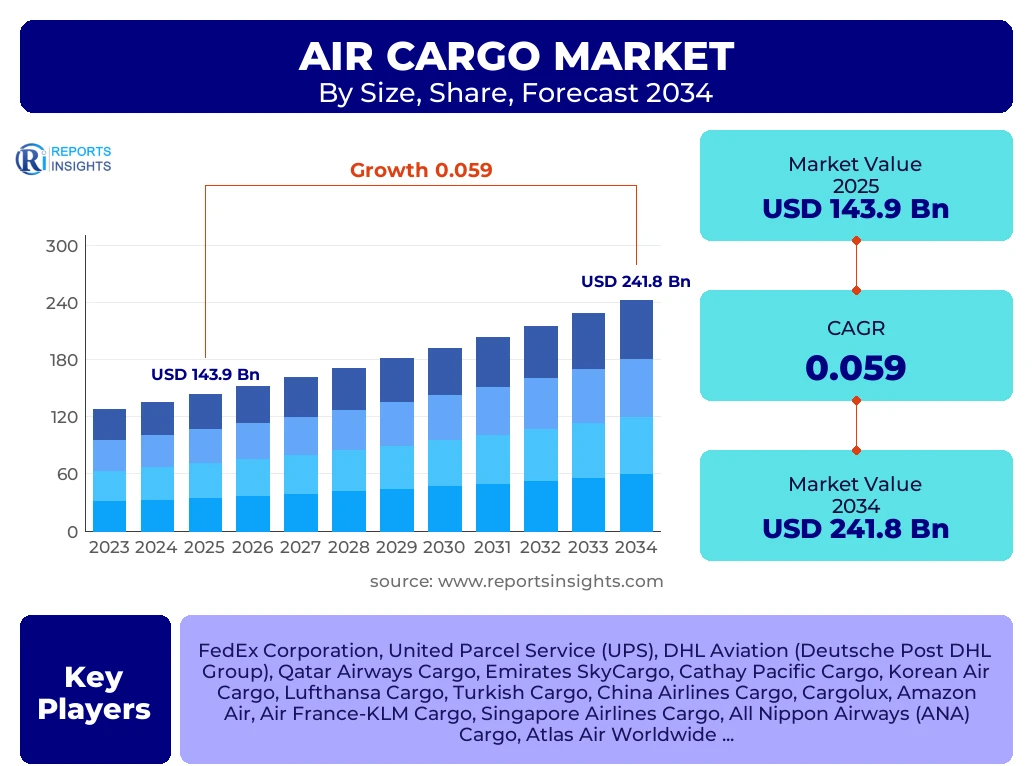
According to Reports Insights Consulting Pvt Ltd, The Air Cargo Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.9% between 2025 and 2034. The market is estimated at USD 152.4 Billion in 2026 and is projected to reach USD 241.8 Billion by the end of the forecast period in 2034.
Key Air Cargo Market Trends & Insights
The global air cargo sector is undergoing a profound structural transformation characterized by the rapid integration of digital technologies and a heightened focus on sustainability. As global supply chains become more complex, the demand for speed and reliability has positioned air freight as a critical component of international trade, particularly for high-value and time-sensitive commodities. The resurgence of belly cargo capacity following the stabilization of passenger aviation, alongside the expansion of dedicated freighter fleets, has created a more balanced supply-demand dynamic. Furthermore, the industry is witnessing a significant shift toward data-driven operations, with artificial intelligence and blockchain being deployed to enhance transparency, optimize route planning, and streamline customs documentation.
Regional dynamics play a pivotal role in shaping the market landscape. Asia-Pacific continues to dominate the sector, driven by robust manufacturing outputs in China, Vietnam, and India, combined with a burgeoning middle class that fuels cross-border e-commerce. In contrast, the North American and European markets are focusing on modernizing logistics infrastructure and adopting Sustainable Aviation Fuel (SAF) to meet stringent environmental mandates. The competitive benchmarking of major players reveals a trend toward "end-to-end" logistics solutions, where traditional air carriers are expanding their ground handling and last-mile delivery capabilities to compete with integrated express providers.
- Largest Region: Asia-Pacific remains the largest regional market, accounting for over 35% of the total market share due to its status as a global manufacturing hub.
- Fastest Growing Region: South Asia, particularly India and Southeast Asian nations like Vietnam, are experiencing the highest CAGR due to shifting manufacturing bases and infrastructure investment.
- Largest Segment by Service: The Regular Cargo segment currently holds the largest share, although the Express Cargo segment is growing at a faster rate.
- Dominant End-User: The Electronics and High-Tech industry remains the primary revenue generator for air cargo providers.
Key Takeaways Air Cargo Market Size & Forecast
The long-term outlook for the air cargo market is underpinned by the permanent shift in consumer behavior toward online shopping and the global necessity for resilient medical supply chains. Forecasts suggest that while cyclical economic fluctuations may impact short-term volumes, the underlying demand for air transport as a "just-in-time" logistics solution remains unshakable. Stakeholders are increasingly prioritizing investments in specialized handling facilities, such as temperature-controlled environments for pharmaceuticals and secure zones for high-value electronics, to capture higher-margin market segments. The transition from legacy systems to cloud-based logistics platforms is also expected to be a primary catalyst for operational efficiency and market expansion through 2034.
- E-commerce Growth: Cross-border e-commerce is expected to contribute nearly 25% of total air cargo traffic by 2034.
- Fleet Modernization: There is an increasing trend in the conversion of older passenger aircraft into freighters (P2F) to meet the demand for dedicated cargo capacity.
- Leading Country: China continues to lead in terms of both export volume and infrastructure development, including the expansion of specialized cargo airports.
- Sustainability Impact: Environmental regulations are forcing carriers to invest in fuel-efficient aircraft, which will influence long-term capital expenditure strategies.
Air Cargo Market Drivers Analysis
The primary catalysts for the air cargo market involve the exponential rise of global e-commerce and the critical need for rapid transport of perishables and life-saving pharmaceuticals. As consumers demand faster delivery times across borders, air freight provides the only viable solution for meeting these expectations. Additionally, the ongoing digitization of logistics processes, including the implementation of electronic Air Waybills (e-AWB), is significantly reducing processing times and costs, making air cargo more accessible to small and medium-sized enterprises.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Cross-Border E-commerce | +2.1% | Global (China, USA, Germany) | 2025 - 2034 |
| Demand for Pharmaceutical Cold Chain | +1.4% | Europe & North America | 2025 - 2030 |
| High-Tech Product Launch Cycles | +1.2% | Asia-Pacific (Taiwan, South Korea) | 2026 - 2034 |
Air Cargo Market Restraints Analysis
Despite strong growth prospects, the market faces significant headwinds from volatile jet fuel prices and the increasing stringency of environmental regulations. Carbon emission taxes and noise restrictions at major urban airports are raising operational costs and limiting nighttime flying windows. Furthermore, the modal shift back to maritime transport for certain goods—driven by improvements in ocean freight reliability and significantly lower costs—poses a threat to air cargo volumes for less time-sensitive shipments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Jet Fuel Pricing | -0.8% | Global | Continuous |
| Strict Environmental & Carbon Mandates | -0.6% | European Union | 2026 - 2034 |
| Trade Protectionism & Tariffs | -0.5% | USA - China Trade Route | 2025 - 2028 |
Air Cargo Market Opportunities Analysis
The integration of autonomous cargo drones for middle-mile delivery and the adoption of Sustainable Aviation Fuel (SAF) represent major frontiers for market expansion. There is also a significant opportunity in the development of specialized "smart" warehouses equipped with AI and IoT to facilitate faster sorting and reduced dwell times. As emerging economies in Africa and Latin America improve their airport infrastructure, these regions present untapped potential for new trade corridors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Sustainable Aviation Fuel (SAF) | +0.9% | Europe, North America | 2027 - 2034 |
| Autonomous Drone Delivery Systems | +0.7% | USA, China, Middle East | 2028 - 2034 |
| Digitalization & Blockchain Integration | +1.1% | Global | 2025 - 2034 |
Air Cargo Market Challenges Impact Analysis
One of the most pressing challenges is the chronic shortage of skilled personnel, including pilots and specialized ground handling staff, which can lead to operational bottlenecks. Additionally, the industry must navigate complex geopolitical tensions that can abruptly close airspace or disrupt established trade routes, necessitating agile and costly contingency planning. The physical capacity of major hub airports is also reaching its limit, requiring massive capital investment to prevent severe congestion.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Skilled Labor & Pilot Shortages | -0.4% | North America, Europe | 2025 - 2030 |
| Airport Infrastructure Congestion | -0.5% | Asia-Pacific (Major Hubs) | 2026 - 2034 |
| Cybersecurity Risks in Logistics Networks | -0.3% | Global | 2025 - 2034 |
Air Cargo Market - Updated Report Scope
This report provides a comprehensive analysis of the global air cargo industry, covering the period from 2020 to 2034. It examines the market by service type, aircraft type, and end-user industry across six major geographic regions. The scope includes an in-depth evaluation of the competitive landscape, identifying key strategies used by top-tier carriers and integrators to maintain market leadership in an increasingly volatile global environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 143.9 Billion |
| Market Forecast in 2034 | USD 241.8 Billion |
| Growth Rate | 5.9% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | FedEx Corporation, United Parcel Service (UPS), DHL Aviation (Deutsche Post DHL Group), Qatar Airways Cargo, Emirates SkyCargo, Cathay Pacific Cargo, Korean Air Cargo, Lufthansa Cargo, Turkish Cargo, China Airlines Cargo, Cargolux, Amazon Air, Air France-KLM Cargo, Singapore Airlines Cargo, All Nippon Airways (ANA) Cargo, Atlas Air Worldwide, Nippon Cargo Airlines, Polar Air Cargo, Etihad Cargo, Cargojet. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the air cargo market reflects the diverse operational requirements of modern commerce. By service type, the market is split between Regular and Express cargo, with Express showing significant momentum due to the "Amazon effect" and the need for overnight delivery. The aircraft type segment highlights the strategic importance of Belly Cargo, which offers cost-effective capacity on passenger routes, versus Dedicated Freighters that provide reliability and specialized handling for heavy or hazardous goods.
- By Service Type:
- Express Cargo: Driven by high-priority shipments and e-commerce, this segment is growing the fastest.
- Regular Cargo: The backbone of international trade for general commodities, representing the largest volume.
- By Aircraft Configuration:
- Passenger Aircraft (Belly Cargo): Utilizes the hold of commercial passenger flights; highly dependent on tourism and business travel recovery.
- Freighters: Maindeck cargo planes designed solely for freight; critical for oversized and heavy industrial equipment.
- By Industry Vertical:
- Healthcare and Pharmaceuticals: Focuses on temperature-sensitive logistics and GDP compliance.
- High-Tech and Electronics: Driven by short product lifecycles and high value-to-weight ratios.
- Automotive: Primarily used for urgent spare parts and "line-down" situations in manufacturing.
Regional Highlights
- Asia-Pacific: The region is the global powerhouse for air cargo, led by China's massive export economy and the rising manufacturing hubs in Southeast Asia. It holds the largest market share and is expected to maintain this dominance through 2034.
- North America: Home to the world’s largest express integrators (FedEx and UPS), this region focuses on advanced logistics tech and is the primary hub for the e-commerce revolution.
- Europe: A key hub for pharmaceutical and automotive exports. Germany (Frankfurt) and the Netherlands (Amsterdam Schiphol) serve as critical gateways for transatlantic and Eurasian trade.
- Middle East: Leveraging its geographic position between East and West, carriers like Qatar and Emirates have turned Doha and Dubai into central global transit hubs.
- Latin America & MEA: These regions are emerging as significant players in the export of perishables and flowers, with increasing investments in cold-chain infrastructure.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Air Cargo Market.- FedEx Corporation
- United Parcel Service (UPS)
- DHL Aviation (Deutsche Post DHL Group)
- Qatar Airways Cargo
- Emirates SkyCargo
- Cathay Pacific Cargo
- Korean Air Cargo
- Lufthansa Cargo
- Turkish Cargo
- China Airlines Cargo
- Cargolux
- Amazon Air
- Air France-KLM Cargo
- Singapore Airlines Cargo
- All Nippon Airways (ANA) Cargo
- Atlas Air Worldwide
- Nippon Cargo Airlines
- Polar Air Cargo
- Etihad Cargo
- Cargojet
Frequently Asked Questions
What is the projected growth rate of the Air Cargo market?
The global air cargo market is expected to grow at a Compound Annual Growth Rate (CAGR) of 5.9% through 2034, reaching a total value of approximately USD 241.8 Billion.
Which industry is the largest consumer of air cargo services?
The electronics and high-tech sector currently represents the largest end-user segment, followed closely by the retail and pharmaceutical industries.
How is e-commerce affecting the air cargo industry?
E-commerce is a primary driver, increasing the demand for express delivery services and dedicated freighter capacity to handle high volumes of small, time-sensitive parcels.
What role does belly cargo play in the market?
Belly cargo, or the transport of freight in the lower hold of passenger aircraft, provides a significant portion of global capacity and is often more cost-effective than dedicated freighters.
What are the main challenges facing air cargo carriers today?
Key challenges include volatile fuel costs, strict environmental regulations regarding carbon emissions, and the need for significant capital investment in digital infrastructure.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
