Agricultural Inoculants Market
Agricultural Inoculants Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711597 | Published On : November 07, 2026 |
Format : 


 | Author : Shawn Patel
Agricultural Inoculants Market Size
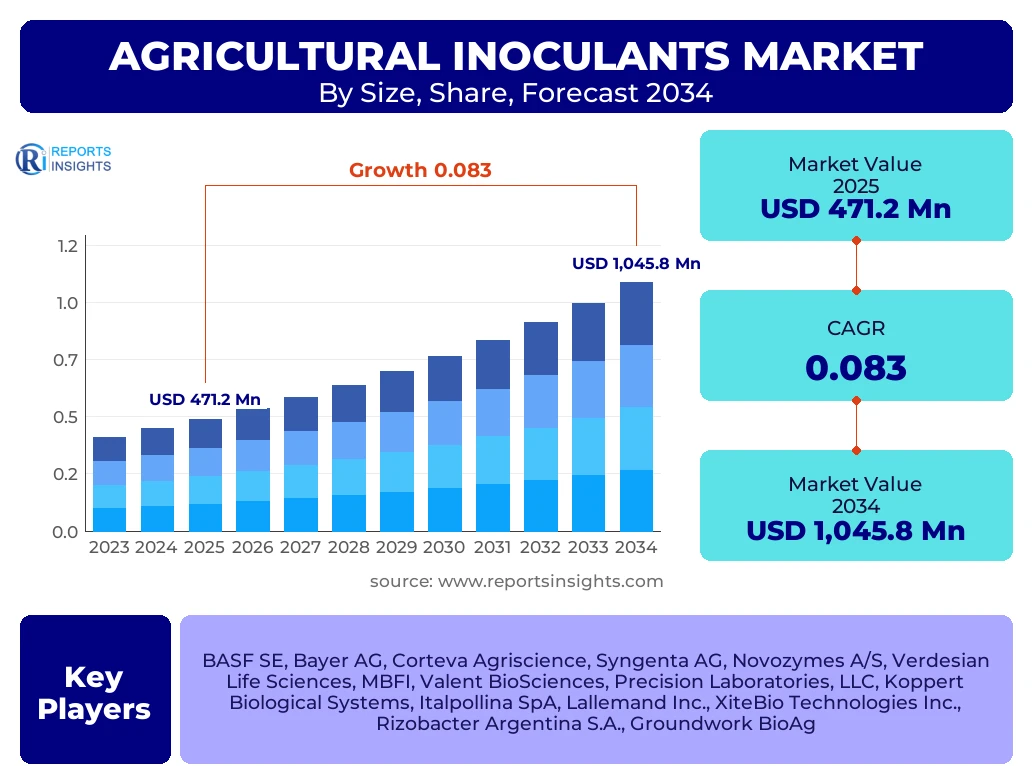
According to Reports Insights Consulting Pvt Ltd, The Agricultural Inoculants Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.3% between 2025 and 2034. The market is estimated at USD 510.4 Million in 2026 and is projected to reach USD 1,045.8 Million by the end of the forecast period in 2034.
Key Agricultural Inoculants Market Trends & Insights
The global Agricultural Inoculants market is undergoing a significant paradigm shift as the agricultural sector transitions from traditional chemical-intensive practices to biologically integrated systems. This transition is primarily fueled by the increasing consumer demand for organic produce and the stringent regulatory environment surrounding synthetic fertilizers and pesticides. Modern inoculants, which leverage beneficial microorganisms like nitrogen-fixing bacteria and mycorrhizal fungi, are being recognized not just as supplements but as essential components of integrated crop management. Advances in microbial encapsulation and formulation technologies have significantly enhanced the shelf life and field efficacy of these products, addressing one of the primary historical barriers to adoption. Furthermore, the integration of precision agriculture tools allows for site-specific application of inoculants, optimizing microbial colonization and ensuring maximum yield returns for growers across diverse pedoclimatic conditions.
- Largest Region: North America currently holds the largest market share, driven by a highly mechanized agricultural sector and early adoption of biological soil health solutions.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR due to rapid population growth, increasing food security concerns, and government-led initiatives promoting sustainable farming in India and China.
- Largest Segment: By type, Bacterial Inoculants (specifically Rhizobacteria) dominate the market share owing to their proven efficacy in nitrogen fixation for pulse and oilseed crops.
- Dominant Application Mode: Seed Treatment remains the preferred application method due to its cost-effectiveness, ease of use, and targeted delivery of microbes to the rhizosphere.
Key Takeaways Agricultural Inoculants Market Size & Forecast
The forecast period from 2025 to 2034 represents a decade of industrial maturity for agricultural inoculants. The market is expected to witness a double-digit growth trajectory in specific sub-segments like fungal inoculants, as their role in phosphate solubilization and drought resistance becomes more critical in the face of climate change. Stakeholders are increasingly focusing on the development of multi-strain microbial consortia that offer synergistic benefits, such as simultaneous nutrient uptake and pathogen suppression. The market's expansion is further supported by the rising cost of synthetic nitrogenous fertilizers, making biological nitrogen fixation a commercially viable and environmentally superior alternative. Strategic partnerships between biotechnology startups and major agrochemical players are accelerating product pipelines, ensuring that next-generation inoculants reach global markets more efficiently.
- Leading Country: The United States leads the global market in terms of value, supported by extensive research and development in microbial genomics.
- Primary Growth Catalyst: The shift toward Regenerative Agriculture is the most significant driver, prioritizing soil microbiome health as a core asset for long-term productivity.
- Segmental Insight: Oilseeds and Pulses are the primary crop types utilizing inoculants, but significant expansion is being noted in the Fruits and Vegetables segment for export-oriented quality improvement.
- Technological Focus: Development of liquid formulations with improved stabilizing agents is expected to outpace traditional peat-based carriers.
Agricultural Inoculants Market Drivers Analysis
The primary driver for the Agricultural Inoculants market is the escalating global demand for sustainable food production. As the world's population approaches 9 billion, the pressure on existing arable land has led to soil degradation. Agricultural inoculants offer a restorative solution by replenishing the natural microbial diversity of the soil, thereby improving nutrient use efficiency (NUE) and reducing the environmental footprint of farming. This aligns with the United Nations Sustainable Development Goals (SDGs) and various regional "Green Deal" initiatives that mandate a reduction in chemical runoff and greenhouse gas emissions from nitrogenous fertilizers.
Another critical driver is the rising cost and supply chain volatility of synthetic fertilizers. Geopolitical tensions and energy price fluctuations have made chemical inputs less predictable for farmers. In contrast, biological inoculants provide a stable, cost-efficient alternative that enhances the plant's natural ability to sequester nitrogen from the atmosphere. Additionally, the growing consumer preference for "clean label" and organic food products has incentivized retailers and food processors to enforce stricter biological standards on their supply chains, compelling farmers to adopt microbial solutions to maintain market access.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift to Organic and Regenerative Agriculture | +3.2% | Europe and North America | 2025-2034 |
| Rising Prices of Synthetic Nitrogen Fertilizers | +2.5% | Global | 2025-2029 |
| Advances in Microbial Encapsulation Technology | +1.8% | United States, Germany, Japan | 2026-2034 |
| Government Subsidies for Bio-fertilizers | +0.8% | India, Brazil, China | 2025-2030 |
Agricultural Inoculants Market Restraints Analysis
Despite the optimistic growth outlook, the market faces significant restraints, most notably the limited shelf life and environmental sensitivity of live microbial products. Unlike chemical fertilizers, which are stable under various storage conditions, biological inoculants contain living organisms that can perish if exposed to extreme temperatures or improper handling. This poses a logistical challenge for distributors, particularly in developing regions with inadequate cold chain infrastructure. Farmers often perceive these products as "unreliable" if they do not see immediate visible results, which can hinder the adoption rate compared to the rapid greening effect of synthetic nitrogen.
Furthermore, the regulatory landscape for biologicals remains fragmented and complex. In many jurisdictions, agricultural inoculants are governed by disparate laws that lack a unified definition for "bio-stimulants" or "bio-fertilizers." The high cost and time required for product registration, combined with the necessity of proving efficacy across different soil types and climates, can be a deterrent for small to medium-sized enterprises (SMEs) looking to enter the market. This regulatory bottleneck often delays the introduction of innovative microbial strains to the field.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Short Shelf Life and Storage Sensitivities | -1.5% | Africa, Southeast Asia | 2025-2034 |
| Fragmented Regulatory Frameworks | -1.2% | European Union, Brazil | 2025-2028 |
Agricultural Inoculants Market Opportunities Analysis
Significant opportunities exist in the development of "Climate-Smart" microbial solutions. As global warming increases the frequency of abiotic stresses like drought, salinity, and heatwaves, there is a burgeoning market for inoculants specifically engineered to enhance plant resilience. Mycorrhizal fungi and certain Bacilli strains have shown remarkable potential in improving water retention and osmotic adjustment in crops. Tailoring microbial consortia for specific stress-prone regions represents a high-value niche for biotechnology firms. Furthermore, the integration of CRISPR and other gene-editing tools to optimize microbial traits—without necessarily creating transgenic organisms—could lead to highly efficient strains that perform consistently across varied environments.
The expansion into non-leguminous crops also presents a massive untapped opportunity. Historically, inoculants have been synonymous with nitrogen fixation in legumes (soybeans, peas, lentils). However, research into endophytes and diazotrophs that can colonize cereals like maize, wheat, and rice is gaining momentum. If biological nitrogen fixation can be reliably scaled for global staple crops, the market size could triple. Additionally, the digital agriculture boom allows for the creation of "Microbiome Maps," where farmers can receive customized inoculant recommendations based on real-time soil testing data, opening doors for personalized biological service models.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Cereals and Grains (Maize, Wheat) | +4.5% | United States, China, Russia | 2027-2034 |
| Microbial Solutions for Abiotic Stress Tolerance | +3.0% | Middle East, Australia, Africa | 2026-2034 |
| Direct-to-Farmer Digital Advisory Platforms | +1.5% | Global | 2025-2034 |
Agricultural Inoculants Market Challenges Impact Analysis
The primary challenge for the agricultural inoculants market is the inconsistency of field performance due to competition with native soil microflora. When a commercial inoculant is introduced to the soil, it must compete with thousands of indigenous microbial species for nutrients and space. In many cases, the introduced strains fail to establish a significant population, leading to sub-optimal results. This variability makes it difficult for manufacturers to provide a "guaranteed" yield increase, which is a key metric for risk-averse farmers. Overcoming this "competition barrier" requires advanced formulation techniques that protect the inoculant during the initial colonization phase.
Another major challenge is the compatibility of biological inoculants with existing chemical seed treatments. Many farmers use seeds pre-treated with synthetic fungicides and insecticides. These chemicals can be toxic to the beneficial microbes in the inoculant, negating their benefits. Developing "chemical-tolerant" microbial strains or specialized coatings that separate the biological and chemical components is a complex R&D hurdle. Additionally, there is a lack of technical awareness among smallholder farmers in emerging economies regarding the correct application timing and dosage, which can lead to product failure and loss of trust in biological solutions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition with Indigenous Soil Microbes | -2.0% | Global | 2025-2034 |
| Compatibility with Chemical Seed Treatments | -1.5% | North America, LATAM | 2025-2030 |
Agricultural Inoculants Market - Updated Report Scope
This report provides a granular analysis of the global agricultural inoculants industry, covering microbial types, application modes, and crop categories. It evaluates the impact of macroeconomic factors, such as fertilizer price volatility and environmental regulations, on market growth. The scope includes an in-depth assessment of the competitive landscape, identifying key players and their strategic moves in the R&D space, as well as a regional breakdown that highlights growth pockets across six major geographies. The study is designed to provide actionable insights for stakeholders ranging from microbial manufacturers to venture capitalists and agricultural policymakers.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 471.2 Million |
| Market Forecast in 2034 | USD 1,045.8 Million |
| Growth Rate | 8.3% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta AG, Novozymes A/S, Verdesian Life Sciences, MBFI, Valent BioSciences, Precision Laboratories, LLC, Koppert Biological Systems, Italpollina SpA, Lallemand Inc., XiteBio Technologies Inc., Rizobacter Argentina S.A., Groundwork BioAg |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The agricultural inoculants market is segmented based on the biological agent, the method through which it is introduced to the plant, and the specific crop category it serves. Understanding these segments is crucial for identifying high-growth niches. Currently, the bacterial segment, particularly nitrogen-fixing bacteria, represents the largest share due to its established use in soybean and pulse farming. However, the fungal segment is witnessing the fastest growth as mycorrhizal inoculants are increasingly recognized for their role in enhancing phosphorus uptake and improving soil structure. The segmentation also reflects a shift in application modes, where seed treatment is being supplemented by in-furrow and foliar applications to provide microbial support throughout the plant life cycle.
- By Type:
- Bacterial Inoculants (Rhizobia, Azotobacter, Azospirillum, Phosphorus-Solubilizing Bacteria)
- Fungal Inoculants (Arbuscular Mycorrhizal Fungi, Ectomycorrhizal Fungi, Trichoderma spp.)
- Other Microbial Inoculants (Algal, Actinomycetes)
- By Mode of Application:
- Seed Treatment (Dry and Liquid formulations)
- Soil Treatment (In-furrow, Drenching)
- Foliar Spray
- By Crop Type:
- Cereals & Grains (Corn, Wheat, Rice, Barley)
- Oilseeds & Pulses (Soybean, Peanut, Chickpea, Lentils)
- Fruits & Vegetables (Leafy greens, Solanaceous crops, Berries)
- Other Crops (Forage, Ornamental, Turf)
Regional Highlights
- North America: The largest market for agricultural inoculants, dominated by the United States and Canada. This region benefits from a large soybean acreage, high awareness of soil health, and a robust ecosystem of biotechnology startups. Precision agriculture integration is highest here.
- Europe: A significant market characterized by strict regulations on chemical inputs (e.g., the Farm to Fork Strategy). Countries like France, Germany, and Spain are leading in the adoption of bio-stimulants and fungal inoculants for high-value viticulture and horticulture.
- Asia Pacific: The fastest-growing region. India and China are witnessing a massive push toward organic farming and reduced urea consumption. Government subsidies for bio-fertilizers and a large area under rice and pulse cultivation are primary growth drivers.
- Latin America: Brazil and Argentina are global hubs for soybean production, making them critical markets for Rhizobia-based inoculants. The region is seeing a trend toward large-scale "on-farm" inoculant production, though commercial high-quality products still hold the majority share.
- Middle East & Africa: An emerging market focusing on inoculants for dryland farming. Projects in Saudi Arabia and Egypt are utilizing microbes to improve crop survival in saline and arid conditions, while Sub-Saharan Africa is seeing growth through international development programs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Agricultural Inoculants Market.- BASF SE
- Bayer AG
- Corteva Agriscience
- Syngenta AG
- Novozymes A/S
- Verdesian Life Sciences
- MBFI (Microbial Biological Fertilizers International)
- Valent BioSciences (Sumitomo Chemical)
- Precision Laboratories, LLC
- Koppert Biological Systems
- Italpollina SpA (Hello Nature)
- Lallemand Inc.
- XiteBio Technologies Inc.
- Rizobacter Argentina S.A.
- Groundwork BioAg
- BioWorks, Inc.
- AgBiome, Inc.
- Advanced Biological Marketing (ABM)
- TerraMax, Inc.
- Legume Technology
Frequently Asked Questions
What are agricultural inoculants and how do they function?
Agricultural inoculants are formulations containing live beneficial microorganisms, such as bacteria or fungi, applied to seeds or soil. They function by establishing a symbiotic or associative relationship with plant roots, enhancing nutrient uptake (like nitrogen and phosphorus), producing plant growth hormones, and improving the plant’s resilience to environmental stress and pathogens.
Why is the agricultural inoculants market growing so rapidly?
The growth is primarily driven by the global shift toward sustainable agriculture and organic farming. Increased regulatory pressure to reduce synthetic fertilizer use, the rising cost of chemical inputs, and a better understanding of the soil microbiome's role in long-term crop productivity are key factors accelerating market adoption.
Which crop type is the largest consumer of inoculants?
Oilseeds and pulses, particularly soybeans, are the largest consumers. This is because these crops have a natural symbiotic relationship with Rhizobia bacteria, which are the most common and effective type of commercial inoculant used to fix atmospheric nitrogen directly into the plant.
What are the main challenges in using microbial inoculants?
The main challenges include the short shelf life of living organisms, sensitivity to extreme environmental conditions (heat, UV light), and competition from indigenous soil microbes that can prevent the inoculant from successfully colonizing the plant roots. Compatibility with chemical seed treatments is also a technical hurdle.
How is technology changing the inoculant industry?
Technology is revolutionizing the industry through advanced encapsulation (protecting microbes from stress), the development of multi-strain consortia that offer multiple benefits, and the use of genomic sequencing to identify more robust microbial strains. Additionally, digital agriculture tools now allow for precision application of inoculants based on specific soil health data.
Author
S
Shawn Patel is a Manger Agriculture Research Industry with 6+ years of experience in the Agriculture Industry. He specializes in agricultural market intelligence, crop production analysis, agribusiness trend assessment, demand forecasting, competitive benchmarking, supply chain evaluation, precision agriculture technologies, commodity pricing analysis, and market sizing across farming and agricultural input sectors. His research combines industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, understand evolving market trends, and strengthen their competitive positioning in the global agriculture industry.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
