Advanced Battery Energy Storage System Market
Advanced Battery Energy Storage System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710984 | Published On : September 25, 2026 |
Format : 


 | Author : Seema Bhateja
Advanced Battery Energy Storage System Market Size
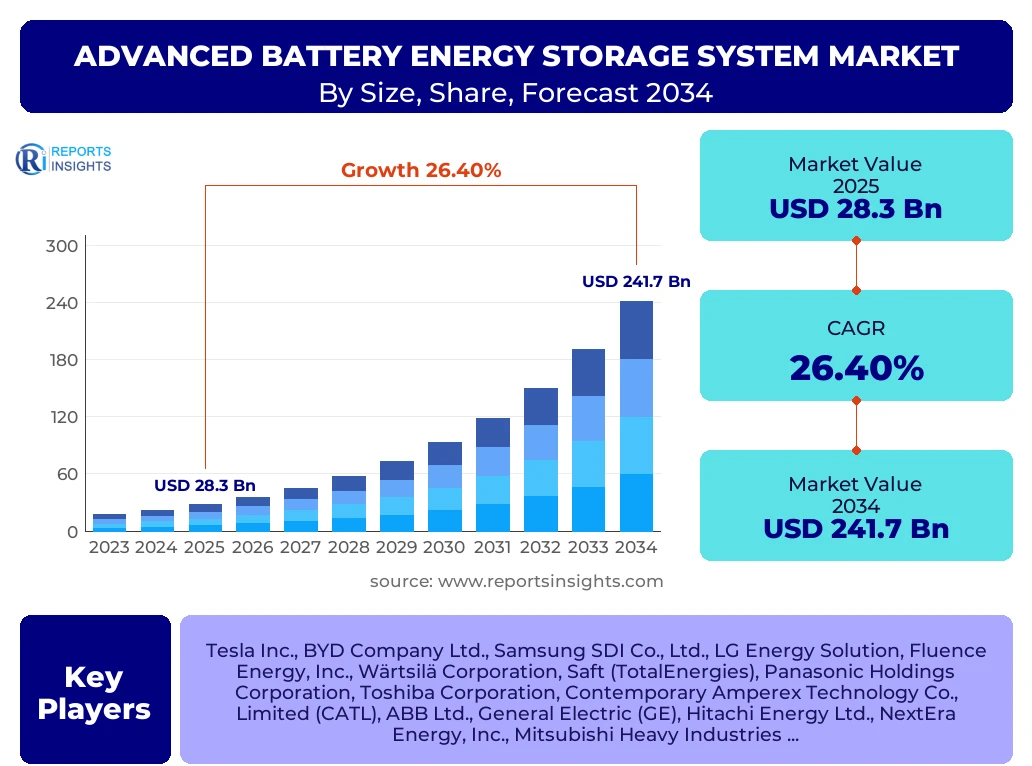
According to Reports Insights Consulting Pvt Ltd, The Advanced Battery Energy Storage System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 26.4% between 2026 and 2034. The market is estimated at USD 35.8 Billion in 2026 and is projected to reach USD 241.7 Billion by the end of the forecast period in 2034.
Key Advanced Battery Energy Storage System Market Trends & Insights
The global transition toward sustainable energy landscapes is the primary catalyst for the exponential growth of the advanced battery energy storage system market. Stakeholders are increasingly focusing on the integration of intermittent renewable energy sources, such as solar and wind, into existing power grids, necessitating robust storage solutions to ensure stability and reliability. Competitive benchmarking indicates a shift from traditional lead-acid systems toward high-density lithium-ion and emerging solid-state technologies. Furthermore, the rise of decentralized energy systems and the microgrid movement are fundamentally altering the demand profile, moving from centralized utility-scale projects to localized commercial and industrial installations. Analytical data suggests that the convergence of artificial intelligence with battery management systems is optimizing energy discharge cycles and extending the operational lifecycle of storage units, providing a significant competitive edge to early adopters of these smart technologies.
- Largest region: Asia Pacific currently holds the largest market share, driven by massive infrastructure investments in China and India.
- Fastest growing region: North America is anticipated to be the fastest-growing region due to aggressive decarbonization targets and supportive federal legislation.
- Largest segment: The Lithium-Ion Battery segment remains the dominant technology due to its declining costs and high energy density.
- Dominant application: Utility-scale installations account for the majority of the market value as grid operators seek to manage peak loads and frequency regulation.
Key Takeaways Advanced Battery Energy Storage System Market Size & Forecast
The market forecast indicates a decade of unprecedented expansion characterized by technological diversification and economies of scale. The aggressive reduction in battery pack prices, which have fallen by over 80 percent in the last decade, has reached a tipping point where energy storage is now economically viable without heavy reliance on subsidies in many jurisdictions. Strategic analysis reveals that energy security concerns, heightened by geopolitical volatility, are prompting nations to invest in domestic storage capacities to reduce dependence on imported fuels. Forecast models suggest that by 2034, the integration of long-duration energy storage (LDES) will be a critical component of the market, addressing the limitations of short-duration lithium-ion systems for seasonal energy shifts. This evolution will be supported by a robust supply chain for raw materials and a growing emphasis on circular economy practices, including battery recycling and second-life applications.
- Leading country: China leads the global market in both manufacturing capacity and domestic deployment.
- Grid Modernization: Modernizing aging grid infrastructure is a critical requirement across Europe and North America to prevent blackouts.
- Policy Impact: The Inflation Reduction Act (IRA) in the United States and the European Green Deal are the most significant regulatory tailwinds.
- Technology Shift: Increased interest in Lithium Iron Phosphate (LFP) chemistries over Nickel Manganese Cobalt (NMC) due to cost and safety benefits.
Advanced Battery Energy Storage System Market Drivers Analysis
The market is primarily driven by the global imperative to achieve net-zero emissions, which requires a fundamental restructuring of power generation and distribution. The increasing penetration of electric vehicles (EVs) is also creating a secondary market for battery technologies and driving down costs through manufacturing scale. Additionally, the need for grid resilience against extreme weather events is pushing utilities to adopt distributed storage solutions to maintain power continuity.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Renewable Energy Integration | +8.5% | Global / EU / APAC | 2025 - 2034 |
| Declining Battery Manufacturing Costs | +6.2% | China / USA / Germany | 2025 - 2030 |
| Government Incentives and Subsidies | +5.4% | North America / Europe | 2025 - 2028 |
| Rising Demand for Grid Stability | +4.3% | Global | 2026 - 2034 |
Advanced Battery Energy Storage System Market Restraints Analysis
Despite strong growth, the market faces significant restraints, including the high initial capital expenditure required for large-scale BESS projects. Supply chain vulnerabilities, particularly regarding the sourcing of critical minerals like lithium, cobalt, and graphite, present ongoing risks to price stability and project timelines. Furthermore, safety concerns regarding thermal runaway and fire hazards in large battery installations continue to invite stringent regulatory scrutiny.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -3.5% | Global | 2025 - 2029 |
| Stringent Safety Regulations | -2.1% | EU / North America | 2025 - 2034 |
| High Installation Costs | -1.8% | Developing Nations | 2025 - 2027 |
Advanced Battery Energy Storage System Market Opportunities Analysis
The emergence of second-life battery applications represents a massive opportunity to lower costs and improve the sustainability of the industry. By repurposing EV batteries for stationary storage, companies can significantly reduce the environmental footprint and capital requirements. Additionally, the development of solid-state and flow battery technologies offers a path toward safer, longer-lasting, and more efficient storage systems that could disrupt the current dominance of liquid-electrolyte lithium-ion batteries.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Second-Life Battery Repurposing | +4.8% | Japan / South Korea / USA | 2027 - 2034 |
| Solid-State Battery Commercialization | +3.9% | Global | 2028 - 2034 |
| Microgrid Expansion in Rural Areas | +3.2% | Africa / SE Asia | 2026 - 2034 |
Advanced Battery Energy Storage System Market Challenges Impact Analysis
The primary challenge lies in the lack of standardized global protocols for battery performance and safety, which complicates cross-border trade and technology adoption. Environmental concerns regarding the end-of-life disposal and recycling of batteries are also gaining prominence, requiring the industry to develop efficient recycling infrastructures. Moreover, the integration of storage systems with legacy grid software requires sophisticated digital upgrades that many older utilities are slow to implement.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Recycling Infrastructure | -2.4% | Global | 2025 - 2034 |
| Interoperability with Legacy Systems | -1.9% | North America / Europe | 2025 - 2030 |
| Geopolitical Trade Barriers | -1.5% | China / USA / EU | 2025 - 2034 |
Advanced Battery Energy Storage System Market - Updated Report Scope
This report provides an exhaustive analysis of the global advanced battery energy storage system landscape, covering technological advancements, economic indicators, and regulatory frameworks. It examines the market through multiple lenses, including battery chemistry, power capacity, and end-user segments, while providing a detailed roadmap for future growth and investment opportunities. The scope includes a meticulous assessment of the competitive landscape and regional dynamics that are shaping the next decade of energy storage.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 28.3 Billion |
| Market Forecast in 2034 | USD 241.7 Billion |
| Growth Rate | 26.4% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Tesla Inc., BYD Company Ltd., Samsung SDI Co., Ltd., LG Energy Solution, Fluence Energy, Inc., Wärtsilä Corporation, Saft (TotalEnergies), Panasonic Holdings Corporation, Toshiba Corporation, Contemporary Amperex Technology Co., Limited (CATL), ABB Ltd., General Electric (GE), Hitachi Energy Ltd., NextEra Energy, Inc., Mitsubishi Heavy Industries, Ltd., Sungrow Power Supply Co., Ltd., Enphase Energy, Inc., SolarEdge Technologies, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the advanced battery energy storage system market reflects the diverse needs of the energy sector, ranging from high-capacity utility requirements to smaller, localized residential systems. Each segment is influenced by distinct drivers, such as regulatory mandates for utilities or the desire for energy independence among residential consumers. Technological segmentation further highlights the transition from established chemistries to next-generation materials designed for specific performance metrics like discharge duration and thermal stability.
- By Battery Technology:
- Lithium-Ion (NMC, LFP, NCA)
- Flow Batteries (Vanadium Redox, Zinc-Bromine)
- Sodium-Based (Sodium-Sulfur, Sodium-Ion)
- Lead-Acid (Advanced Lead-Carbon)
- Others (Nickel-Cadmium, Solid-State)
- By Application:
- Utility-Scale (Grid-level storage, ancillary services)
- Commercial & Industrial (Peak shaving, backup power)
- Residential (Self-consumption, EV charging integration)
- By Grid Connection:
- On-grid (Grid-tied systems)
- Off-grid (Remote power systems, islanded microgrids)
- By Discharge Duration:
- Short Duration (Under 4 hours)
- Long Duration (Over 4 hours to seasonal)
Regional Highlights
Regional dynamics are significantly influenced by local energy policies, existing grid infrastructure, and the availability of renewable resources. Asia Pacific remains the powerhouse of the industry, not only as the largest consumer but also as the primary hub for battery manufacturing. North America and Europe are focusing on policy-driven growth, aiming to secure domestic supply chains and reduce reliance on external providers for critical energy technologies.
- Asia Pacific: Holds approximately 45% of the market share. China is the primary driver, followed by rapid adoption in Australia, India, and Japan. The region benefits from localized supply chains and aggressive government mandates for renewable energy integration.
- North America: Projected as the fastest-growing market. The United States is at the forefront, supported by the Investment Tax Credit (ITC) for standalone storage and large-scale projects in California and Texas.
- Europe: Growth is driven by the urgent need for energy sovereignty and the decommissioning of coal and nuclear plants. Germany, the UK, and Italy are leading the deployment of both utility and residential storage.
- Middle East & Africa: Increasing interest in large-scale solar plus storage projects in Saudi Arabia and the UAE to diversify energy portfolios beyond hydrocarbons.
- Latin America: Emerging opportunities in Chile and Brazil, particularly in the mining sector and for stabilizing grids with high solar penetration.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Advanced Battery Energy Storage System Market.- Tesla Inc.
- BYD Company Ltd.
- Samsung SDI Co., Ltd.
- LG Energy Solution
- Fluence Energy, Inc.
- Wärtsilä Corporation
- Saft (TotalEnergies)
- Panasonic Holdings Corporation
- Toshiba Corporation
- Contemporary Amperex Technology Co., Limited (CATL)
- ABB Ltd.
- General Electric (GE)
- Hitachi Energy Ltd.
- NextEra Energy, Inc.
- Mitsubishi Heavy Industries, Ltd.
- Sungrow Power Supply Co., Ltd.
- Enphase Energy, Inc.
- SolarEdge Technologies, Inc.
- Powin Energy Corporation
- Kokam Co., Ltd.
Frequently Asked Questions
What is the projected growth rate of the Advanced Battery Energy Storage System market?
The market is expected to grow at a CAGR of 26.4% from 2025 to 2034, driven by the global transition to renewable energy and grid modernization efforts.
Which battery technology currently dominates the market?
Lithium-ion technology, specifically Lithium Iron Phosphate (LFP) and Nickel Manganese Cobalt (NMC), dominates the market due to its high energy density and declining production costs.
How do government policies impact the BESS market?
Policies such as the U.S. Inflation Reduction Act and the EU Green Deal provide tax credits, subsidies, and regulatory mandates that significantly accelerate the deployment of storage systems.
What are the main applications for battery energy storage systems?
The primary applications include utility-scale grid services (frequency regulation and peak load management), commercial peak shaving, and residential energy backup and self-consumption.
Which region is expected to lead the market in the coming years?
Asia Pacific is currently the largest market, but North America is projected to witness the fastest growth rate through 2034 due to extensive grid decarbonization projects.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
