5G Radio Access Network Professional Services Market
5G Radio Access Network Professional Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711408 | Published On : October 31, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
5G Radio Access Network Professional Services Market Size
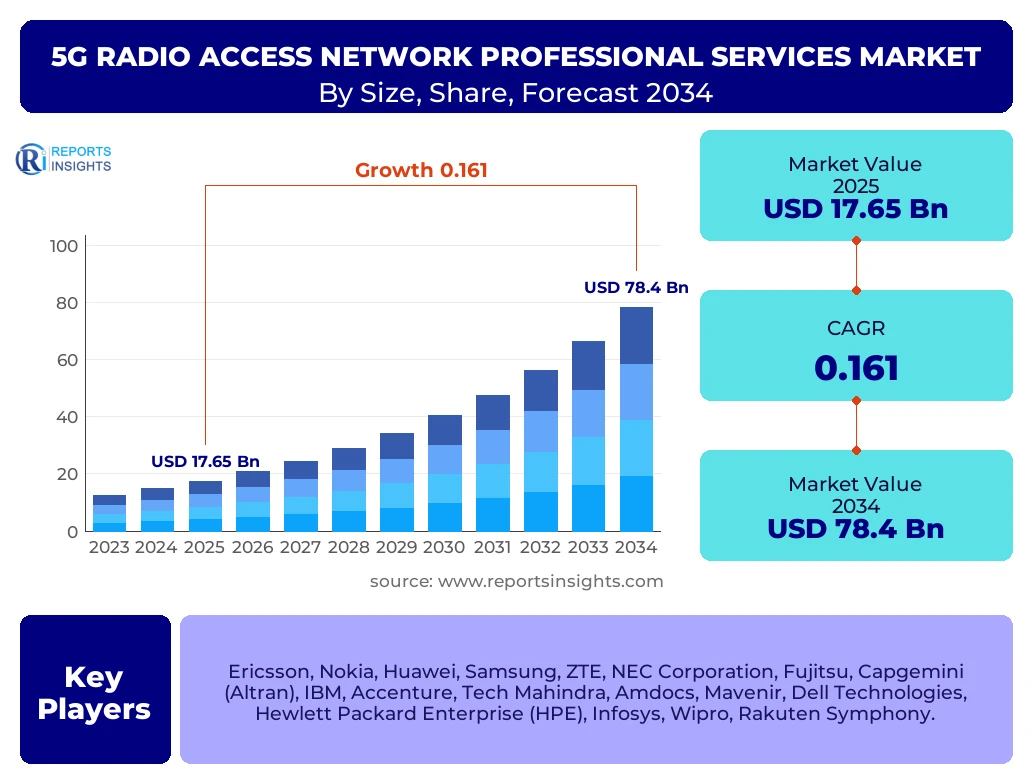
According to Reports Insights Consulting Pvt Ltd, The 5G Radio Access Network Professional Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.1% between 2025 and 2034. The market is estimated at USD 20.5 Billion in 2026 and is projected to reach USD 78.4 Billion by the end of the forecast period in 2034.
Key 5G Radio Access Network Professional Services Market Trends & Insights
The 5G Radio Access Network (RAN) Professional Services market is undergoing a transformative phase driven by the global shift toward disaggregated and virtualized network architectures. Enterprise and telecommunication providers are increasingly seeking specialized expertise to navigate the complexities of Open RAN (O-RAN) integration and AI-driven network optimization. As 5G standalone (SA) deployments accelerate, the demand for professional services has transitioned from basic installation to advanced network slicing, edge computing integration, and automated lifecycle management. This shift reflects a broader industry trend where software-defined infrastructure requires a continuous delivery and integration model, moving away from legacy hardware-centric deployment strategies. Furthermore, the convergence of Information Technology (IT) and Operational Technology (OT) is pushing professional service providers to offer bespoke consulting for private 5G networks in industrial environments.
- North America remains the largest regional market due to early 5G adoption and massive investments in standalone 5G core infrastructures.
- The Asia Pacific region is the fastest-growing market, fueled by rapid urbanization and government-led digital transformation initiatives in China, India, and Southeast Asia.
- Network Planning and Design currently holds the largest market share as operators prioritize efficient spectrum utilization and site densification.
- Support and Maintenance services are experiencing the highest growth rate as the installed base of 5G sites expands and requires long-term operational excellence.
- Open RAN integration services are emerging as a critical sub-segment, allowing operators to mix and match vendors and reduce long-term capital expenditures.
Key Takeaways 5G Radio Access Network Professional Services Market Size & Forecast
The global 5G Radio Access Network professional services market is characterized by a significant move toward automation and cloud-native service delivery. As mobile data traffic continues to surge, operators are forced to optimize their RAN environments using professional services that leverage machine learning for predictive maintenance and real-time interference management. The forecast period indicates a robust transition where traditional network integrators are evolving into digital service partners, providing end-to-end consulting for diverse industry verticals including healthcare, automotive, and smart manufacturing. Strategic partnerships between equipment manufacturers and hyperscale cloud providers are also reshaping the competitive landscape, creating new avenues for professional service growth in hybrid cloud environments.
- The United States leads the market in terms of high-value professional service contracts for enterprise-grade 5G solutions.
- The transition to 5G Standalone (SA) architecture is a primary driver for the increased demand in network configuration and testing services.
- Small cell densification projects are significantly boosting the deployment and integration service segment in urban areas.
- Sustainability and energy-efficient network design have become core components of the professional services portfolio to meet global ESG targets.
- Security consulting for 5G RAN is seeing unprecedented demand due to the increased attack surface of virtualized network functions.
5G Radio Access Network Professional Services Market Drivers Analysis
The primary catalysts for the 5G RAN professional services market include the exponential growth in mobile data consumption and the strategic imperative for operators to lower their cost-per-bit through network modernization. The push for Industry 4.0 is another massive driver, as manufacturing plants require dedicated professional services to deploy low-latency, high-reliability private 5G networks. Furthermore, the global regulatory push for diverse vendor ecosystems is encouraging the adoption of Open RAN, which necessitates complex integration services that only specialized professional firms can provide.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift to Cloud-Native and Open RAN Architectures | +4.5% | Global (Strong in Europe/NA) | 2025–2034 |
| Demand for Private 5G Networks in Industry 4.0 | +3.8% | Germany, Japan, USA | 2026–2032 |
| Network Densification and Small Cell Expansion | +3.2% | China, India, South Korea | 2025–2030 |
| Integration of AI for Autonomous Network Operations | +2.6% | USA, UK, Singapore | 2027–2034 |
5G Radio Access Network Professional Services Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant headwinds such as the high cost of skilled labor and the complexities involved in multi-vendor integration. Regulatory delays in spectrum auctioning in certain developing regions continue to postpone infrastructure projects, thereby affecting the demand for planning and deployment services. Additionally, the lack of standardized protocols in early Open RAN iterations can lead to performance inconsistencies, making some operators hesitant to move away from traditional end-to-end legacy systems.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capex and Operational Complexity | -2.1% | Emerging Markets (LATAM, MEA) | 2025–2028 |
| Shortage of Certified 5G Technical Professionals | -1.8% | Global | 2025–2030 |
| Regulatory and Spectrum Allocation Delays | -1.5% | India, Brazil, Southeast Asia | 2025–2027 |
5G Radio Access Network Professional Services Market Opportunities Analysis
The emergence of the "Network-as-a-Service" (NaaS) model presents a significant opportunity for professional service providers to establish recurring revenue streams. As enterprises seek to outsource their network management, service providers can offer comprehensive managed services covering everything from design to daily operations. Furthermore, the integration of 5G with Satellite (Non-Terrestrial Networks) and the early-stage research into 6G architectures provide a long-term roadmap for professional consulting and R&D services.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Managed Services for Private Enterprise Networks | +5.2% | USA, Germany, China | 2026–2034 |
| 5G Advanced and NTN (Satellite) Integration | +2.4% | Global | 2028–2034 |
| Edge Computing and RAN Convergence | +3.1% | Japan, South Korea, NA | 2026–2032 |
5G Radio Access Network Professional Services Market Challenges Impact Analysis
Interoperability remains the most significant technical challenge in the 5G RAN professional services landscape. Ensuring that software from one vendor works seamlessly with radio units from another requires rigorous testing and validation, which can extend project timelines. Cybersecurity also poses a major challenge, as the decentralized nature of modern RAN increases the number of potential entry points for malicious actors, necessitating advanced security-by-design professional services.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interoperability in Multi-Vendor (Open RAN) Environments | -2.5% | Global | 2025–2030 |
| Increasing Cybersecurity Vulnerabilities in Software-RAN | -1.9% | Europe, North America | 2025–2034 |
5G Radio Access Network Professional Services Market - Updated Report Scope
This report provides a comprehensive analysis of the global 5G Radio Access Network (RAN) professional services market, covering technical deployment, strategic consulting, and operational maintenance. It examines the market through the lens of technological evolution from 4G to 5G and the upcoming transition to 5G-Advanced. The scope includes detailed forecasting of service segments, end-user verticals, and regional market dynamics, ensuring stakeholders have a granular view of investment hotspots and competitive movements.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 17.65 Billion |
| Market Forecast in 2034 | USD 78.4 Billion |
| Growth Rate | 16.1% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Ericsson, Nokia, Huawei, Samsung, ZTE, NEC Corporation, Fujitsu, Capgemini (Altran), IBM, Accenture, Tech Mahindra, Amdocs, Mavenir, Dell Technologies, Hewlett Packard Enterprise (HPE), Infosys, Wipro, Rakuten Symphony. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the 5G RAN professional services market reveals a diverse ecosystem of specialized services tailored to the lifecycle of network deployment. While initial planning and design dominated the early phase of 5G rollout, the market is now pivoting toward complex optimization and integration services. This transition is essential for managing the increased density of small cells and the sophisticated beamforming techniques required for mid-band and millimeter-wave (mmWave) frequencies. The vertical segmentation also highlights a growing trend where non-telecom industries are becoming major consumers of RAN professional services to build their own dedicated private infrastructures.
- Network Planning and Design: Focuses on RF site surveys, link budget analysis, and interference modeling to maximize coverage and capacity.
- Deployment and Integration: Includes physical installation of base stations (gNodeB), cabling, and the logical integration of the RAN with the 5G core.
- Network Optimization: Utilizing drive testing and software-based analytics to fine-tune network parameters for optimal user experience and throughput.
- Support and Maintenance: Ongoing technical support, software patching, and hardware replacement services to ensure 99.999% uptime.
- Consulting and Strategic Advisory: Business case development, spectrum strategy, and digital transformation consulting for operators and enterprises.
- Vertical-Specific Services: Customized solutions for sectors like Smart Manufacturing (URLLC), Healthcare (Remote Surgery), and Automotive (V2X).
Regional Highlights
- North America: Holds the largest market share, driven by aggressive 5G rollout schedules by Tier-1 carriers and the rapid adoption of private 5G networks in the industrial and logistics sectors. The presence of major technology consultancies and a mature cloud ecosystem further bolsters this region.
- Asia Pacific: Identified as the fastest-growing region. Massive government investments in China and South Korea, coupled with the emerging 5G market in India, create a high-volume demand for deployment and optimization services. The region is also a hub for RAN hardware manufacturing, leading to strong local service partnerships.
- Europe: Shows steady growth with a focus on regulatory compliance, security, and Open RAN initiatives. Countries like Germany and the UK are leading the way in industrial 5G applications, requiring high-end consulting and integration services.
- Middle East and Africa: Experiencing a surge in 5G investments in the Gulf Cooperation Council (GCC) countries, particularly for smart city projects. In contrast, Africa is in the early stages, offering long-term growth potential as infrastructure matures.
- Latin America: Market growth is tied to spectrum auctions in Brazil and Mexico, where professional services are needed to upgrade aging 4G infrastructures to 5G compatibility.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the 5G Radio Access Network Professional Services Market.- Ericsson (Sweden)
- Nokia (Finland)
- Huawei (China)
- Samsung Electronics (South Korea)
- ZTE Corporation (China)
- NEC Corporation (Japan)
- Fujitsu Limited (Japan)
- Capgemini Engineering (France)
- IBM Corporation (USA)
- Accenture (Ireland)
- Tech Mahindra (India)
- Amdocs (USA)
- Mavenir (USA)
- Dell Technologies (USA)
- Hewlett Packard Enterprise (USA)
- Infosys Limited (India)
- Wipro Limited (India)
- Rakuten Symphony (Japan)
- Cisco Systems, Inc. (USA)
- Oracle Corporation (USA)
Frequently Asked Questions
What is the current market size of the 5G RAN professional services industry?
The market is estimated to be valued at approximately USD 20.5 Billion in 2026 and is on a trajectory to reach USD 78.4 Billion by 2034, growing at a CAGR of 16.1%.
Which service segment is expected to dominate the market during the forecast period?
Network Planning and Design currently dominates the market share; however, Support and Maintenance along with Optimization services are expected to grow at the highest rates as more networks go live.
How is the rise of Open RAN affecting professional services?
Open RAN increases the demand for professional integration and testing services because it allows for multi-vendor environments, which are more complex to harmonize than traditional single-vendor proprietary systems.
Which region offers the most significant growth opportunities for 5G RAN services?
The Asia Pacific region offers the highest growth potential due to large-scale infrastructure projects in China and India and the rapid digital transformation of manufacturing hubs.
What are the main challenges facing providers in this market?
Key challenges include a global shortage of highly skilled 5G engineers, technical interoperability issues between different vendors, and increasing cybersecurity threats in virtualized network environments.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
