3D Printing Metal Market
3D Printing Metal Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_701312 | Published On : September 19, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
3D Printing Metal Market Size
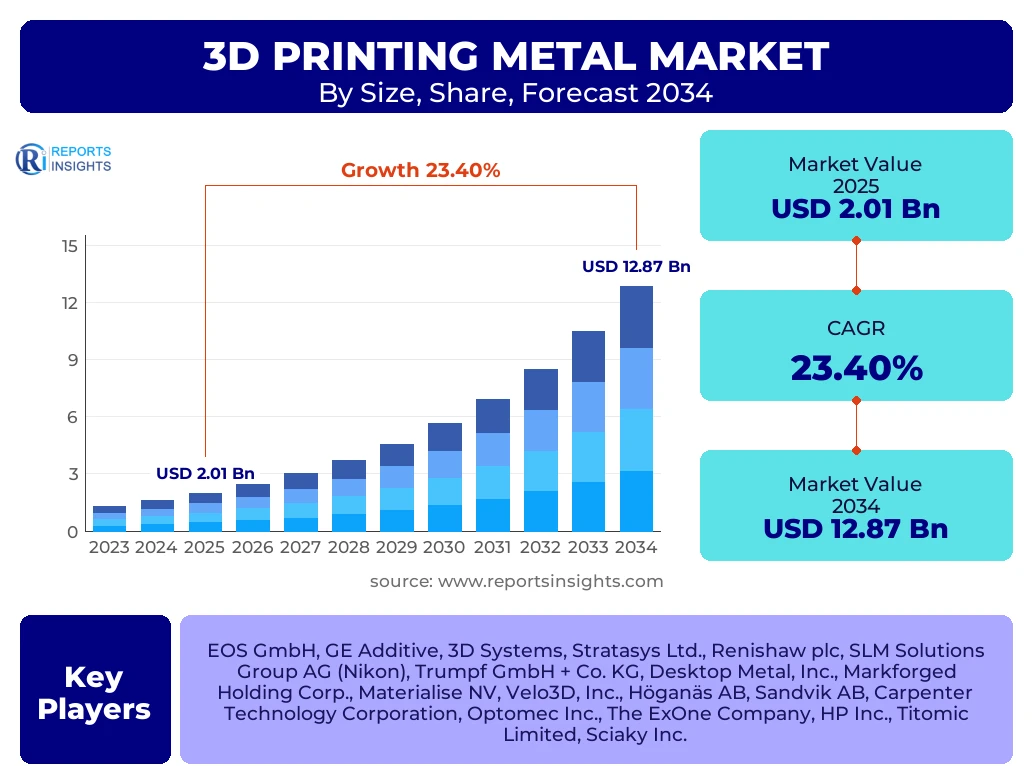
According to Reports Insights Consulting Pvt Ltd, The 3D Printing Metal Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 23.4% between 2026 and 2034. The market is estimated at USD 2.45 Billion in 2026 and is projected to reach USD 12.87 Billion by the end of the forecast period in 2034.
Key 3D Printing Metal Market Trends & Insights
The global 3D printing metal market is undergoing a paradigm shift from rapid prototyping toward large-scale industrial production. Current market inquiries frequently center on the economic viability of metal additive manufacturing (AM) compared to traditional subtractive methods, the development of specialized alloys for extreme environments, and the integration of artificial intelligence for in-situ monitoring and defect detection. High-growth sectors like aerospace and healthcare are increasingly adopting Powder Bed Fusion (PBF) and Directed Energy Deposition (DED) to produce complex, lightweight geometries that were previously impossible to manufacture. Furthermore, the push for decentralized manufacturing and the reduction of carbon footprints are driving enterprises to invest in local 3D printing hubs to mitigate supply chain disruptions.
- North America currently holds the largest market share due to its robust aerospace and defense infrastructure and early adoption of advanced manufacturing technologies.
- The Asia-Pacific region is identified as the fastest-growing market, driven by rapid industrialization in China and India and heavy investment in automotive manufacturing.
- The Powder Bed Fusion (PBF) segment remains the largest technology segment by share, owing to its high precision and compatibility with a wide range of metal powders.
- Titanium is the leading material segment in terms of value, largely due to its high strength-to-weight ratio and bio-compatibility in medical applications.
Key Takeaways 3D Printing Metal Market Size & Forecast
The long-term forecast for the 3D printing metal market suggests a trajectory characterized by technological convergence and material democratization. Strategic analyses indicate that as the cost of high-grade metal powders decreases and print speeds increase, the threshold for mass-production adoption will be reached by 2028. Stakeholders are particularly focused on the "total cost of ownership" and the impact of post-processing automation on overall margins. The market is expected to see significant consolidation as large industrial conglomerates acquire niche technology startups to internalize additive manufacturing capabilities and secure proprietary material formulations.
- The United States is the leading country in the global market, supported by massive government funding for defense-related additive manufacturing projects.
- The Aerospace and Defense sector is the primary contributor to market revenue, utilizing metal 3D printing for engine components, fuel nozzles, and structural brackets.
- Germany maintains a dominant position in Europe, serving as the global hub for high-end 3D printing machine manufacturing and engineering expertise.
- Hybrid Manufacturing, combining additive and subtractive processes in a single machine, is emerging as a critical trend for improving surface finish and dimensional accuracy.
3D Printing Metal Market Drivers Analysis
The primary catalysts for the 3D printing metal market involve the demand for complex lightweight components and the urgent need for supply chain resilience. Industries are moving away from traditional warehousing toward digital inventories, where spare parts are printed on demand. This shift significantly reduces inventory costs and lead times. Additionally, the increasing focus on bio-compatible metal implants in the medical field is propelling the market forward, as 3D printing allows for patient-specific anatomical designs that improve surgical outcomes and recovery times.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Lightweight Aerospace Components | +5.8% | United States, France | 2025–2034 |
| Advancements in Custom Medical Implants | +4.5% | Germany, United Kingdom | 2025–2030 |
| Digital Inventory and On-demand Spare Parts | +3.9% | Global | 2027–2034 |
| Sustainability and Material Waste Reduction | +3.2% | European Union | 2026–2034 |
3D Printing Metal Market Restraints Analysis
Despite the high growth trajectory, the market faces significant restraints, primarily revolving around the high initial capital expenditure (CAPEX) required for industrial-grade metal printers and the expensive nature of high-purity metal powders. Furthermore, the lack of standardized certification processes across different industries creates hurdles for the widespread adoption of 3D-printed parts in safety-critical applications. The requirement for extensive post-processing, such as heat treatment and surface finishing, also adds to the total production time and cost, limiting the technology's competitiveness for simple high-volume parts.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Equipment and Material Costs | -4.2% | India, Brazil, Southeast Asia | 2025–2029 |
| Lack of Industry-wide Quality Standards | -2.8% | Global | 2025–2034 |
| Stringent Regulatory Approvals for Aerospace | -1.5% | North America, Europe | 2025–2030 |
3D Printing Metal Market Opportunities Analysis
The emergence of space exploration and the commercial satellite industry presents a massive opportunity for the 3D printing metal market. Metal AM is uniquely suited for space applications due to its ability to consolidate many parts into a single monolithic structure, reducing weight and potential failure points. Moreover, the development of mid-range, more affordable metal 3D printers is opening the market to small and medium enterprises (SMEs) in the automotive and industrial tooling sectors, which were previously priced out of the technology. The expansion of 3D printing service bureaus also provides an avenue for companies to access metal AM without heavy upfront investment.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Commercial Space Exploration Initiatives | +6.4% | United States (SpaceX/NASA) | 2026–2034 |
| Expansion into the Oil & Gas Sector | +3.7% | Middle East (UAE, Saudi Arabia) | 2027–2034 |
| Development of New High-Entropy Alloys | +4.1% | Japan, South Korea | 2028–2034 |
3D Printing Metal Market Challenges Impact Analysis
A significant challenge facing the industry is the shortage of a skilled workforce capable of handling advanced design for additive manufacturing (DfAM) software and managing complex metal printing systems. Additionally, the safety risks associated with handling reactive metal powders, such as titanium and aluminum, necessitate specialized facility requirements and high operational safety costs. Maintaining consistency across different batches of powder and across different printing machines also remains a technical hurdle for global manufacturers attempting to scale production across multiple geographic locations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Additive Manufacturing Talent | -2.5% | Global | 2025–2034 |
| Operational Safety and Powder Handling Risks | -1.8% | All Manufacturing Hubs | 2025–2034 |
| Difficulty in Achieving Part-to-Part Consistency | -2.1% | Global | 2025–2034 |
3D Printing Metal Market - Updated Report Scope
This report provides an exhaustive analysis of the global 3D printing metal landscape, covering technological advancements, material science breakthroughs, and end-user adoption patterns. It investigates the transition from prototyping to industrial production and provides granular data on market sizing across multiple dimensions. The scope includes a detailed evaluation of the competitive landscape, identifying the strategic moves of key players, and assessing the impact of macroeconomic factors such as trade policies and energy costs on the production of metal powders and printing hardware.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.01 Billion |
| Market Forecast in 2034 | USD 12.87 Billion |
| Growth Rate | 23.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | EOS GmbH, GE Additive, 3D Systems, Stratasys Ltd., Renishaw plc, SLM Solutions Group AG (Nikon), Trumpf GmbH + Co. KG, Desktop Metal, Inc., Markforged Holding Corp., Materialise NV, Velo3D, Inc., Höganäs AB, Sandvik AB, Carpenter Technology Corporation, Optomec Inc., The ExOne Company, HP Inc., Titomic Limited, Sciaky Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The 3D printing metal market is highly fragmented based on the diversity of technologies and materials required for specific industrial applications. Technology segmentation reveals that while Powder Bed Fusion remains the benchmark for complex aerospace parts, Binder Jetting is gaining traction for high-volume automotive components due to its superior speed and lower material costs. From a material perspective, titanium alloys dominate the high-value aerospace and medical markets, while stainless steel and aluminum are widely used in general industrial and automotive prototyping. The market is also segmented by form, where powder is the dominant medium, though wire-fed systems are increasingly utilized in large-format Directed Energy Deposition for repairing large industrial equipment.
- By Technology: The market is split into Powder Bed Fusion (PBF), Directed Energy Deposition (DED), Binder Jetting, and Material Extrusion. PBF is further divided into Selective Laser Melting (SLM) and Electron Beam Melting (EBM).
- By Metal Type: Major metals include Titanium, Stainless Steel, Aluminum, Nickel Alloys (Inconel), Cobalt-Chrome, and Precious Metals (Gold, Silver).
- By End-Use Industry: Key verticals are Aerospace & Defense, Medical & Dental, Automotive, General Manufacturing, and Oil & Gas.
- By Component: Segmentation involves Hardware (Printers), Software (Design and Simulation), Materials (Metal Powder), and Services (3D Printing Bureaus).
Regional Highlights
- North America: Leads in terms of market value, driven by high R&D spending and the presence of industry leaders like GE Additive and 3D Systems. The U.S. Department of Defense's focus on additive manufacturing for tactical advantage is a major growth driver.
- Europe: The second-largest market, with Germany as its epicenter. Europe excels in the manufacturing of high-precision metal 3D printing hardware and has a strong automotive sector integrating 3D printing into supply chains.
- Asia-Pacific: The fastest-growing region, with a CAGR exceeding 25%. China's "Made in China 2025" initiative has significantly boosted domestic metal AM capabilities. Japan and South Korea are focusing on electronics and precision engineering applications.
- Middle East & Africa: Emerging as a hub for Oil & Gas applications, where 3D printing is used to create specialized drilling tools and replace obsolete parts in remote locations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the 3D Printing Metal Market.- EOS GmbH
- GE Additive
- 3D Systems
- Stratasys Ltd.
- Renishaw plc
- SLM Solutions Group AG (Nikon)
- Trumpf GmbH + Co. KG
- Desktop Metal, Inc.
- Markforged Holding Corp.
- Materialise NV
- Velo3D, Inc.
- Höganäs AB
- Sandvik AB
- Carpenter Technology Corporation
- Optomec Inc.
- The ExOne Company (Desktop Metal)
- HP Inc.
- Titomic Limited
- Sciaky Inc.
- Xact Metal
Frequently Asked Questions
What is the projected market size of the 3D Printing Metal Market by 2034?
The global 3D Printing Metal market is expected to reach approximately USD 12.87 Billion by 2034, growing at a robust CAGR of 23.4% from 2026 onwards.
Which metal is most commonly used in 3D printing for medical applications?
Titanium and its alloys are the most commonly used metals for medical 3D printing due to their excellent bio-compatibility, high strength, and resistance to corrosion within the human body.
Which region is expected to exhibit the fastest growth during the forecast period?
The Asia-Pacific region is projected to be the fastest-growing market, driven by heavy industrial investments, government initiatives in China and India, and a burgeoning automotive sector.
What are the main advantages of metal 3D printing over traditional manufacturing?
The primary advantages include the ability to produce complex internal geometries, reduction in material waste, part consolidation (reducing assembly needs), and significant weight reduction through topology optimization.
What are the key challenges hindering the mass adoption of metal 3D printing?
Key challenges include the high cost of industrial machines and metal powders, the necessity for extensive post-processing, and the current lack of global standardization for part certification.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
